


EN
Avery Dennison (AVY) Guidance Update Puts Valuation Back In Focus
Avery Dennison (AVY) just paired fresh earnings guidance for 2026 with a reaffirmed cash dividend, giving investors new information on both expected profit levels and near term income potential from the stock.
The recent guidance and dividend update land after a patchy year for the share price. A 30 day share price return of 6.6% and a 90 day share price return of 7.26% suggest momentum has picked up ahead of and around Avery Dennison’s Q3 beat and higher full year earnings outlook. However, a 1 year total shareholder return of 5.85% and a 5 year total shareholder return that declined 8.67% highlight how the longer term picture has been more muted.
Capitalize on Avery Dennison's fresh guidance and dividend signal by scanning a curated shortlist of resilient materials and industrials with the 30 resilient stocks with low risk scores.Avery Dennison shares have already reacted to the fresh earnings outlook and steady dividend, so the real decision now is whether to lean into this reset or wait for a cheaper entry. Valuation has to break that tie next.
Most Popular Narrative: 10% Undervalued
Avery Dennison’s most followed narrative sets a fair value of $201.80 against a last close of $182.06, so the current reset sits at a discount while still leaning on the same core growth drivers investors have been watching for years.
The ongoing shift in the Materials Group toward high value categories like Specialty and Durable Labels, Embelex, Vestcom and new architectural films, while still growing core label materials, may improve mix quality and support both segment revenue and adjusted EBITDA margins over time.
See why 12 investors see Avery Dennison as 10% undervalued.
Result: Fair Value of $201.80 (UNDERVALUED)
Still, Avery Dennison’s story hinges on inventory prebuys unwinding cleanly and on raw material inflation not eroding the margin progress analysts are banking on.
Find out about the key risks to this Avery Dennison narrative.
Another View On Avery Dennison’s Valuation
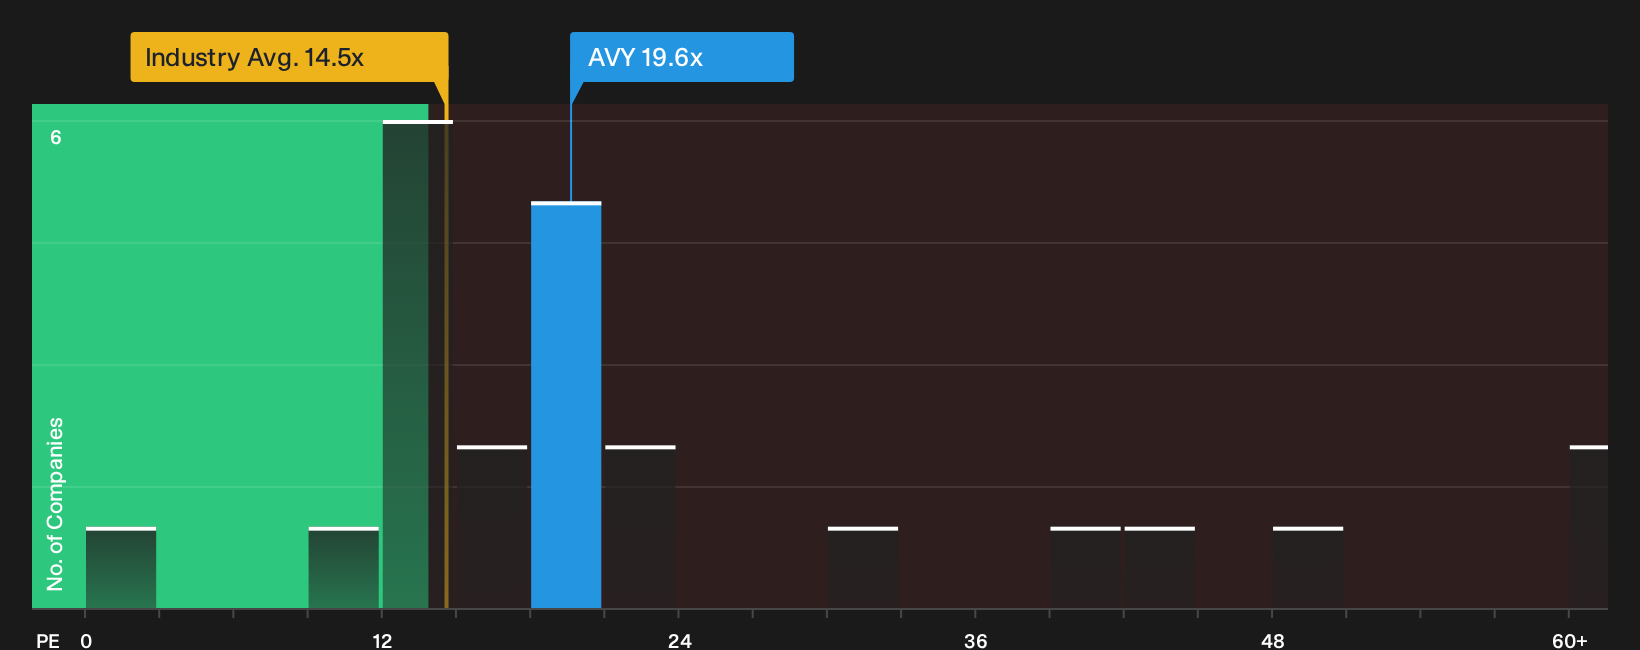
The first narrative leans on analyst fair value around $201.80 per share. A different lens tells a more cautious story. Avery Dennison trades on a P/E of 19.6x while the fair ratio is 18.4x, above the global packaging average of 14.5x and below peers at 27.3x. That mix points to both relative strength and valuation risk. Which side of that trade-off matters more for you?
For a closer look at how this pricing gap lines up with earnings power and sector benchmarks, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Avery Dennison so far, right? If that blend of risks and bright spots feels worth your time, take a closer look for yourself with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Avery Dennison?
If Avery Dennison has sharpened your focus, you can broaden your opportunity set with data backed stock ideas that match different risk, income, and quality preferences.
- Chase upside with targeted smaller companies by scanning the 9 elite penny stocks with strong financials that clear strict financial filters.
- Strengthen your core holdings with the 30 high quality undervalued stocks that pair quality fundamentals with pricing that still looks reasonable.
- Prioritise resilience and balance sheet strength by reviewing the list of solid balance sheet and fundamentals (23 results) that can help anchor a long term portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com