


EN
FormFactor (FORM) Stock Price Drops After Q3 Earnings Beat Spurs Margin Questions
FormFactor came into Q3 2026 earnings on a slide, with the stock already down sharply over the past month and then dropping a further 11.7% to US$97.46 the day after results. That move suggests investors expected perfection. The reported quarter instead delivered strong numbers, with revenue at US$280.5m and non GAAP earnings per share at US$1.04, powered by high end probe cards and photonics systems.
The real tension for you as a shareholder is simple: the market just punished FormFactor on a day when the income statement looked anything but weak.
Investors may appreciate the recent earnings strength from FormFactor but feel uneasy after the sharp decline in its share price. Consider exploring our curated list of resilient stocks with more stable recent trading activity in the 30 resilient stocks with low risk scores
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$280.5m vs. US$202.7m (up roughly 38%)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$73.8m vs. US$15.7m (very large year over year increase, roughly 4.7x)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.94 vs. US$0.20 (up roughly 364%)
- Non GAAP Gross Margin (Q3 2026 vs. Q2 2026): 56.5% vs. roughly 53.3% (up about 320 basis points quarter over quarter)
Tired of scrolling through extensive earnings commentary and raw figures trying to piece together what FormFactor really looks like financially today? Get the full visual picture in one place, with a clear view of its valuation profile through our company report for FormFactor.
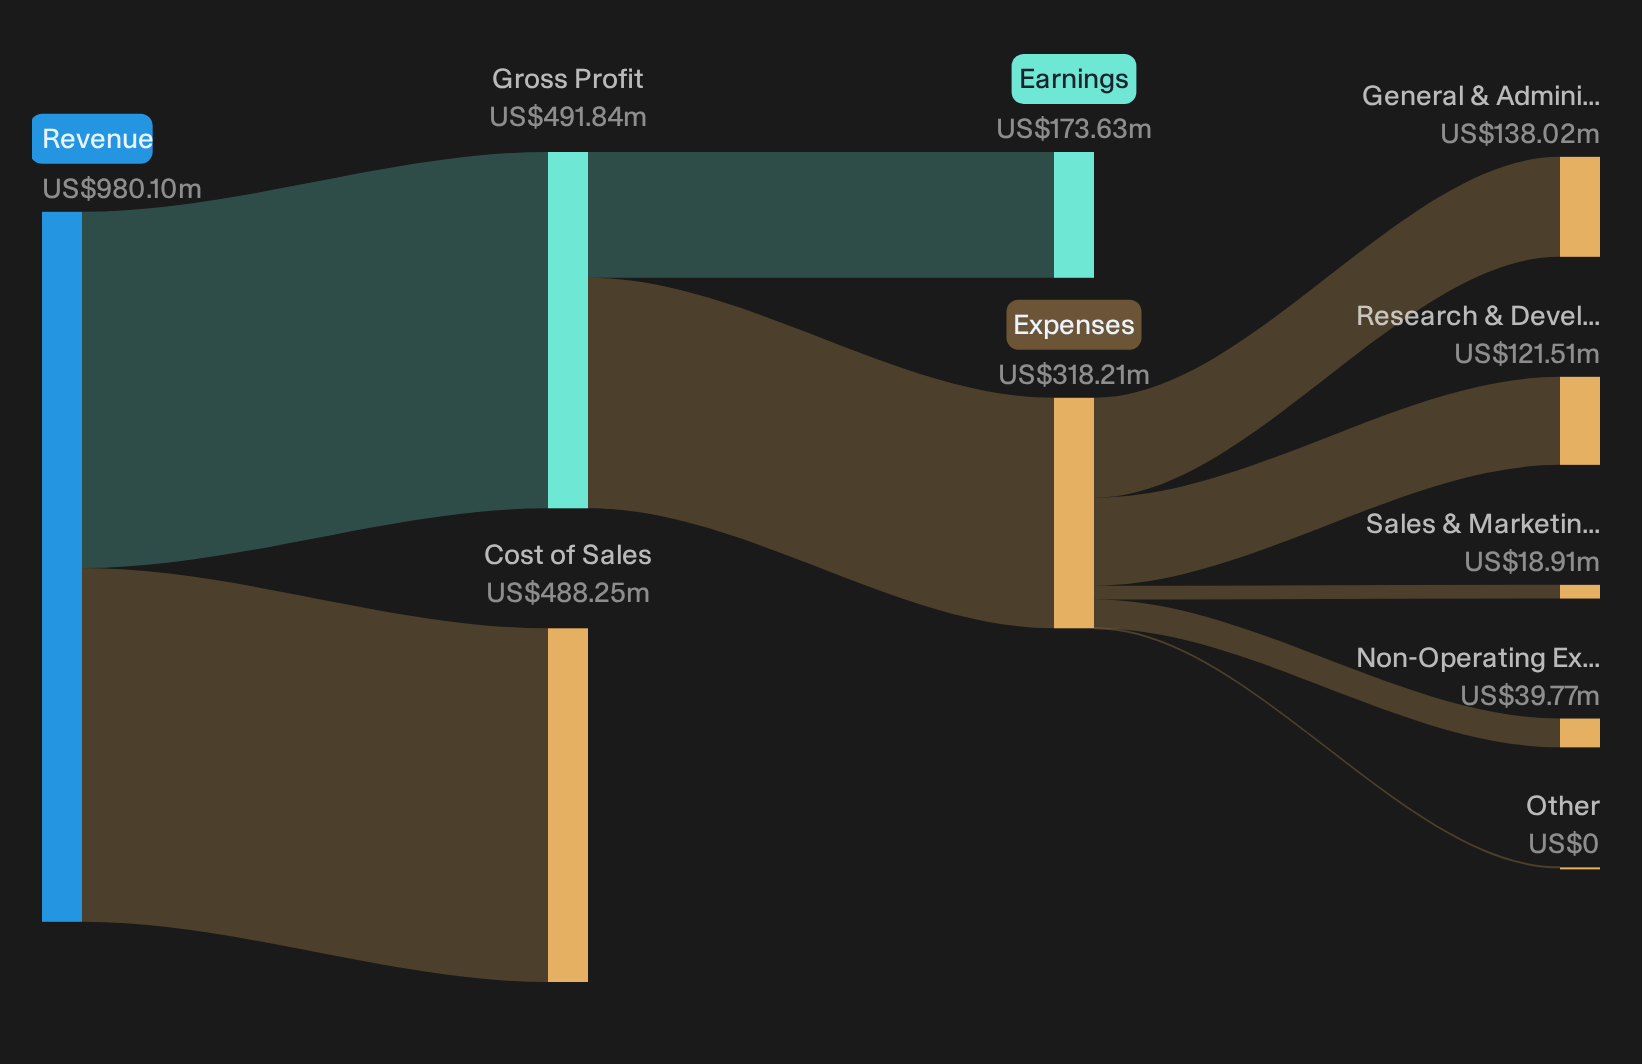
FormFactor’s Bull Story Meets Concrete Milestones
The bullish pitch centers on FormFactor turning capacity and partnerships into broader, more durable demand across probe cards and Systems.
"The main factor that has to go right is that FormFactor converts its current capacity buildout and customer partnerships in areas such as CPO, GPUs, and advanced packaging into sustained, diversified demand beyond DRAM and HBM."
Q3 results point in that direction. TRITON photonics revenue for 2026 is now expected above US$30m, compared with the US$10m to US$20m view at the start of the year. Systems revenue reached US$59.5m and Farmers Branch has begun shipping, so the capacity build is moving from slideware into actual output.
One Narrative disagrees with today's price. → See where this Narrative says FormFactor should trade.
FormFactor Margins: One Off Help, Real Cost Pressure
Bearish investors worry that FormFactor’s recent profitability depends too heavily on temporary helpers rather than durable pricing or mix.
"While the company highlights structurally higher non GAAP gross margin around 51% at recent volumes, a significant portion of the most recent margin uplift comes from temporary IEEPA tariff refunds and precious metal reclaim, so the roll off of these non recurring benefits could pressure gross margin and net income if underlying mix and pricing do not fully compensate."
The latest quarter partly backs that concern. Reported non GAAP gross margin reached 56.5%, yet management attributes roughly US$8.6m to US$10.5m to one time items and pegs the sustainable level nearer 52.5% to 53%. Q4 guidance still leans on remaining refunds, so the test of true margin resilience is deferred.
Hunt For FormFactor Style Dislocations
FormFactor just showed how strong operating numbers and a sliding share price can coexist. The real opportunity is spotting stocks that could be undervalued before the market catches up.
- Company 1 - 38% below our estimate - uses expanded manufacturing and supply chain capacity to sell higher margin film and services through deeper OEM and dealer channels.
- Company 2 - 21% below our estimate - expands a surgical robotics platform from joint replacements into broader procedures as hospitals upgrade capital equipment and integrate connected care offerings.
- Company 3 - 23% below our estimate - ties cloud infrastructure, workplace software and AI assistants together so enterprises shift everyday workflows and development directly onto its ecosystem.
That is three of the list. See every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com