


EN
Home Depot (HD) Moved Higher, What Is Drawing Attention Now?
Investor focus on Home Depot (HD) has intensified ahead of its upcoming fiscal third quarter earnings release, as the retailer balances its outlook for profit growth, softer big ticket renovation demand, and reaffirmed sales and margin guidance.
At a recent share price of US$328.98, Home Depot has seen a 14.21% 1 month share price return but remains down 4.87% on a year to date basis, while the 1 year total shareholder return has declined 10.87% even as the 3 year total shareholder return has gained 20.64%.
Compare how Home Depot stacks up against other retailers facing similar renovation trends by scanning the hand picked 30 high quality undervalued stocks that combine quality fundamentals with discounted share prices.
After a sharp 1 month rebound but weaker returns over 1 and 5 years, Home Depot now trades at a discount to analyst targets yet a premium to intrinsic estimates. Which signal does that gap really support?
Most Popular Narrative: 15% Undervalued
Against the last close at $328.98, the most followed narrative pegs Home Depot’s fair value at $385, which implies a material valuation gap that hinges on how the Pro-focused strategy plays out.
Home Depot is evolving from a traditional big-box home improvement retailer into a comprehensive supplier ecosystem for professional contractors (“Pros”), while continuing to serve DIY customers through stores, digital tools, and faster fulfillment. Recent acquisitions (including SRS Distribution and GMS) expand its reach into specialty distribution for roofing, drywall, HVAC, and other complex project categories, enlarging the addressable market toward roughly $1.2 trillion and the Pro segment opportunity near $700 billion.
See why 11 investors see Home Depot as 15% undervalued.
Result: Fair Value of $385 (UNDERVALUED)
Still, the Home Depot narrative can crack if elevated mortgage rates keep housing turnover muted for longer and if acquisitions fail to deliver the expected Pro lift.
Find out about the key risks to this Home Depot narrative.
Another Look At Home Depot’s Valuation
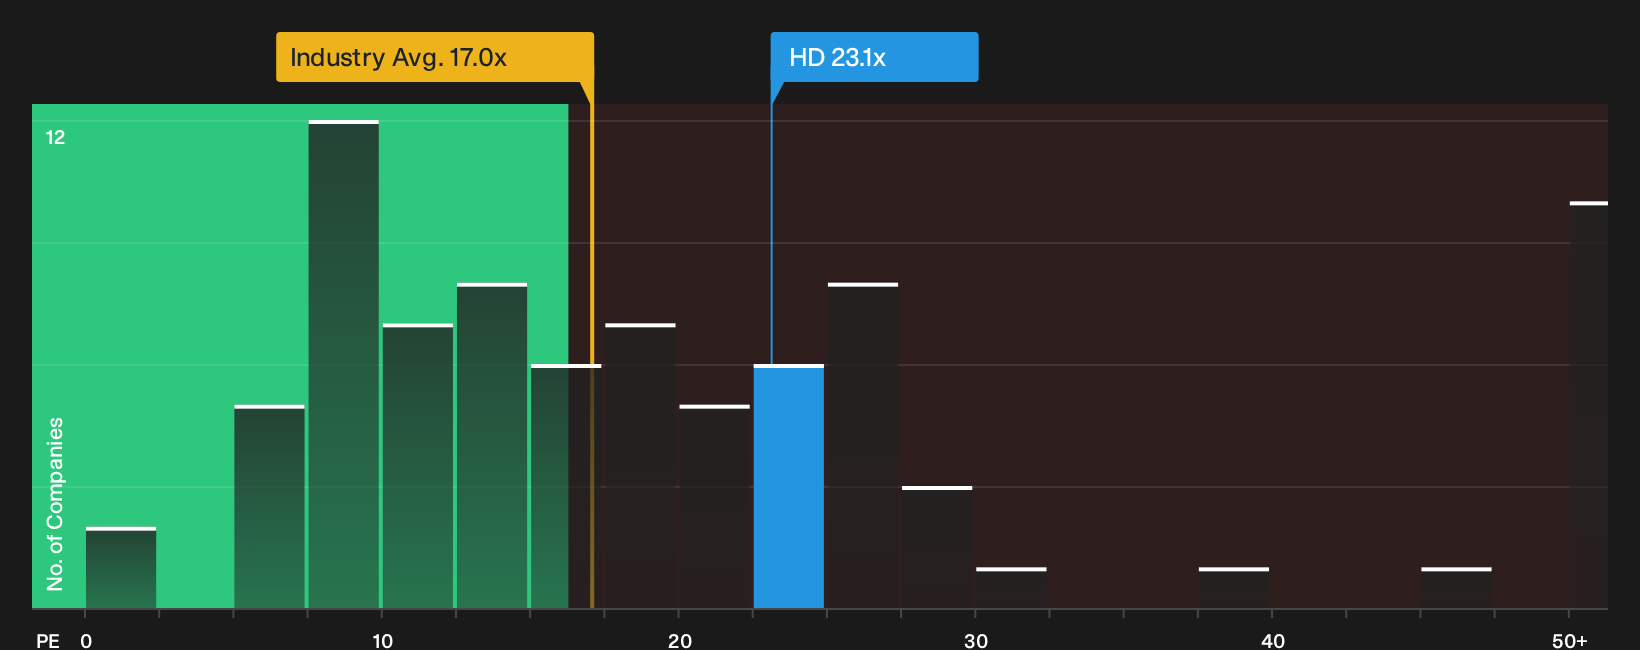
That $385 fair value puts Home Depot in the “undervalued” camp, but the earnings multiple tells a different story. The stock trades on a P/E of 23.1x, compared with 17x for the US Specialty Retail group, 22.2x for peers, and a fair ratio of 21.7x. That suggests investors are already paying up, so is this really a bargain or just a quality premium?
To stress test that richer P/E and see what the earnings profile implies for risk and potential upside, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages around Home Depot and its valuation are everywhere. Move quickly, test the numbers yourself, and weigh both caution and optimism by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Home Depot?
Do not stop your research with Home Depot. Broaden your watchlist now and give yourself more options before the next round of earnings headlines hits.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (22 results).
- Hunt for quality at a discount by reviewing the 18 high quality undiscovered gems.
- Prioritize capital protection and stability by checking the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com