


EN
COSCO SHIPPING Energy Transportation (SEHK:1138) Stock Sees Q3 Earnings Power Build
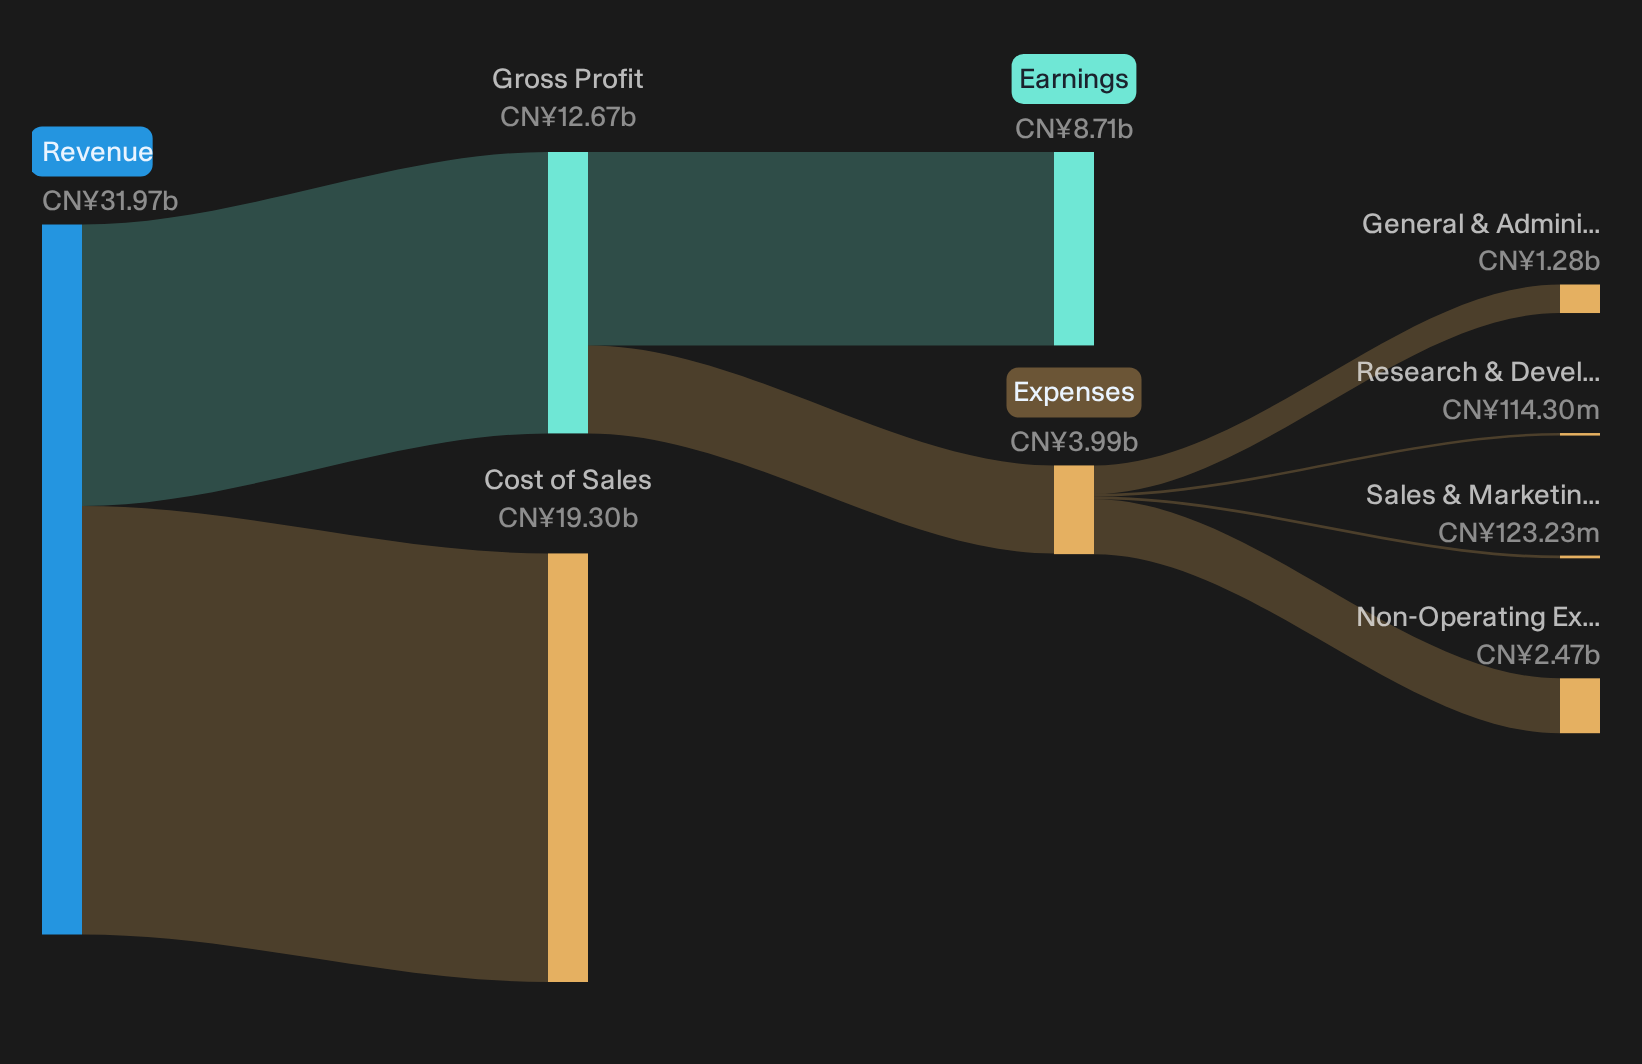
COSCO SHIPPING Energy Transportation closed at HK$16.99 after Q3 2026 results, with the stock roughly flat over the past week and up strongly over three months. The headline is simple: earnings power in this tanker owner keeps building. Basic earnings per share reached 0.52 CNY for the quarter and trailing net profit margin sits at 27.2%, which is high for a capital heavy shipping business.
Short term traders may focus on the recent 30 day pullback of about 5%. Longer term holders are more likely watching the sharp multi quarter earnings expansion and asking whether a 9.1x P/E still prices in that run rate.
Like the earnings power at COSCO SHIPPING Energy Transportation but unsure how a 27.2% net margin and a single digit P/E stack up against peers in tougher shipping cycles? Compare SEHK:1138 with a wider set of resilient tanker and transport operators in our list of solid balance sheet and fundamentals stocks (206 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): 10,097.4m CNY vs 5,521.0m CNY (approximately 2x)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): 2,844.1m CNY vs 848.9m CNY (more than 3x)
- Basic EPS (Q3 2026 vs Q3 2025): 0.5198 CNY vs 0.1779 CNY (approximately 3x)
- Trailing Net Profit Margin: 27.2% vs 14.4% a year earlier (higher profitability on recent revenue)
Earnings jumped faster than the share price multiple. Ask Charlie what COSCO SHIPPING Energy’s earnings surge says about value.
Earnings Momentum and Governance Support Bullish View
COSCO SHIPPING Energy Transportation looks better backed by hard numbers than the earlier cautious optimism implied. Revenue and net income for Q3 2026 are both several times higher than a year ago, while basic EPS has moved in the same direction. A 27.2% trailing net margin, up from 14.4%, suggests the tanker fleet is converting that higher activity into solid profitability. Recent board and risk committee changes also point to tighter oversight. For investors leaning positive, this combination of earnings strength and cleaner governance supports confidence in the current business setup.
Cyclical, Capital-Heavy Risks Not Fully Parked
Bears still have some hooks. Shipping remains a capital heavy, cyclical field, and the revenue and profit surge says more about the current phase of the freight cycle than about long run stability. The 30 day share price decline of about 5%, even after strong Q3 metrics, underlines that sentiment can cool quickly when investors worry about future day rates or overcapacity. High margins help absorb shocks today but do not remove exposure to freight swings, policy shifts or large ongoing investment needs in the tanker and LNG fleets.
High margins and a recent share pullback already hint at fragile freight economics and capital demands that can turn quickly. Before assuming COSCO SHIPPING Energy Transportation has fully tamed those swings, review our independent risk analysis for COSCO SHIPPING Energy Transportation which shows 1 important warning sign
Hunt For Mispriced Earnings Power
COSCO SHIPPING Energy Transportation reports a strong quarter followed by a softer recent trading period. The real opportunity is finding stocks that could be undervalued before the market adjusts expectations.
- Company 1 - 16% below our estimate - applies contract manufacturing capacity to higher value photonics packaging work as AI data centers increase specialized component orders.
- Company 2 - 34% below our estimate - turns a concentrated residential land bank into funded housing projects supported by targeted government mortgage programs.
- Company 3 - 45% below our estimate - reassesses lending as rising credit provisions and political uncertainty reshape risk across a key profit center.
That is three of the list. See every one of the 194 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com