


EN
McDonald's (MCD) Challenges Tokenized Trading, Is The Stock Overvalued?
McDonald's (MCD) has formally objected to its shares being listed on the OKX ICE tokenized stock venue, joining other large corporates that are pushing back on this experimental trading format under the SEC innovation exemption.
For context, McDonald's shares closed at US$257.38 after a 1-day share price return of 2.75%, extending a 30-day share price gain of 10.00%, even as the year-to-date share price is down 15.13% and the 1-year total shareholder return has declined 12.71%.
This mix of a recent share price rebound and weaker longer term total shareholder returns suggests that momentum has started to rebuild ahead of the upcoming November 4 earnings release. Headlines around tokenized trading and overseas marketing developments are also drawing additional attention to how investors evaluate both growth potential and risk in the stock.
Spot emerging momentum shifts around McDonald's by scanning a hand-picked 30 high quality undervalued stocks that shows stronger fundamentals and potential upside than recent headlines suggest.After a sharp bounce but weaker 1-year return, McDonald’s now presents a simple fork in the road. Investors must decide whether to lean into the recent move or wait and see what the current valuation really offers.
Most Popular Narrative: 10% Overvalued
According to the most followed McDonald's valuation narrative, the fair value sits at $233.67 compared with the recent close at $257.38. This frames the current rebound as pricing in more optimism than that model supports.
So, in resume, I forecast that McDonald's will expand its margins through an increase in efficiency of its operations (probably with the aid of AI) but will also see its revenue growth slow down, probably below the economy growth rate given the maturity of the business and the decrease of consumer spending.
See why 56 investors see McDonald's as 10% overvalued.
Result: Fair Value of $233.67 (OVERVALUED)
Still, two things could quickly challenge this McDonald's overvaluation story: a softer consumer that undercuts pricing power, and any setback in AI driven efficiency gains.
Find out about the key risks to this McDonald's narrative.
Another View On McDonald's Valuation
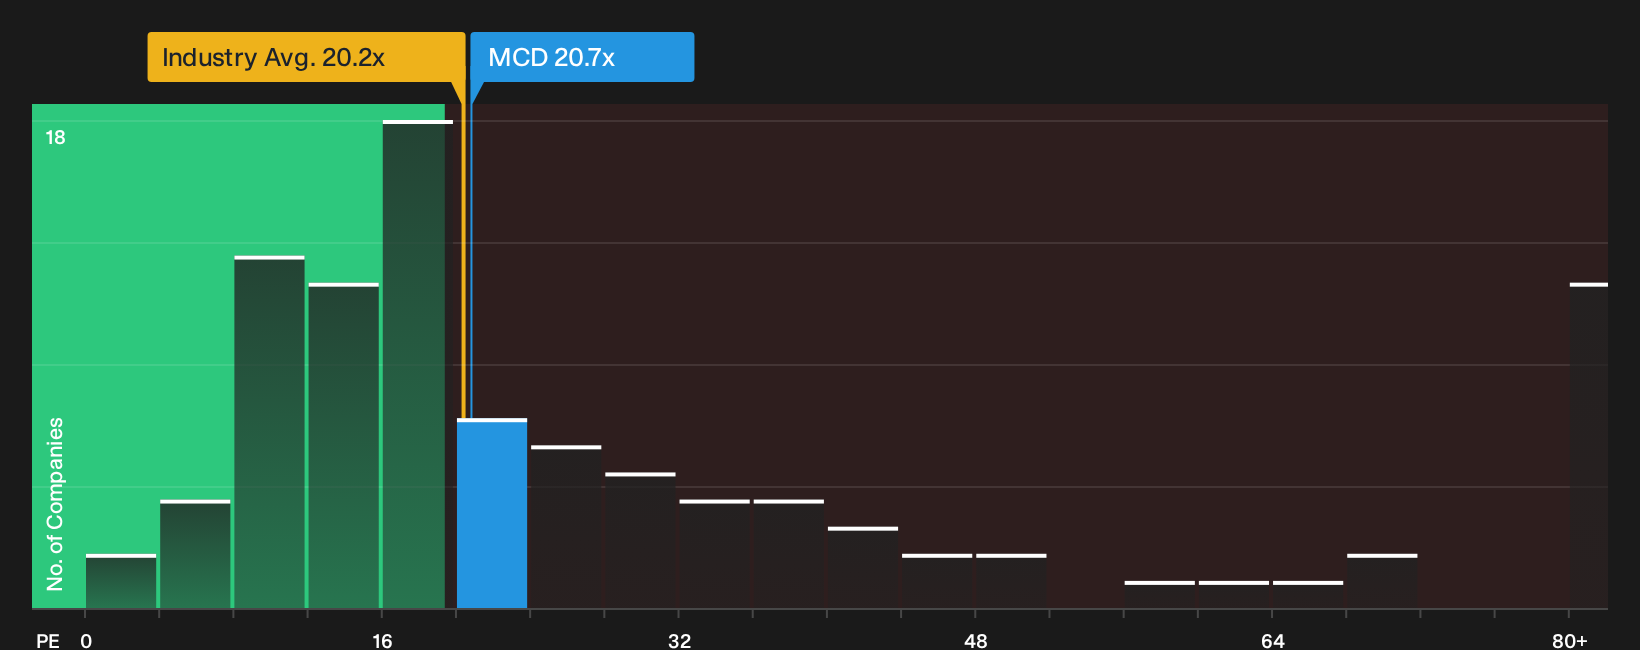
The community narrative leans on detailed cash flow work and ends up calling McDonald's overvalued. The Simply Wall St valuation tool that focuses on the P/E ratio paints a different picture, with MCD at 20.7x earnings versus a fair ratio of 24.6x.
That multiple is slightly higher than the wider US Hospitality sector at 20.2x, yet it still implies the stock trades below what the market could move towards if sentiment improved. For anyone weighing these signals side by side, the real question is which risk feels bigger: paying up a little on earnings, or trusting long term cash flow assumptions.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around McDonald's outlook can feel confusing, so move quickly from headlines to hard data and weigh both sides of the story using our breakdown of 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond McDonald's?
If you stop with McDonald's you only see one angle. Broaden your watchlist using the Simply Wall St Screener and compare fresh ideas side by side.
- Target resilience first and stress test your portfolio against shocks with a curated set of companies ranked as 30 resilient stocks with low risk scores.
- Hunt for real value and benchmark McDonald's against a focused collection of 30 high quality undervalued stocks that pair solid cash flows with healthier balance sheets.
- Pursue future leaders early by scanning a refined group of 18 high quality undiscovered gems before they attract mainstream attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com