


EN
What Waste Connections (WCN) Earnings Beat Means For Shareholders
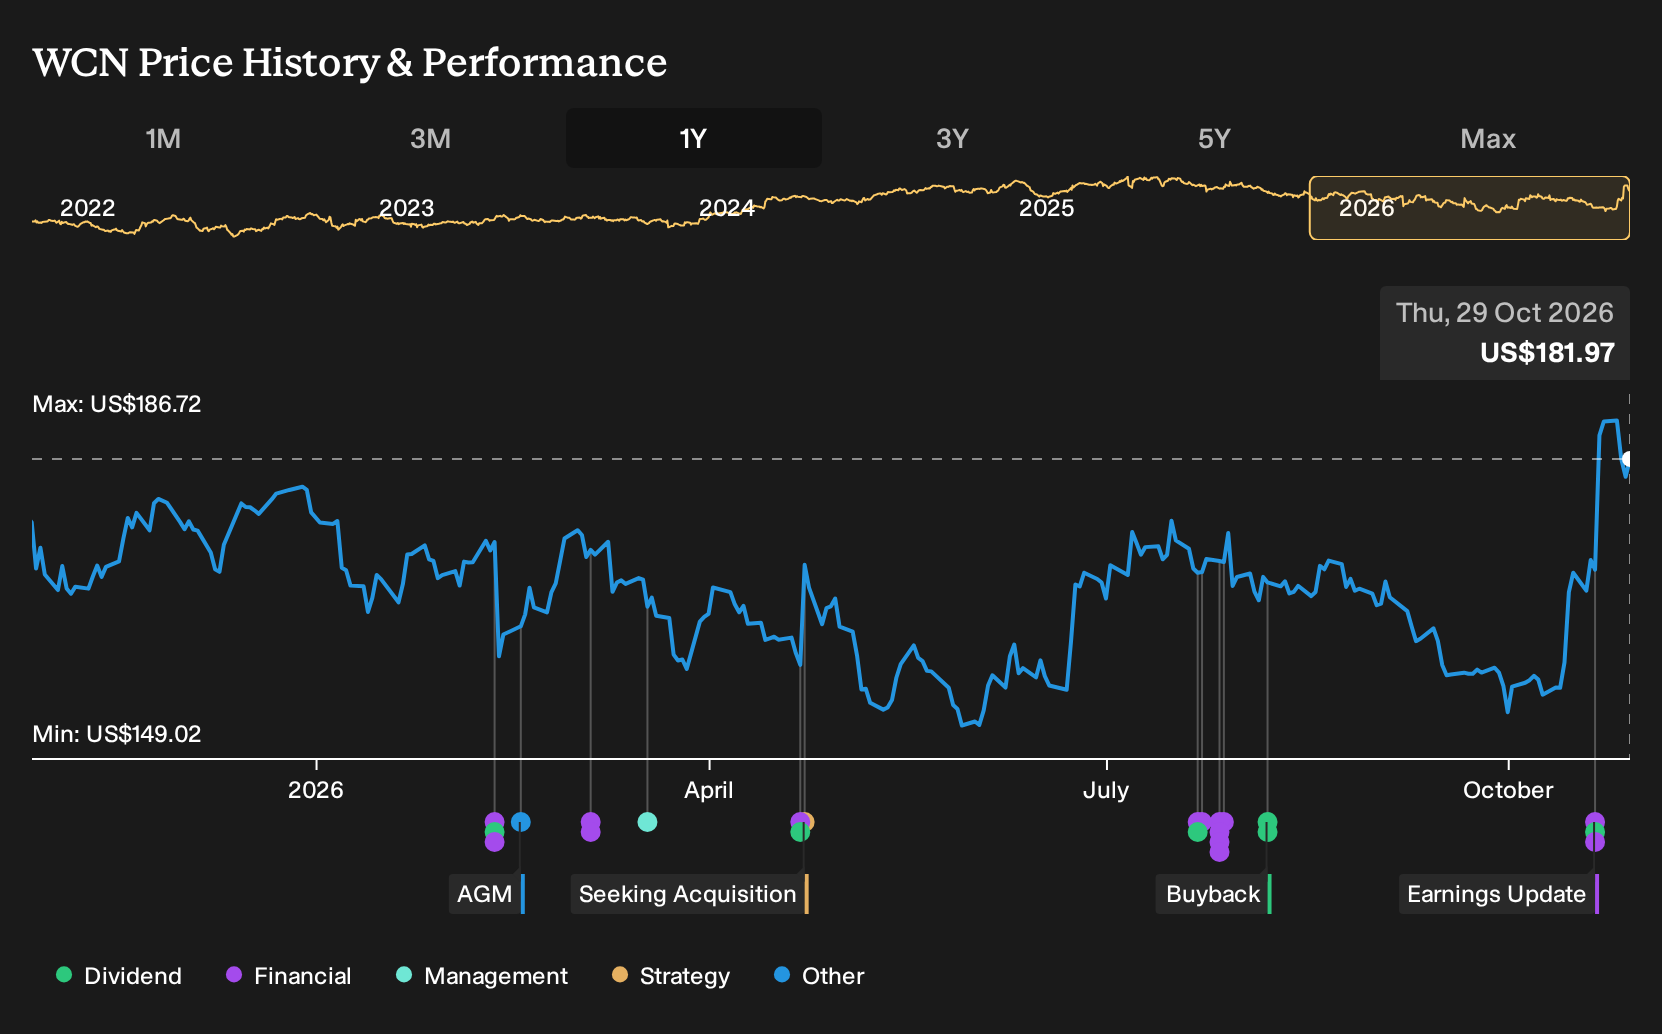
- Waste Connections reported third quarter 2026 sales of US$2,638.08 million and net income of US$359.22 million, alongside a 10% increase in its quarterly dividend to US$0.385 per share and updated full year 2026 guidance that now points to approximately US$10.09 billion of revenue and US$1.182 billion of net income.
- This combination of higher earnings, a larger cash payout and clearer full year targets provides fresh information on how Waste Connections is balancing growth investments, Chiquita related spending and shareholder returns.
- The focus now turns to how this stronger quarter and higher dividend influence Waste Connections' existing investment narrative and risk profile.
Scan how Waste Connections’ latest earnings and dividend move compare with peers by lining up its profile against 30 resilient stocks with low risk scores, which is built to weather tougher conditions.
Waste Connections Investment Narrative Recap
To own Waste Connections, you need to be comfortable with a story built on pricing discipline, steady execution in solid waste and a long build of AI and digital projects, while cash is still being pulled into Chiquita Canyon remediation. The latest quarter, with higher sales, earnings and updated 2026 guidance, broadly supports that operating thesis.
The immediate swing factor remains how quickly free cash flow feels cleaner as Chiquita spending tapers and as fuel and other input costs are managed. The biggest risk still sits in remediation cash outflows or fuel costs running hotter than planned, which could blunt near term margin progress and slow that cash conversion improvement.
The most relevant development here is the updated full year 2026 guidance that points to about US$10.09b of revenue and US$1.182b of net income. Those figures give you a clearer anchor for stress testing key moving parts, especially landfill remediation, fuel surcharges and the timing of AI and routing efficiency benefits.
Against the existing catalysts, firmer guidance helps you judge whether pricing tools, workforce retention gains and tuck in deals are translating into the earnings profile analysts have been modelling. It also makes it easier to weigh that progress against the known risks, including Chiquita related cash drag, higher debt levels and the multi year payback on digital projects.
What The Current Analyst Framework Implies
Analysts are effectively asking you to underwrite a Waste Connections story that leans on a few clear numbers. Revenue is assumed to climb at about 6.0% a year over the next three years. Profitability is expected to shift from an 11.4% margin today to 14.3% by 2029 as AI tools, routing gains and workforce improvements work through the model.
The same playbook underpins the earnings line. Forecast profit is pegged at US$1.7b by 2029, compared with US$1.1b of earnings today. That is an earnings increase of about US$0.6b over the period, with consensus expecting that change to land in a relatively tight range. Waste Connections’ narrative projects US$11.8b of revenue and US$1.7b of earnings by 2029. This requires roughly 6.0% yearly revenue growth and about US$0.6b of earnings increase from US$1.1b of earnings today.
Those assumptions feed straight into how the stock is being framed. The consensus price target of US$206.90 rests on the idea that the business reaches those 2029 numbers and trades on a P/E of 35x at that point, compared with about 40.2x today and an industry multiple around 18.9x. That gap to the sector indicates that analysts are still pricing in a premium for Waste Connections’ perceived quality, AI and digital optionality and M&A pipeline, while also incorporating Chiquita and capital intensity concerns through a lower future multiple.
Uncover why Waste Connections' fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The most bullish analysts lean hard into Waste Connections’ renewable natural gas buildout as the extra gear. They were already pencilling in about US$12.0b of revenue and US$1.9b of earnings by 2029 before this earnings beat and dividend hike. You can compare that optimism with more cautious views, then decide which story fits your expectations.
Explore 2 other Waste Connections fair value estimates, including one that suggests as much as 55% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Waste Connections research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Waste Connections. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waste Connections' overall financial health at a glance.
Looking for more investment ideas beyond Waste Connections?
If this Waste Connections update has sharpened your view on quality, risk and income, you can apply the same lens across the market using the Simply Wall St Screener and quickly surface stocks that fit different roles in your portfolio.
- For investors who care most about financial resilience and balance sheet strength, start with a curated list of solid balance sheet and fundamentals (22 results) that can handle tougher conditions without stretching their finances.
- If value is your priority and you want businesses where quality and pricing look out of sync, scan through a focused group of 30 high quality undervalued stocks that combine cash generation with room for sentiment to catch up.
- When stability and income matter more than short term swings, concentrate on companies that have delivered reliable payouts through a set of 7 dividend fortresses built for yield focused investors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com