


EN
Stock Yards Bancorp (SYBT) Q3 Earnings Sustain Margin Strength And Premium Debate
Stock Yards Bancorp came into this Q3 2026 earnings print with a premium P/E tag and a reputation as a high quality regional bank. The stock still climbed about 2.5% on the day to roughly US$78.70, even after a solidly profitable quarter that did not produce fireworks. What really jumps out is the core banking engine. Net interest margin held at 3.88% and basic earnings per share reached about US$1.41, which is enough to keep the long term thesis intact but not enough to close the valuation debate.
Like the quality of Stock Yards Bancorp’s core banking engine but uneasy about paying a premium P/E for steady rather than explosive earnings? Scan the 30 high quality undervalued stocks.
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$119.3m vs. US$99.5m (up about 19.8%)
- Net Income (Excluding Extraordinary Items, Q3 2026 vs. Q3 2025): US$43.5m vs. US$36.2m (up about 20.1%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.41 vs. US$1.23 (up about 13.9%)
- Net Interest Margin (Q3 2026 vs. Q3 2025): 3.88% vs. 3.56% (wider by about 0.32 percentage points)
Earnings tell one story, but investors who care about what they are paying for the business often focus on the durability of Stock Yards Bancorp's cash flows instead of a single quarter's profit line.
On those cash flows alone, Stock Yards Bancorp's share price could be implying a wider gap to estimated value, and on that basis the stock could be a hefty 35% undervalued.
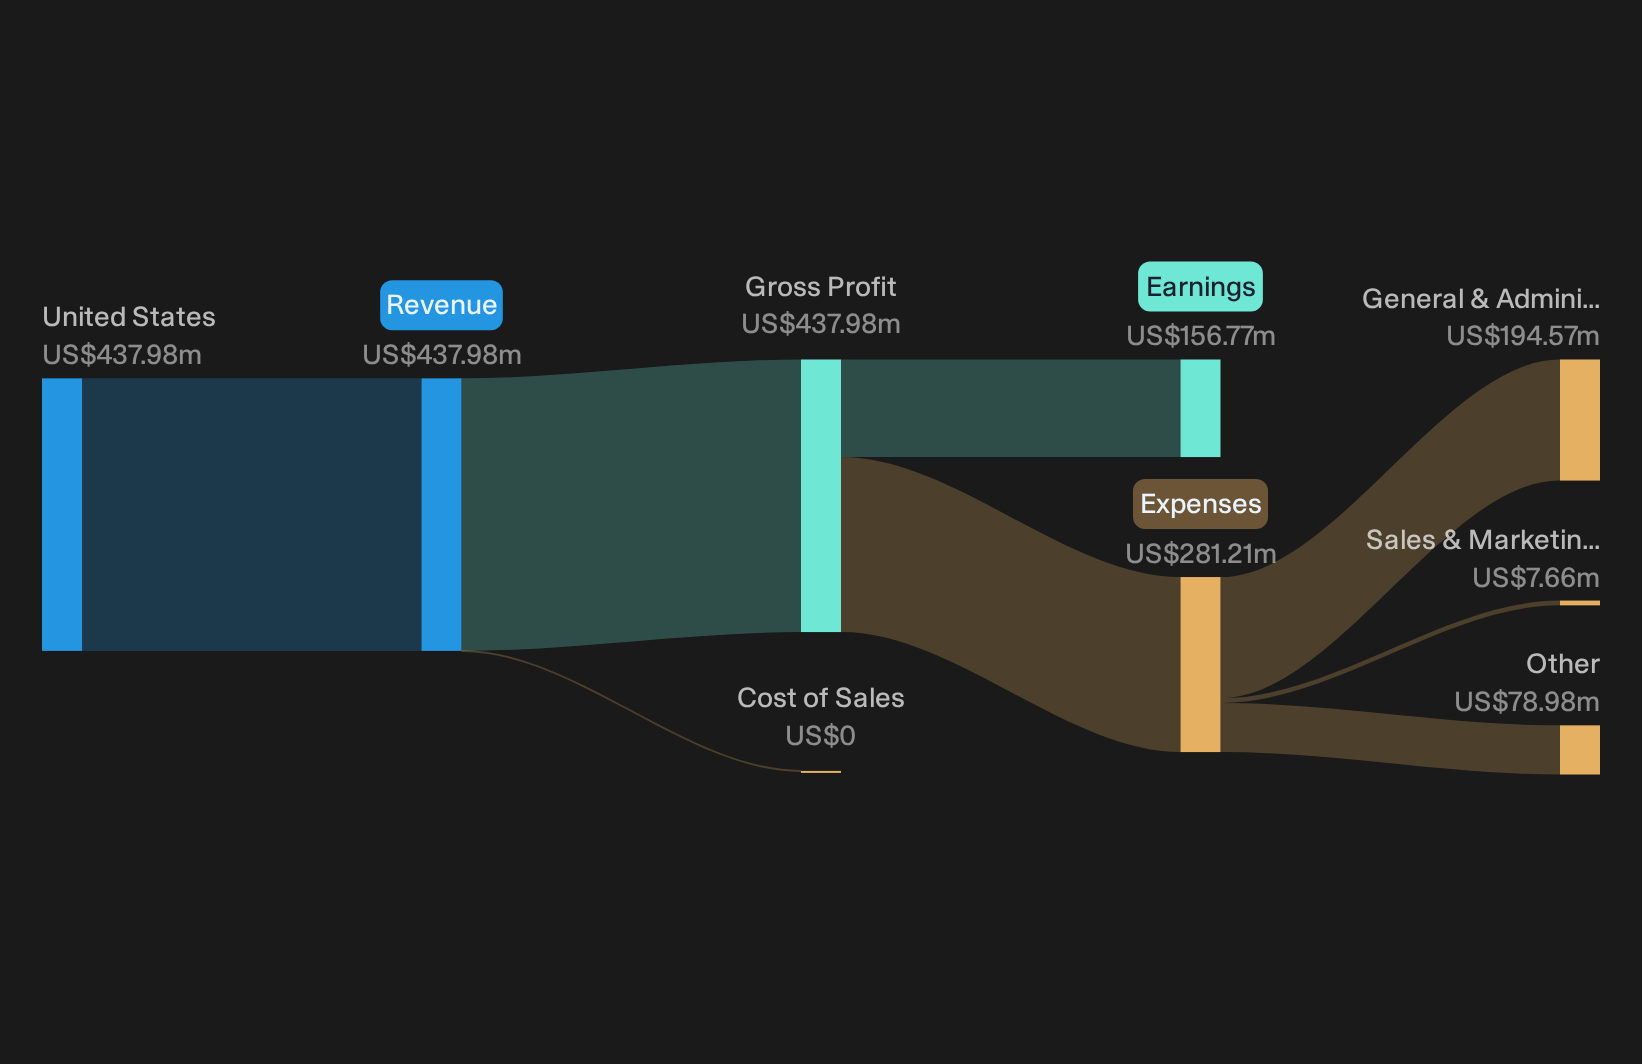
Stock Yards Bancorp results reinforce steady bull case
For investors leaning positive on Stock Yards Bancorp, this quarter largely backs that stance. Total revenue of US$119.3m versus US$99.5m and basic EPS of US$1.41 versus US$1.23 point to solid top line and earnings expansion. Net interest margin at 3.88% compared with 3.56% supports the idea that a traditional banking model can still earn healthy spreads. That mix, combined with the recent dividend increase and ongoing recognition in industry rankings, fits a story of a disciplined regional franchise that is executing on its playbook.
Bearish concerns tested by profitability and trends
More cautious investors worry about regional bank pressure, yet these figures soften some of that anxiety. Profit excluding extraordinary items rose from US$36.2m to US$43.5m while margin widened to 3.88%, which does not signal immediate earnings strain. The share price is still down roughly 7.5% over 90 days, so skepticism has not vanished. Even so, sector awards, dividend growth, and stable quarterly profitability suggest that near term operational risks to Stock Yards Bancorp look more contained than a purely bearish narrative would imply.
After a quarter that reassures on profitability but still leaves questions about regional bank exposure and concentration risk, it is worth asking whether the visible metrics around Stock Yards Bancorp capture the full picture or if there are early warning signs sitting just beneath the surface that could matter later for NasdaqGS:SYBT. Review the independent risk analysis for Stock Yards Bancorp which shows 1 important warning signHunt For Mispriced Earnings Power
Stock Yards Bancorp just showed how a steady banking model can still move a premium priced stock. The real opportunity could lie in stocks that could be undervalued before the market catches up.
- Company 1 - 50% below our estimate - focus on integrating a major aviation acquisition to scale engine, component and parts programs for recurring aftermarket work.
- Company 2 - 37% below our estimate - expand a large manufacturing build out that supplies premium protective films to dealerships and specialist installers.
- Company 3 - 32% below our estimate - sell high end processors and software that many data center customers now treat as the default for intensive AI workloads.
Those are three of them. See every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com