


EN
Earnings Guidance Raise Altering The Investment Case For Standard Chartered Stock?
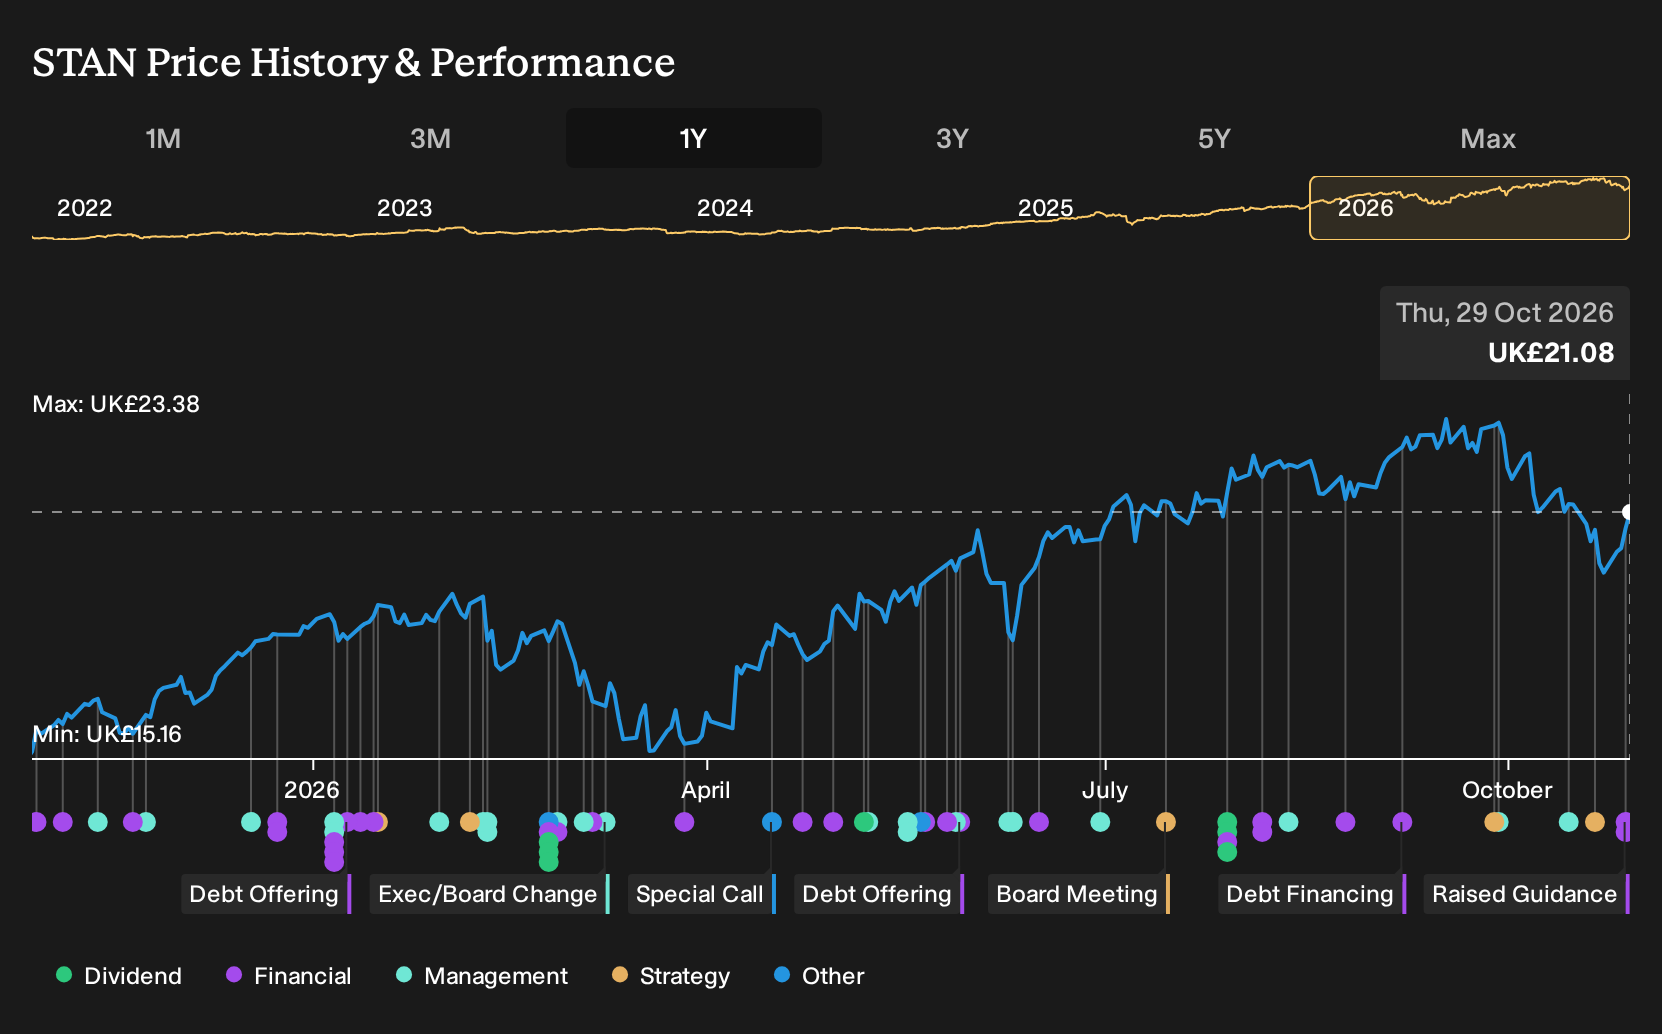
- Standard Chartered raised its 2026 guidance after a strong third quarter, now expecting full year total income growth above the prior 5% to 7% range and guiding net interest income growth of around 4% at constant currency excluding notable items.
- The bank paired this upgraded outlook with nine month 2026 results that showed higher net income and earnings per share, indicating that wealth management, trading activity and tighter execution are becoming more central to how the business earns returns.
- Attention now shifts to how Standard Chartered's raised 2026 income guidance reshapes the broader investment narrative that investors use to judge the bank.
Scan how Standard Chartered’s upgraded 2026 guidance compares with peers by reviewing a curated 10 high quality undervalued stocks that are already pairing resilient income with solid balance sheets.
What Is Standard Chartered's Investment Narrative?
To own Standard Chartered, you have to buy into a story of a globally diversified bank that can turn its footprint in Asia, Africa and the Middle East into consistent returns, not just one strong quarter. The raised 2026 income and net interest income guidance sits alongside nine month figures that show higher net income and earnings per share, which reinforces a narrative of better execution in fee driven areas like wealth management and trading rather than relying only on balance sheet growth.
In the short term, the upgraded outlook keeps attention on a few pressure points. The bank still runs a relatively low allowance for bad loans at 74%, faces an unstable dividend track record and carries a P/E above some peers, even if some models flag a discount to intrinsic value. The guidance upgrade helps the profitability side of the story, but it also raises the bar on cost control, technology delivery and credit discipline from here.
Yet alongside the higher 2026 ambition, there is a quieter issue that could matter much more if the cycle turns...
There's only one way to know the right time to buy, sell or hold Standard Chartered. Head to Simply Wall St's company report for the latest analysis of Standard Chartered's Fair Value.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Standard Chartered’s fee engines as the real swing factor. Before this guidance change, the bullish camp was already sketching out revenue rising about 9.6% a year and earnings reaching roughly US$7.9b by 2029. You can treat today’s upgraded outlook as fresh input and compare it with those more aggressive assumptions.
Explore 2 other Standard Chartered fair value estimates, including one that suggests as much as 62% upside from the current price!
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and making decisions that align with your objectives.
- A great starting point for your Standard Chartered research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Standard Chartered. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Standard Chartered's overall financial health at a glance.
Looking For More Investment Ideas Beyond Standard Chartered?
If you want to stress test your view on Standard Chartered against other opportunities, the Simply Wall St Screener can help you quickly surface stocks that fit different portfolio goals, from defensiveness to income to future growth potential.
- For investors who care most about quality at a fair entry point, review a curated set of 10 high quality undervalued stocks where fundamentals and pricing currently intersect in a potentially appealing way.
- If income reliability is a priority, scan a handpicked group of 5 dividend fortresses that combine higher yields with fundamentals you can scrutinize in one place.
- To keep risk in check while still staying invested, filter the market using a 5 resilient stocks with low risk scores that prioritises resilience based on Simply Wall St's risk scoring.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com