


EN
DPZ’s Dividend Yield Is a Tasty 2.5%, So Grab a Slice of Domino’s Stock Here
Things have been tough for restaurant stocks this year as consumers have cut back on discretionary spending amid a deteriorating macro environment. Restaurants across the board have said consumers are feeling pressure from high inflation and elevated gas prices.
On the third-quarter fiscal 2026 earnings call earlier this month, Domino’s Pizza (DPZ) CFO Sandeep Reddy echoed what fellow quick-service restaurants have been saying for the last few quarters: “Our business continued to be impacted by a challenging macro environment, which is pressuring consumers.” While the company saw an uptick in order count, average order value declined during the quarter. The company’s same-store sales — a key metric for restaurant companies — grew by just 0.3% in the U.S. and 0.2% internationally.
The good news, however, is that Domino's Pizza continues to take market share from rivals. Incidentally, two of its major pizza-chain rivals in the U.S. — namely Pizza Hut and Papa John's (PZZA) — are struggling. In June, Yum! Brands (YUM) sold Pizza Hut for a total consideration of $2.7 billion, while Papa John's — whose stock has fallen more than 50% this year — reportedly received an offer from Qatari royal family-backed Irth Capital Management in March 2026.
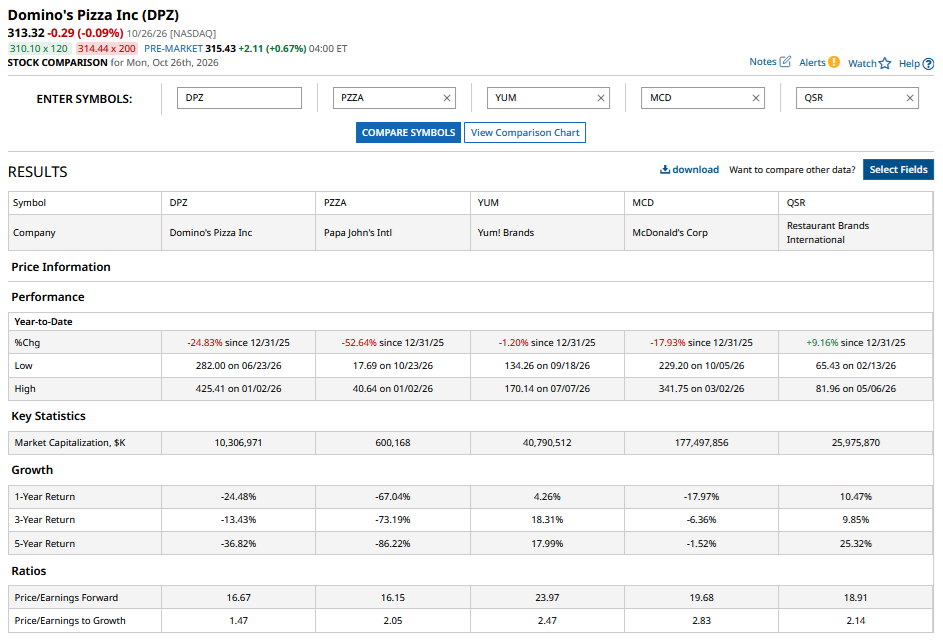
Domino’s Dividend Yield Rises Over 2.5%
DPZ stock has whipsawed this year and lost roughly a quarter of its market capitalization, pushing its dividend yield to more than 2.5%. Its dividend payouts have increased at an annualized rate of nearly 20% over the last 10 years, including a 15% increase this year. That’s pretty solid growth, and while earnings growth hasn’t kept pace in recent years, the payout ratio is comfortable at around 42%, especially considering the company’s capital needs.
In a previous article, I noted that while DPZ stock wasn't a compelling investment, shares could rise from those levels over the next year. With Domino's coming off those levels, let’s revisit the investment thesis.
The restaurant industry is currently facing a perfect storm. Demand has been tepid as many lower- and middle-income families have been cutting down on dining. Restaurants are also grappling with higher input costs as the prices of raw materials have risen this year.
Ideally, companies would have preferred to pass on the cost-push inflation to consumers through higher prices, but they have instead been racing to offer affordable options to lure more customers to order. This behavior is hurting franchise profitability. Last month, Meritage Hospitality Group (MHGUQ) — which is among the biggest franchisees for Wendy’s (WEN) in hte United states — filed for bankruptcy, blaming record-high beef prices and profitability issues.
Domino’s has also lowered its net new store addition plans in the U.S. to between 125 and 150, blaming “pressure on franchisee profitability.” The company did not provide a hard number for net store additions expected in 2027, but Reddy warned about “incremental pressure” until franchisee profitability improves. The company also lowered its 2026 same-store sales growth guidance and now expects it to rise toward the “low end” of the low single-digit growth it previously forecast.
Domino’s Stock Forecast
After Domino’s released its Q3 earnings, several brokerages slashed their price targets for DPZ stock. Among others, Mizuho, Wells Fargo, Citigroup, and Bank of America lowered their targets for shares of the company.
Overall, Domino's Pizza has a consensus “Moderate Buy” rating on Wall Street. Of 28 analysts covering the stock, 13 analysts have a “Strong Buy,” 14 have a “Hold” rating, and one analyst has a “Strong Sell.” The mean price target of $358.26 implies potential upside of 16% from current levels.
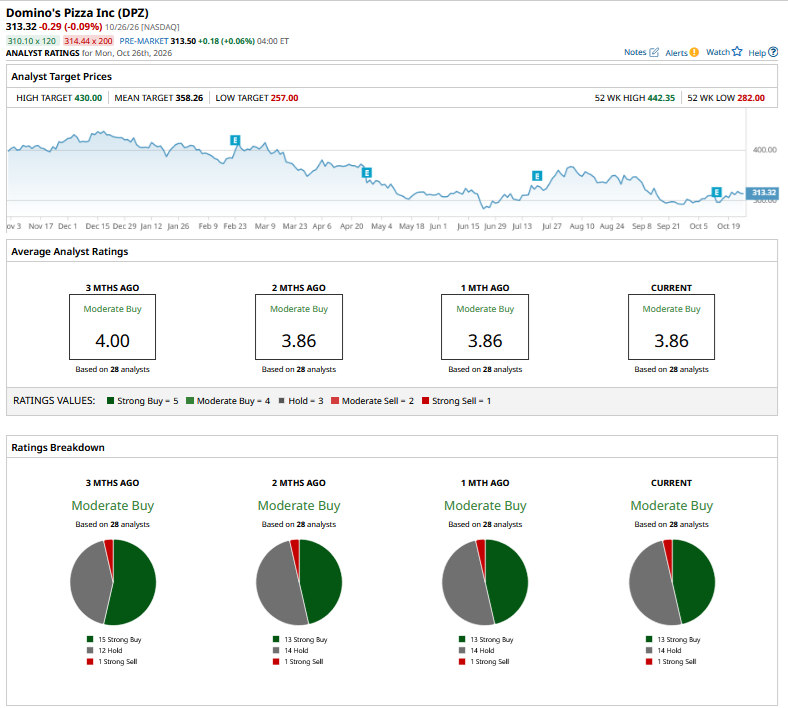
Should You Buy Domino’s Pizza Stock?
The restaurant industry might continue to see tepid growth unless we see gas prices come down significantly. However, Domino’s is positioning its business for long-term growth by gaining market share and expanding its total addressable market by launching new products. On Aug. 31, Domino's launched its namesake product — The Domino — which is a personal-sized Detroit-style pizza.
Domino’s risk-reward has improved since I last covered DPZ stock, as the forward price-to-earnings (P/E) multiple has corrected to 16.3 times. I believe the valuations are getting attractive here, although there could be volatility in the short term amid all the noise over the macro turmoil and affordability crisis.
On the date of publication, Mohit Oberoi did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.