


EN
NXP Semiconductors (NXPI) Stock Climbs As Q3 Earnings Showcase Record Margins
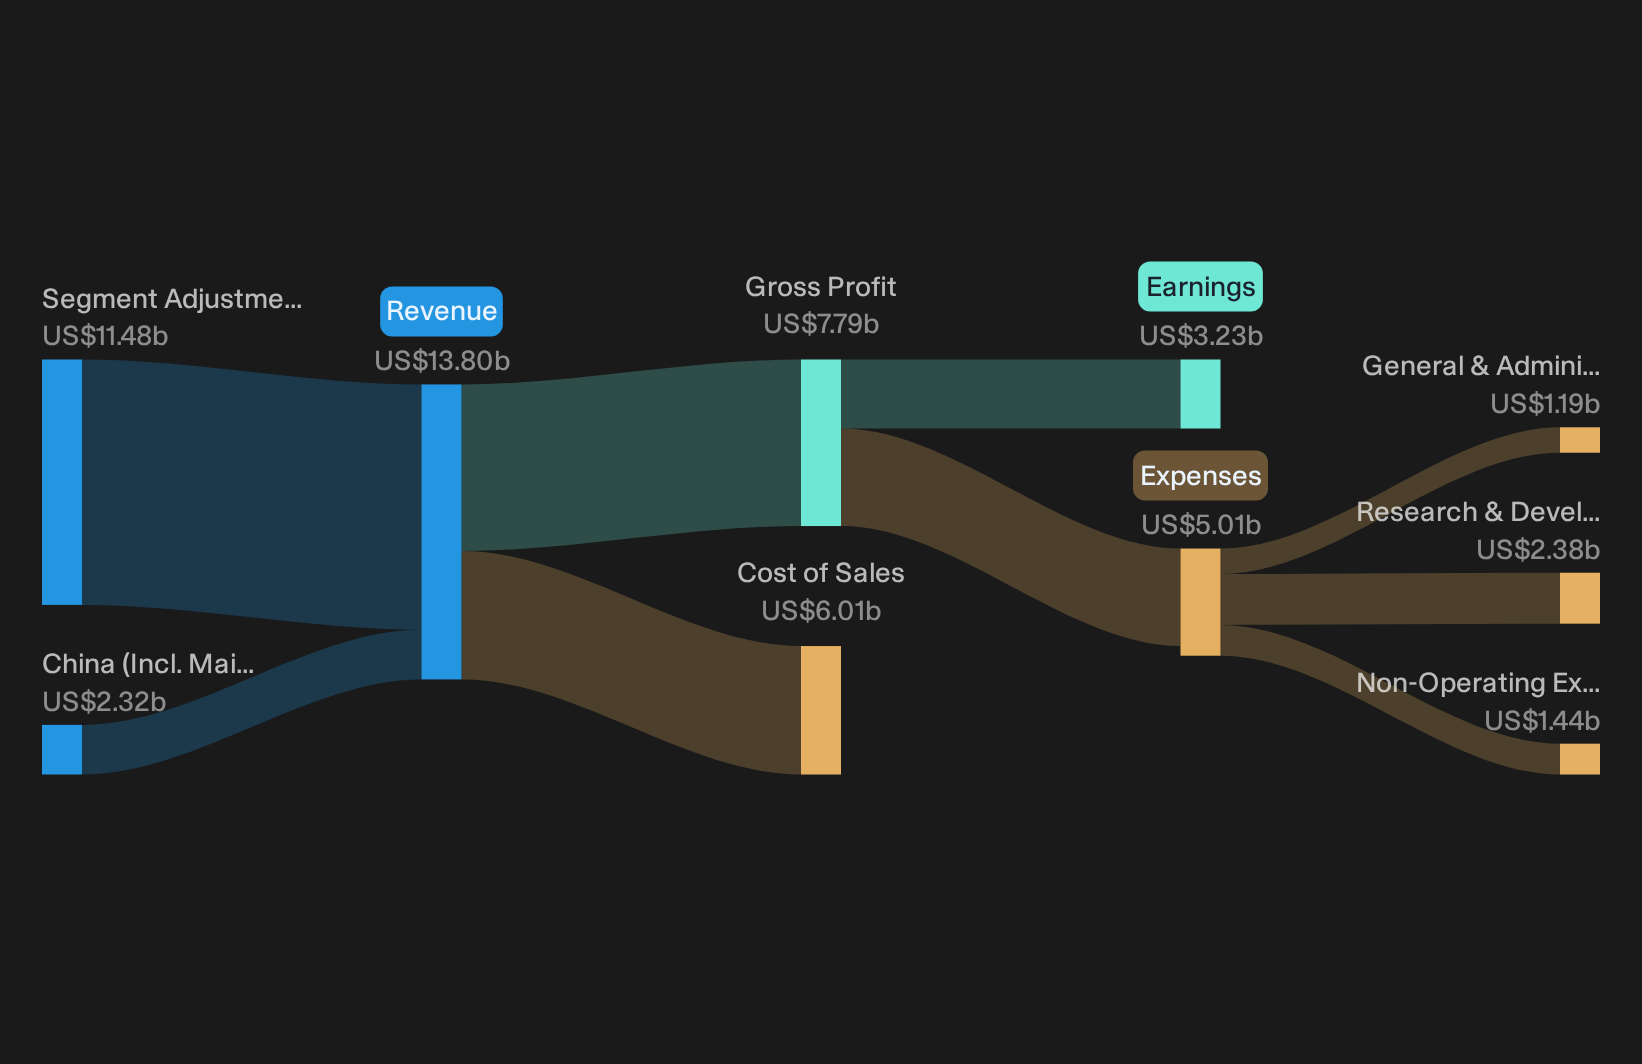
NXP Semiconductors just released its Q3 2026 numbers and the stock wasted no time reacting. The shares jumped 5.7% today to about US$266 after the release, on top of already strong recent gains. The headline that lit the fuse was clear: revenue reached US$3.79b and non GAAP earnings per share were US$4.20, both tied to record profitability.
The emotional rush comes from one place: margin power. Non GAAP operating margin landed at 37.1%, a level that can make even a hot semiconductor story feel under owned. Whether this one day surge fully reflects the underlying earnings quality is the real question for investors now.
Love NXP Semiconductors’ record margins but want a wider set of high quality balance sheets backing strong earnings power? Stack today’s results against our list of solid balance sheet and fundamentals stocks (22 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$3,786m vs. US$3,173m (up about 19%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$884m vs. US$631m (up about 40%)
- Basic EPS (Q3 2026 vs Q3 2025): US$3.51 vs. US$2.50 (up about 40%)
- Non GAAP Operating Margin (Q3 2026 vs Q3 2025): 37.1% vs. about 33.8% (an improvement of roughly 330 basis points)
NXP just logged record auto revenue and a soaring SDV run‑rate. Ask Charlie what NXP’s $2B SDV bet really means.
NXP Semiconductors: Bullish AI And Factory Mix Claims On Trial
The upbeat story around NXP Semiconductors hinges on two big promises: richer AI and software content, and a lighter factory footprint that lifts margins.
"A key factor is that NXP Semiconductors continues to convert its software-defined vehicle, physical AI and data center pipelines into sustained revenue growth while executing on the shift to a more asset light manufacturing model."
Q3 gives real milestones. Automotive revenue passed US$2b, with software defined vehicle sales already at a more than US$1.5b run rate, and data center control roles now tracking above the earlier US$500m 2026 goal. Non GAAP operating margin at 37.1%, plus Q4 guidance near that level, shows the asset lighter mix is flowing through, not just aspirational.
One Narrative disagrees with today's price. → See where this Narrative says NXP Semiconductors should trade.
NXP Semiconductors: Bear Fears Meet Mixed Evidence
Critics worry that NXP Semiconductors is over building for an auto cycle that could roll over. The concern is clear.
"a sharp automotive inventory correction in China could leave this pipeline underutilised and lead to lower than expected automotive revenue and weaker operating margins."
Q3 shows Automotive revenue above US$2b and non GAAP operating margin at 37.1%, which does not yet reflect that stress case. At the same time, Q4 guidance that is broadly in line rather than accelerating, together with Mobile softness, means there is no firm evidence that future Chinese auto demand can fully absorb upcoming 300mm and backend capacity.
Hunt Quiet Disconnects In Quality
NXP Semiconductors showed how quickly sentiment shifted when margins surprised in recent results. The real opportunity could sit in companies where fundamentals appear to change before valuations reflect those shifts.
- Company 1 - 21% below our estimate - use surgical robots, higher acuity procedures and capital equipment upgrades to deepen procedure penetration.
- Company 2 - 44% below our estimate - convert a near record backlog of large civil projects into cash while managing legacy legal disputes.
- Company 3 - 32% below our estimate - supply AI infrastructure and superclusters that support demanding workloads after securing a role in generative AI.
Three companies from the same screener. Open the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com