


EN
MYR Group (MYRG) Stock Shrugs Off Record Q3 Earnings As Timing Questions Linger
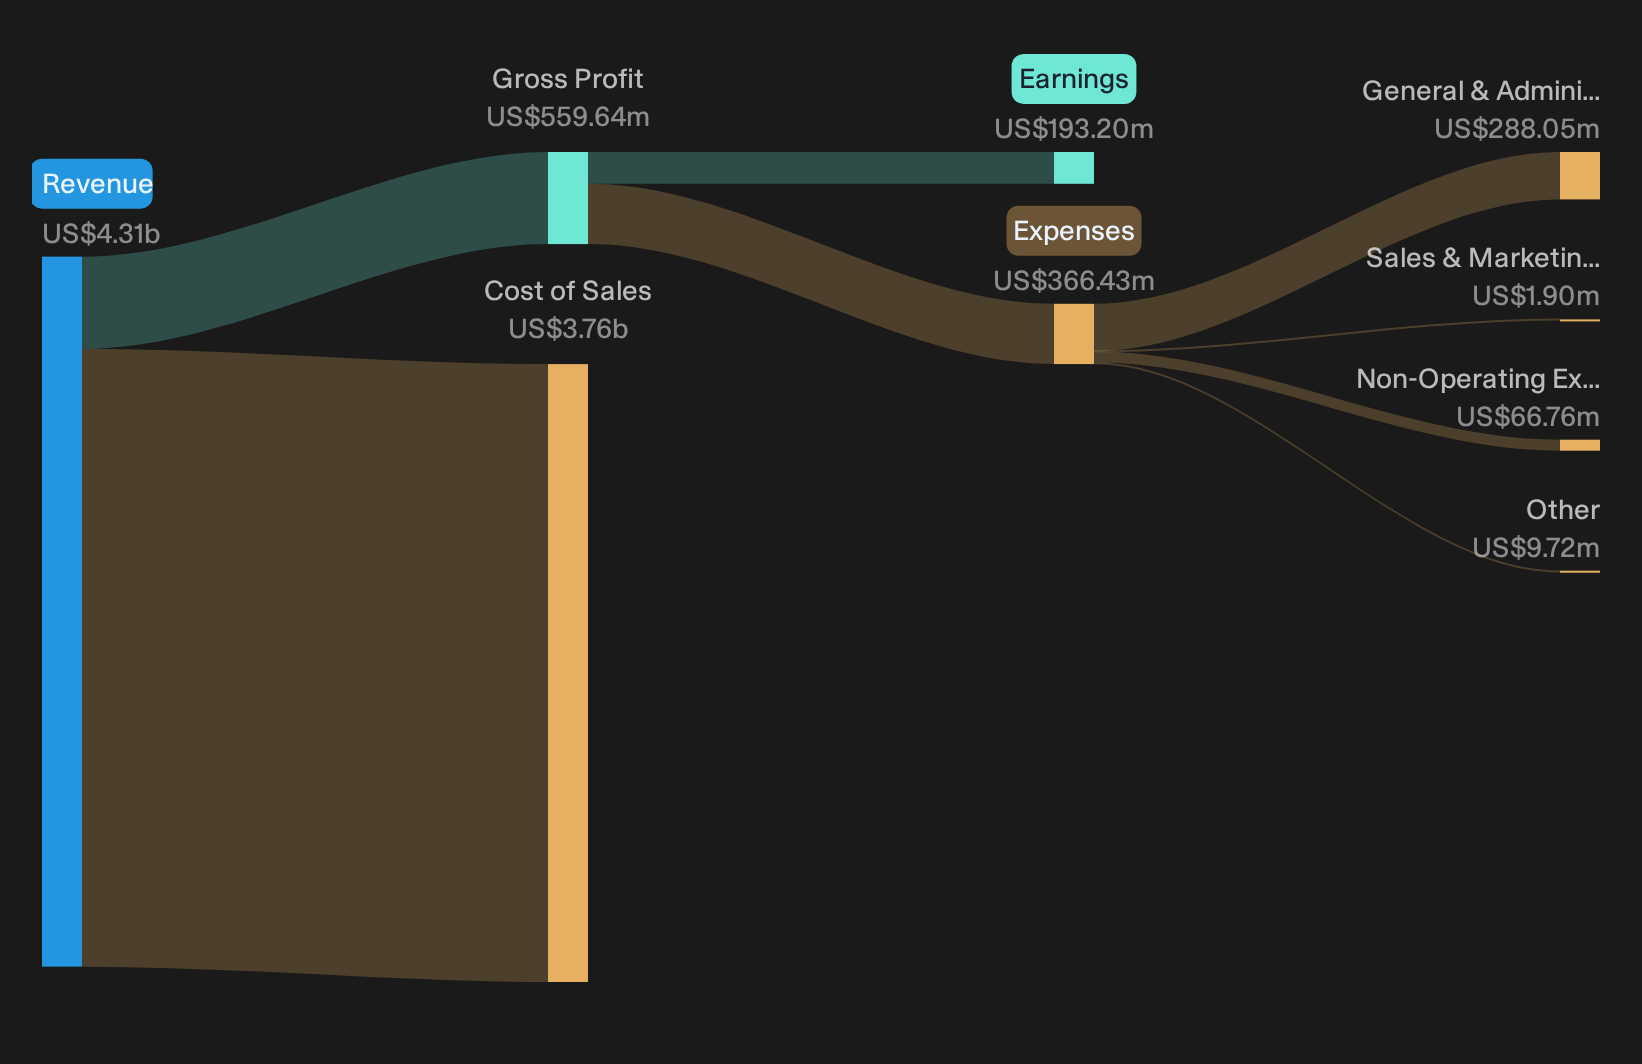
MYR Group came into this Q3 2026 print with a mixed tape. The stock was down about 15% over the past three months, yet it bounced 1.1% today to US$283 after the release. For a contractor often treated as a steady grid and commercial electrification play, the headline was anything but dull. Quarterly revenue reached US$1.26b and net income hit US$60.0m, both records that point to earnings power outpacing the modest share price move.
Impressed that MYR Group reported record revenue and profit while the share price has lagged over the past few months? Explore our screener of grid and infrastructure contractors with solid balance sheets and consistent fundamentals through the list of solid balance sheet and fundamentals stocks (22 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$1,259.0m vs. US$950.4m (up 32%)
- Net Income (Q3 2026 vs Q3 2025): US$60.0m vs. US$32.1m (up 87%)
- Basic EPS (Q3 2026 vs Q3 2025): US$3.85 vs. US$2.07 (up 86%)
- Backlog (Q3 2026 vs Q3 2025): US$3.68b vs. approximately US$2.67b (up 38%)
Earnings grab the headline, but investors who care about what a stock might be worth usually focus on the cash that actually comes in and out of the business. When you line up MYR Group's cash flows against the current share price, the stock could be a striking 44% undervalued.
Evaluating MYR Group’s Grid And Data Center Ambition
The bullish view depends on MYR Group converting structural power and data demand into durable earnings power.
"Industry focus on grid modernization to handle growing electrification and digital demand, highlighted by new MSAs and high voltage line awards, positions the T&D segment to pursue larger, higher complexity projects that can support operating margin targets of 8% to 11%."
Q3 results show this thesis clearing early hurdles. T&D operating margin landed at 9.3%, within that 8% to 11% goal, while a record US$3.68b backlog and 38% growth in total orders indicate utilities and C&I customers are awarding the larger, complex work this story depends on.
The price and this Narrative do not agree. → Uncover what this Narrative says MYR Group is actually worth.
MYR Group: Strong Quarter, But Timing Risk Persists
The cautious view argues MYR Group’s record backlog still does not solve near term timing risk on very large projects.
"Electrification and data demand are pushing utilities and large customers to plan very large, long dated grid and data center programs. However, the company itself notes that many of the largest transmission projects would not start construction or generate revenue until at least 2027, which could leave current revenue and earnings growth exposed if investors expect faster conversion of these plans into billable work."
Q3 shows healthy T&D activity, a 38% larger backlog and raised growth expectations into FY27. Yet management still ties the main high voltage build to 2028, so the core schedule overhang remains unresolved despite strong current execution.
Hunt For Quiet Disconnects
MYR Group just paired record earnings with a share price that has not fully tracked the recent momentum. The real opportunity sits with stocks that could be undervalued before the gap closes.
- Company 1 - 36% below our estimate - uses new high horsepower capacity and engine platforms to chase long term data center power contracts.
- Company 2 - 15% below our estimate - leans on a swelling, data center heavy backlog and strong cash generation while juggling concentration and working capital strain.
- Company 3 - 43% below our estimate - expands payment rails for large merchants across emerging markets as higher margin products and automation reshape unit economics.
That is three of the list. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com