


EN
Darling Ingredients (DAR) Stock Ignores Q3 Earnings Quality Shift
Darling Ingredients just dropped Q3 2026 numbers and the share price barely flinched, slipping about 0.6% on the day. That muted move sits awkwardly against a quarter that delivered about US$1.7 of earnings per share and US$1.79b of revenue, plus strong cash coming out of the Diamond Green Diesel partnership.
The real action is not in the chart. It is in the earnings quality. Traders are treating this like another forgettable quarter while the business is quietly leaning on a sharply improved net margin story and a P/E tag that is cheaper than most peers.
Love the cleaner earnings story at Darling Ingredients but unsure if this P/E discount is really a bargain or a trap? Line it up against a 30 high quality undervalued stocks to see how it stacks up on quality, cash generation, and valuation together.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$1,791.1m vs. US$1,564.0m (up about 14.5%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$267.0m vs. US$19.4m (very large increase, more than 10x)
- Basic EPS (Q3 2026 vs Q3 2025): US$1.70 vs. US$0.12 (very large increase, more than 10x)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 12.5% vs. 1.8% (margin level reported as much stronger year on year)
Tired of scrolling through walls of earnings commentary and raw figures on Darling Ingredients? Get the full visual story on margins, valuation, and the rest of the financial picture in an easy dashboard style view with our company report for Darling Ingredients.
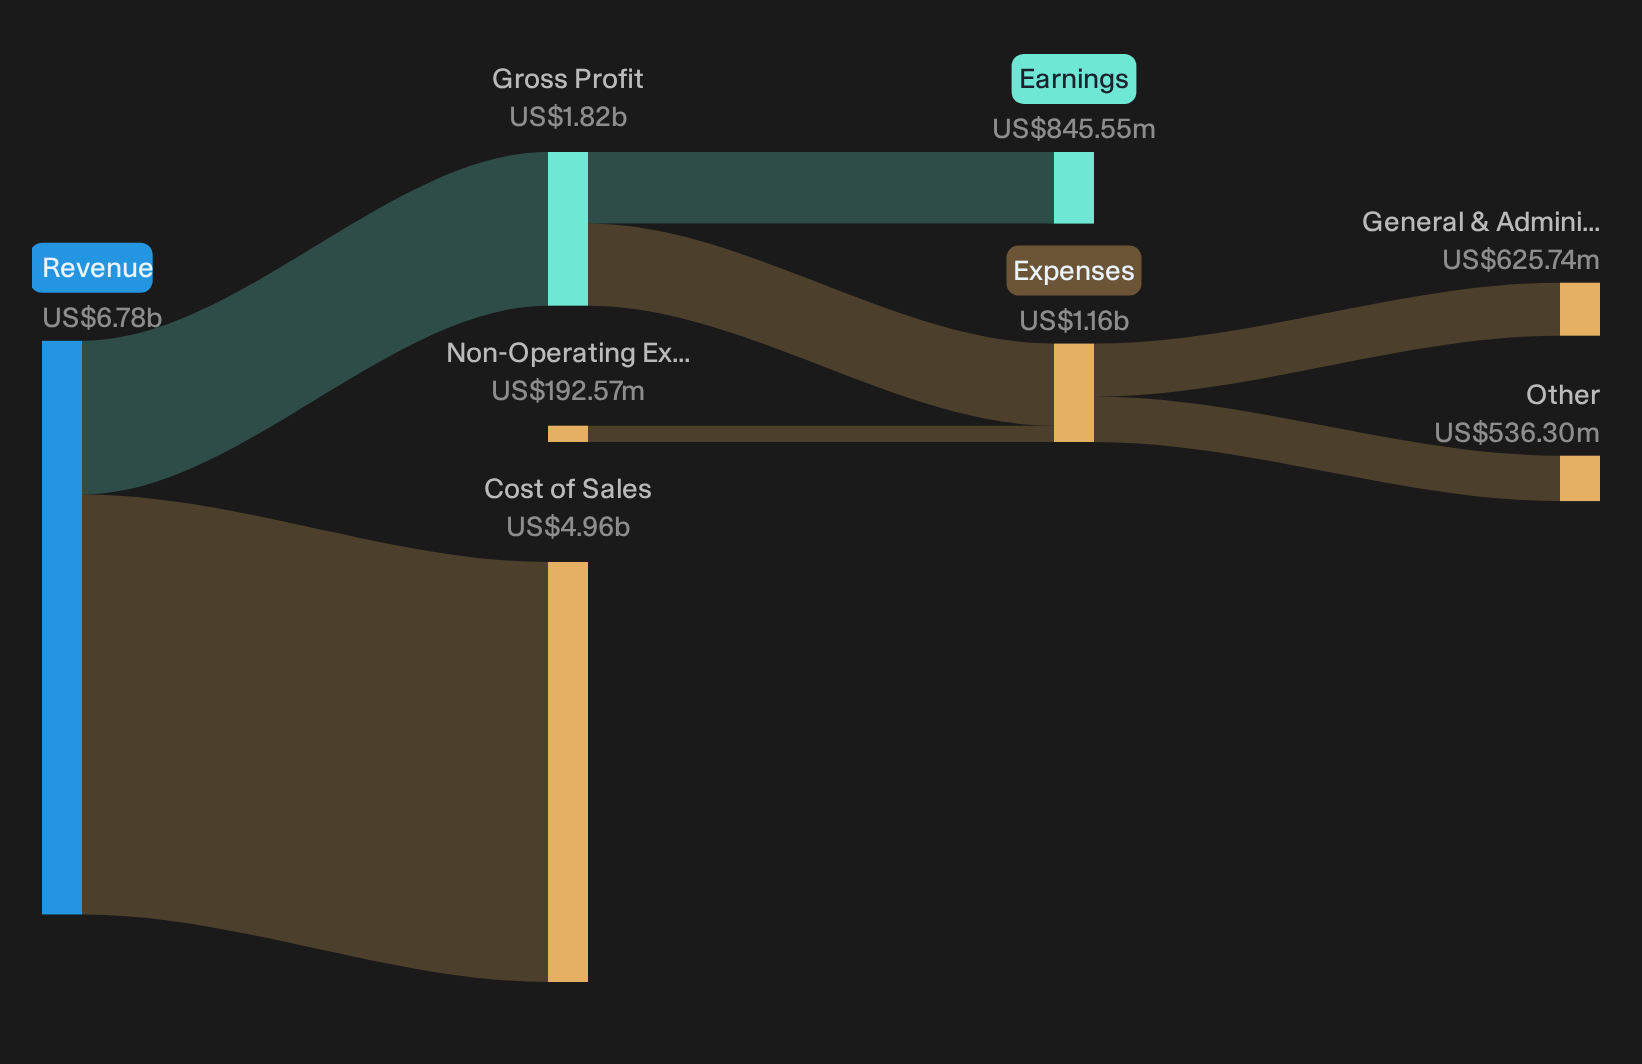
Evaluating Darling Ingredients’ Cash And Margin Milestones
Supporters argue that Darling Ingredients is shifting from policy hope to hard cash and better economics in its core operations.
"The margin and cash optimization plan in the Feed business, illustrated by Q1 2026 gross margins of 25.3% of sales versus 20.3% a year earlier and Core Ingredients EBITDA of US$353m in Q2 2026, points to a structural repricing and mix shift that can continue to re-rate segment profitability and support higher consolidated net margins even without large volume growth."
Q3 results back up that ambition. Trailing net margin at 12.5% versus 1.8% a year earlier, together with reaffirmed US$2.2b to US$2.3b combined adjusted EBITDA and leverage at roughly 1.7x, all signal real progress on that optimization plan, not just talk.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Darling Ingredients: Cash Progress, Policy Overhang
Bears argue Darling Ingredients is still overly dependent on policy supported renewable diesel economics rather than repeatable industrial muscle.
"Although Darling Ingredients is benefiting from strong current renewable diesel margins and tight diesel supply, reliance on policy supported pricing and elevated waste fat values leaves earnings exposed if regulatory support weakens or fuel markets loosen, which could compress margins and pressure EBITDA and net income."
Q3 results do not settle that concern. DGD cash distributions of about US$171m and combined adjusted EBITDA of roughly US$514m underline how central renewable diesel remains. Net debt dropping around US$420m and leverage at roughly 1.7x show balance sheet milestones hit, yet they still hinge heavily on that same policy sensitive cash engine.
Hunt Quiet Disconnects In Plain Sight
Darling Ingredients just reported a detailed quarter that left the share price almost unchanged. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 31% below our estimate - converts long term optical and solar supply agreements and customer prepayments into higher margin infrastructure-linked product shipments.
- Company 2 - 44% below our estimate - turns a near record construction backlog and nine large projects into cash while working through expensive legacy legal disputes.
- Company 3 - 50% below our estimate - builds a focused aviation aftermarket platform by integrating a recent acquisition and expanding higher margin engine repair partnerships.
Three companies from the same screener. Open the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com