


EN
Murata Manufacturing (TSE:6981) Starts SWL Connector Production, Is The Valuation Too Rich?
Murata Manufacturing (TSE:6981) has just moved its SWL series RF and microwave coaxial connectors with a switch into mass production, spotlighting how this component maker tackles tight PCB space in compact wireless hardware.
Against that product backdrop, Murata Manufacturing’s share price has been volatile, with a 7.12% 7 day share price return following a 2.82% gain in the last session. However, the 30 day share price return is down 14.82% and the 90 day share price return is down 7.09%, while the year to date share price return of 106.91% and 1 year total shareholder return of 130.47% signal strong longer term momentum that long term holders will likely weigh against shorter term swings.
Spot similar miniaturization leaders to Murata Manufacturing in our hand-picked list of 71 high quality undiscovered gems that are quietly building the next wave of compact, high-performance electronics.
Murata Manufacturing looks like a powerful franchise in miniaturized components, and the share price has already raced ahead. The key tension now is simple: does the current valuation still leave enough on the table for new buyers?
Preferred P/E of 47.2x: Is it justified for Murata Manufacturing?
Murata Manufacturing trades on a rich P/E of 47.2x, and that sits alongside a last close of ¥6,890 that many investors will compare to both peers and fair value estimates before making any moves.
The P/E ratio links what the market is willing to pay today with the company’s earnings per share. A higher figure usually signals that shareholders are pricing in stronger profit expansion or more resilient earnings power. For a large electronics components supplier like Murata Manufacturing, that matters because much of the value story rests on how consistently it can convert demand for miniaturized parts into bottom line results.
Here, the multiple is doing a lot of heavy lifting. Earnings are described as having declined by 7.9% per year over the past 5 years, even though the most recent year recorded 22.3% growth and an improvement in net profit margins from 12.5% to 13.8%. The market appears to be putting a premium on that recent acceleration and on forecasts that profits could grow 25.7% per year, which is described as significantly ahead of both the JP market and Murata Manufacturing’s own longer term trend.
Against the rest of the JP Electronic industry, which trades at an average P/E of 15.6x, Murata Manufacturing’s 47.2x is substantially higher. The ratio also sits above the estimated fair P/E of 38.6x, implying that if sentiment cooled, the valuation could shift closer to that fair level according to the model. At the same time, it is described as broadly in line with a 49.4x peer average, which suggests investors are currently pricing Murata Manufacturing similarly to other high expectation electronics stocks rather than giving it an unusually extreme premium.
Explore the SWS fair ratio for Murata Manufacturing.
Result: Price-to-earnings of 47.2x (OVERVALUED).
Still, Murata Manufacturing faces pressure if demand for compact electronics softens or if competitors compress margins on key components such as RF modules and sensors.
Find out about the key risks to this Murata Manufacturing narrative.
Another view on Murata Manufacturing’s value
The P/E of 47.2x paints Murata Manufacturing as expensive, yet the SWS DCF model points in the opposite direction. With an estimated future cash flow value of ¥11,890.42 per share against a market price of ¥6,890, that framework frames the stock as undervalued on cash generation potential.
The gap between these two signals matters. A rich earnings multiple can leave less room for error if forecasts slip, while a DCF that sits much higher than today’s quote suggests the market could be under-rating the long run cash profile. Which lens do you put more weight on when the story does not fully line up?
Look into how the SWS DCF model arrives at its fair value.
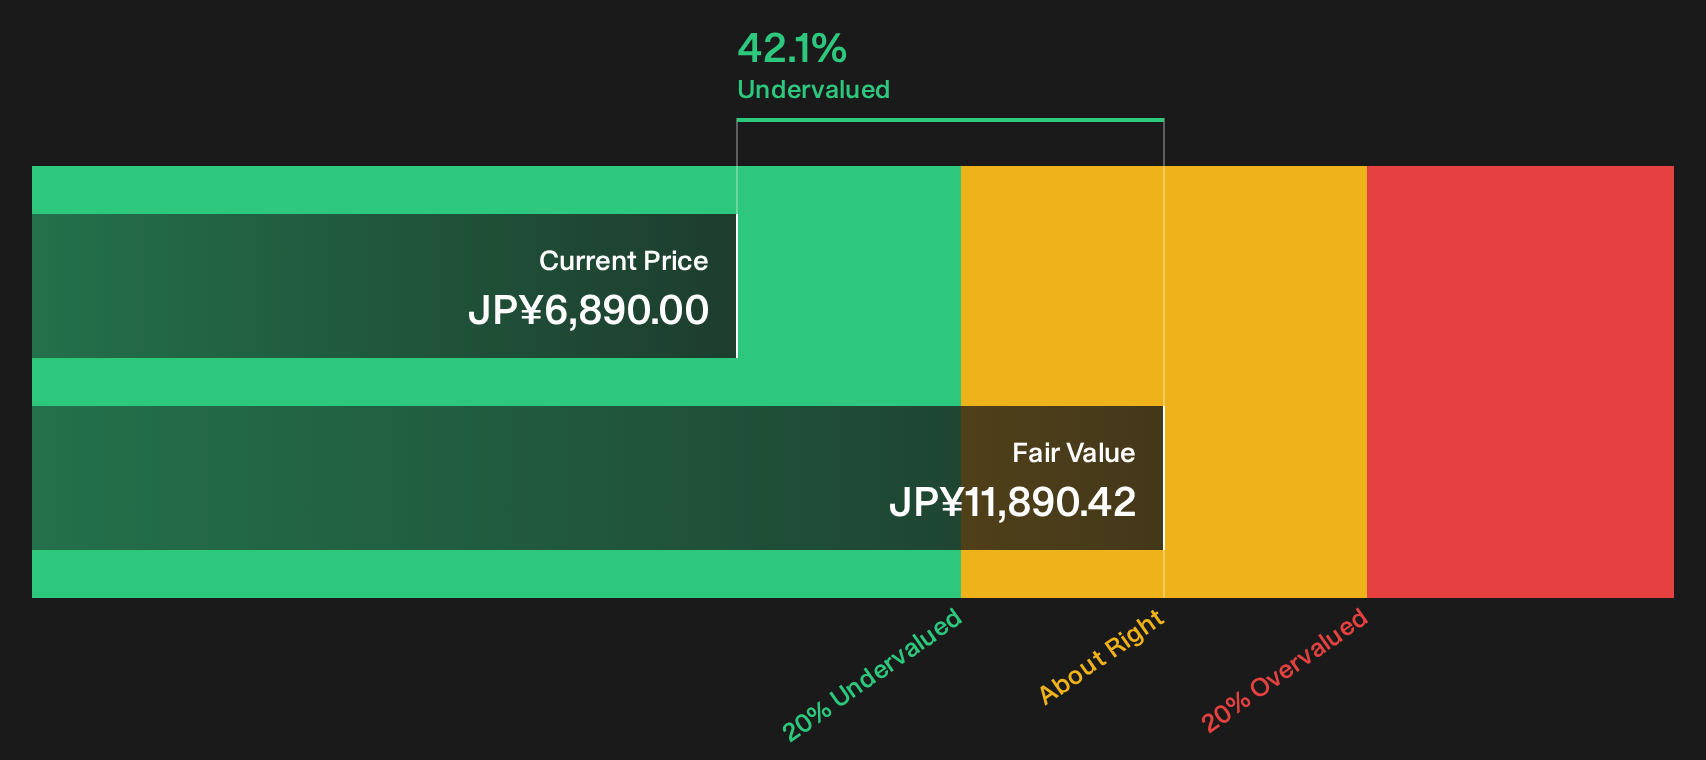
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Murata Manufacturing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Murata Manufacturing now presents a mixed picture of optimism and caution, so treat this as your cue to move fast, review the numbers yourself, and weigh both the upside and the downside by digging into the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Murata Manufacturing?
If Murata Manufacturing has caught your attention, now is the time to widen your net and line up a few more quality candidates on your watchlist.
- Target steadier potential by scanning for companies with robust finances using our list of solid balance sheet and fundamentals (23 results).
- Hunt for potential value by reviewing a curated 15 high quality undervalued stocks that pairs stronger balance sheets with appealing price tags.
- Lock in potential income streams by checking out resilient payers in our 30 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com