


EN
Why Concentra Group Holdings Parent (CON) Is Getting Attention Today
Concentra Group Holdings Parent (CON) just added a new medical center in Arlington, Virginia, extending its Washington, D.C.-area footprint and targeting employers with complex workforce health needs across the broader DMV corridor.
For investors watching the tape, the Arlington opening lands during a strong run for Concentra Group Holdings Parent. The latest share price of US$40.59 comes after a 30 day share price return of 14.79% and a year to date share price return of 109.12%, with the 1 year total shareholder return at 103.88%. This points to momentum that has been building rather than fading, as expansion news and upgraded full year earnings estimates feed into sentiment.
Scan how Concentra Group Holdings Parent compares with other healthcare operators that are showing strong momentum in workforce services using our curated list of list of solid balance sheet and fundamentals (24 results)
For Concentra Group Holdings Parent, the recent surge and Arlington expansion both sit in view. Is the current valuation mostly reflecting the business on the ground, or a mood shift in the market tape?
Most Popular Narrative: 3% Undervalued
Concentra Group Holdings Parent is priced at $40.59 against a widely followed fair value of about $41.67. This frames the Arlington move against a modest valuation gap built on longer term earnings and margin expectations.
Employers are intensifying their focus on workforce health compliance and cost control, creating fertile ground for growth in workplace injury prevention, drug testing, and onsite wellness programs. Concentra's recent scale expansion through acquisitions and enhanced primary care offerings positions the company to capture a greater share of this expanding market, supporting long-term revenue and margin growth.
See why 3 investors see Concentra Group Holdings Parent as 3% undervalued.
Result: Fair Value of $41.67 (UNDERVALUED)
Still, the story can change quickly if organic visit growth stays muted or if higher leverage and acquisition costs continue to pressure Concentra Group Holdings Parent's profitability.
Find out about the key risks to this Concentra Group Holdings Parent narrative.
Another View on Concentra Group Holdings Parent
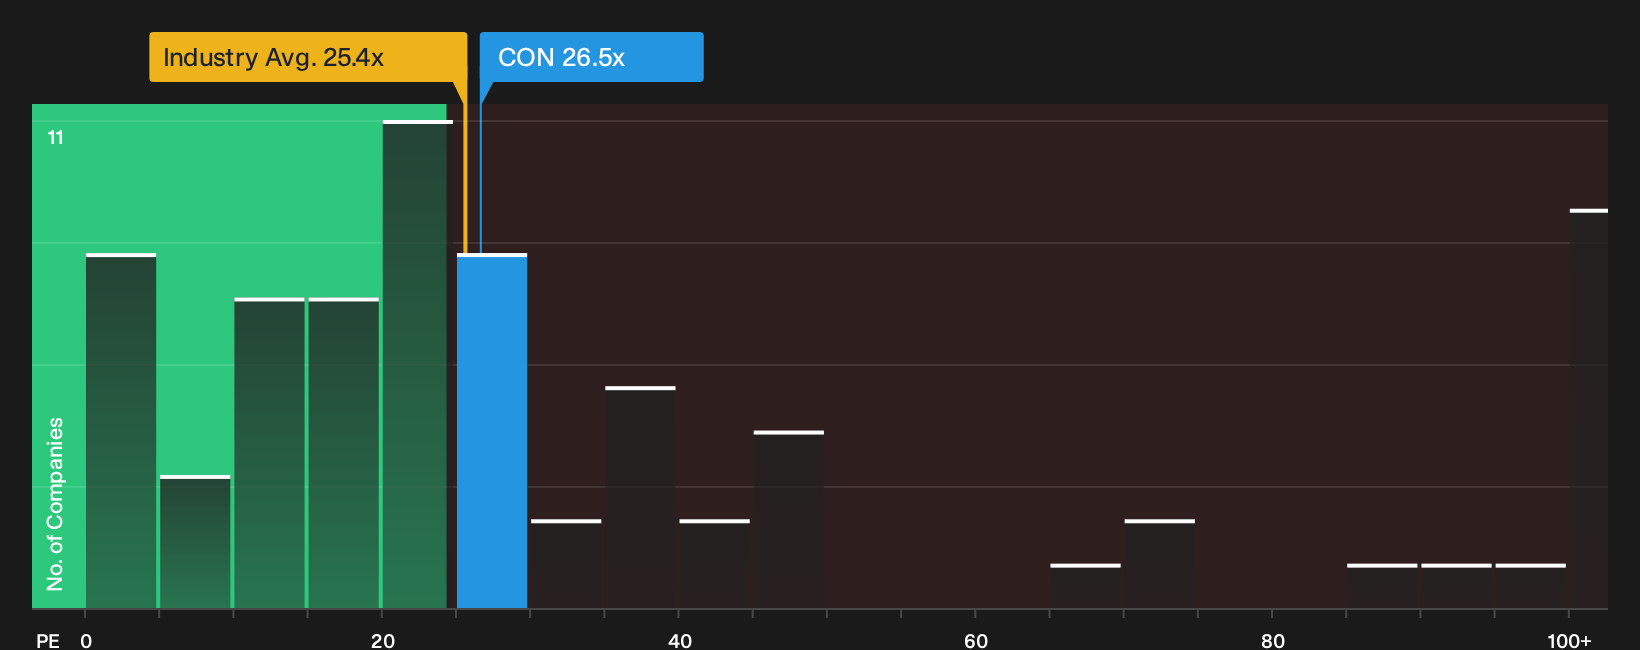
On simple earnings multiples, Concentra Group Holdings Parent looks anything but cheap. The stock trades at a P/E of 26.5x, compared with 21.8x for peers and 24.8x for the broader US Healthcare group, while the fair ratio sits lower again at 23.3x. That premium can reflect quality, or it can compress quickly if expectations cool.
For investors weighing whether this richer multiple still leaves room for upside, the valuation breakdown is worth a closer look, especially if the market starts drifting toward that lower fair ratio over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Concentra Group Holdings Parent so far, or a clear message forming in the numbers? Act while sentiment is still shifting and review the data yourself, starting with the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Concentra Group Holdings Parent?
Do not stop with one ticker when the broader market offers a wide field of opportunities that could fit your goals more closely.
- Target higher potential upside by scanning a curated pool of companies that combine quality fundamentals with attractive entry prices through our 26 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses with robust yields and resilient payouts using the 6 dividend fortresses.
- Prioritize resilience and capital preservation by filtering for companies with lower overall risk profiles through the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com