


EN
Yamazaki Baking (TSE:2212) Stock Drifts As Q3 Results Meet Profit Doubts
Yamazaki Baking just posted its Q3 2026 scorecard and the market shrugged. The stock closed at ¥3,767, roughly flat over the past week, even though trailing twelve month earnings per share are ¥218.29 and net profit margin sits at 3.2%.
The real story is sentiment. Short term traders seem focused on the softer quarterly profit print. However, the trailing earnings base and improved margin profile tell a calmer story than the 7 day share price dip of about 2.8% suggests.
We appreciate the steady earnings base at Yamazaki Baking but remain cautious about short term profit volatility and the flat share price reaction. Compare this setup against our list of solid balance sheet and fundamentals stocks (23 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): ¥334,863 million vs. ¥317,467 million (up about 5.5%)
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): ¥7,675 million vs. ¥6,742 million (up about 13.8%)
- Basic EPS (Q3 2026 vs Q3 2025): ¥38.97 per share vs. ¥34.12 per share (up about 14.2%)
- Trailing 12 Month Net Profit Margin (to Q3 2026 vs prior year): 3.2% vs. 3.0% (modest margin improvement on a trailing basis)
Earnings tell you what just happened, but investors who care about valuation usually pay closer attention to the cash moving through the business over time. When you look at Yamazaki Baking's cash flows on their own, the stock could be a striking 40% undervalued.
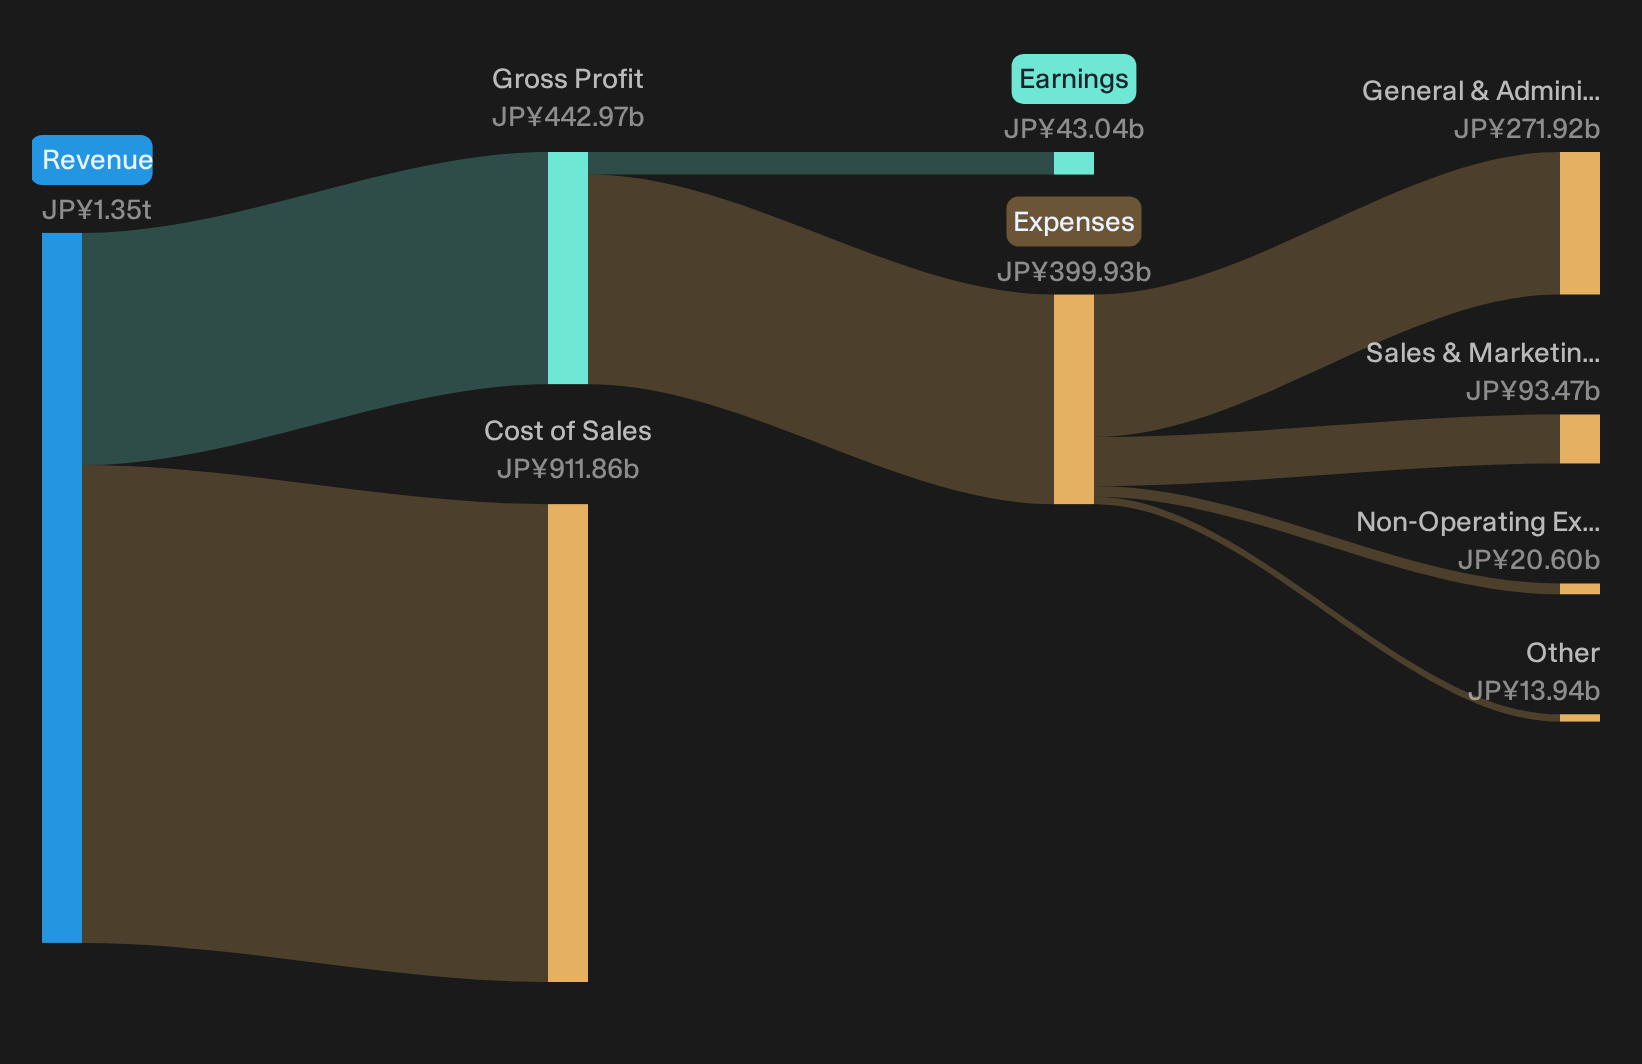
Yamazaki Baking’s results backing the steady story
For a consumer staple like Yamazaki Baking, the latest figures lean gently toward the positive side of that “steady and defensive” label. Revenue in Q3 2026 is higher than Q3 2025 and basic EPS also moves the right way, which fits a narrative of a broad, everyday food portfolio that still pulls its weight. A trailing net margin of 3.2%, slightly above the prior year, lines up with the idea that vertical integration and scale are not obviously eroding profitability right now.
Short term softness keeps bears in the conversation
The cautious story has some backing too. Management delivered only a modest improvement in trailing margin, and the latest quarter produced softer profit than short term traders hoped, which showed up in the recent 7 day share price decline. That hesitation chimes with concerns about cost pressure and complexity in a wide ranging group. Q3 progress on income and EPS helps keep immediate risk in check, yet the reaction in the stock signals that execution questions have not gone away.
With earnings growth slowing from the five year pace and the P/E sitting slightly above the food sector average, it is worth stress testing Yamazaki Baking’s balance sheet strength. Check the full liquidity, leverage and dividend coverage detail in the financial health analysis of Yamazaki Baking stock.Hunt Mispriced Stories Behind The Numbers
Yamazaki Baking shows how a steady earnings base can still leave the share price treading water. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 30% below our estimate - supplies critical photomasks that chip designers adopt when upgrading to more complex packaging and 3D structures.
- Company 2 - 21% below our estimate - sells data platforms firms turn to once scattered reports and manual form workflows start slowing commercial decisions.
- Company 3 - 32% below our estimate - runs payment rails merchants plug into when adding new wallets, pay-later options and instant payout features.
Three companies from the same screener. Open all 15 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com