


EN
Will Upper End Revenue Guidance Change Telix Pharmaceuticals Stock Narrative
- Telix Pharmaceuticals reaffirmed its FY2026 revenue and other income outlook at over US$1b, with guidance tracking near the upper end of its US$950 million to US$970 million range, and reported unaudited Q3 2026 group revenue of US$245 million compared with US$206 million in the prior corresponding quarter.
- The combination of tighter guidance around a US$1b plus revenue year and solid quarterly top line data provides investors with more concrete evidence on Telix Pharmaceuticals' commercial execution and product demand across its radiopharmaceutical portfolio.
- This article will examine how Telix Pharmaceuticals' reaffirmed US$1b plus revenue outlook may reshape the investment narrative around its theranostics platform.
Scan beyond Telix Pharmaceuticals and identify other cancer and healthcare specialists by screening for 7 healthcare AI stocks that could be building similar momentum stories.
Telix Pharmaceuticals Investment Narrative Recap
To own Telix Pharmaceuticals, you need to believe this radiopharma platform can keep scaling its imaging agents while gradually converting a broad oncology pipeline into commercial therapies. The reaffirmed FY2026 outlook at more than US$1b in revenue and other income, together with US$245 million Q3 revenue, points to a business leaning on execution rather than story.
In the near term, the key swing factor remains how efficiently Telix plugs new products like Gozellix into its existing commercial and TMS footprint. The biggest risk still sits in heavy reinvestment and lower margin manufacturing, which can pressure cash generation and earnings, and the latest update does not remove that concern.
The clearest operationally relevant announcement alongside the guidance is the Ekalia collaboration around astatine 211 production in the U.S. This ties Telix Pharmaceuticals more tightly into supply of an alpha emitting isotope that underpins early programs such as TLX102 Tx and other future 211At candidates.
For you as an investor, that alliance links directly to pipeline execution risk and future catalysts. Reliable isotope access can help reduce one bottleneck for theranostic trials, although the SEC subpoena, competitive PSMA imaging market and low margin RLS footprint still frame how fast any therapeutic shift might show up in reported numbers.
What Telix Pharmaceuticals' Consensus Forecasts Assume
Telix Pharmaceuticals' current analyst narrative ties its commercial story to some fairly specific numbers. Analysts are working off an expected 14.9% annual revenue growth rate over the next 3 years, earnings today of $33.5 million and a consensus earnings forecast of $62.5 million by 2029. That implies earnings almost doubling, an increase of about 1.9x from current levels. The same 2029 framework also assumes revenue of $1.4b.
Uncover why Telix Pharmaceuticals' fair value indicates an 82% potential upside to its current price that could narrow quickly.
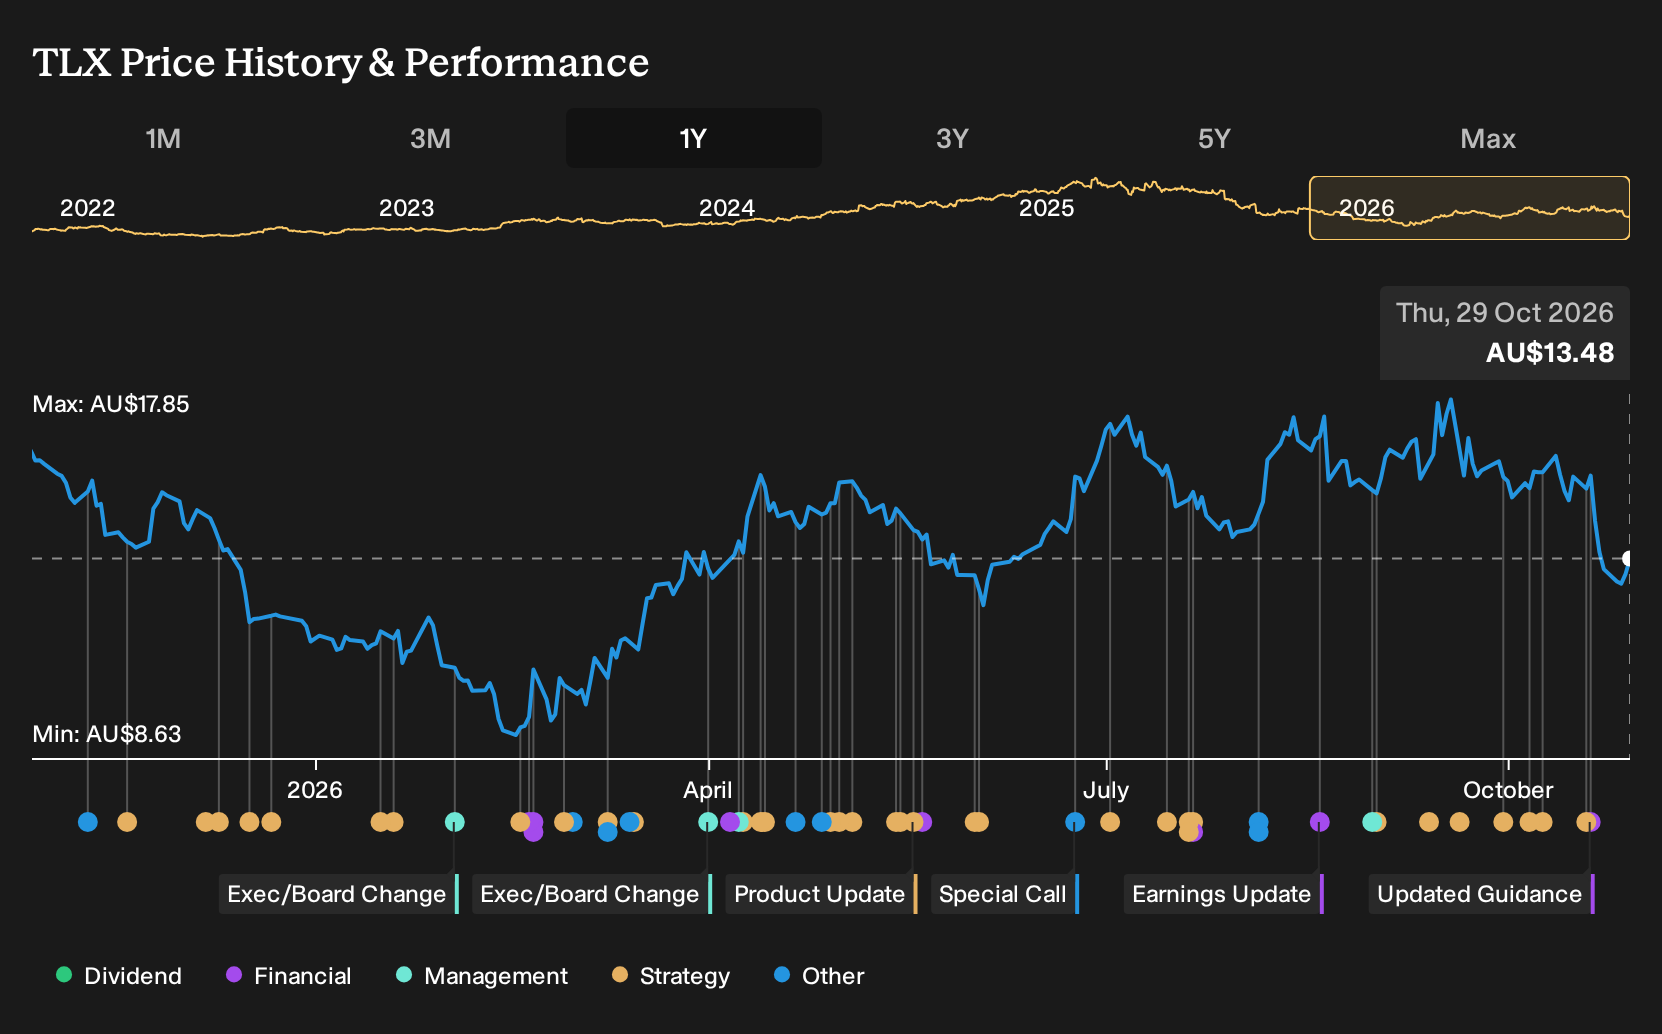
Exploring Other Perspectives
One alternate view highlights Telix Pharmaceuticals’ vertical integration as the key swing factor. The most optimistic analysts were already modelling revenue of about $1.6b and earnings of $199.2 million by 2029 before this guidance and Q3 data. That is far above consensus, and it shows how sharply opinions can differ. You can now compare those pre event assumptions with the new information and decide which narrative you think could shift most.
Explore 5 other Telix Pharmaceuticals fair value estimates, including one that suggests as much as 134% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Telix Pharmaceuticals research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Telix Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Telix Pharmaceuticals' overall financial health at a glance.
Looking for more investment ideas beyond Telix Pharmaceuticals?
Once you have formed a view on Telix Pharmaceuticals, it often helps to widen the lens and see what other companies might offer a different balance of risk, income and quality. The Simply Wall St Screener can surface focused shortlists that match the kind of opportunities you want to research next.
- If capital preservation sits near the top of your priorities, you might start with a basket of companies that score well on stability and financial risk by checking out 6 resilient stocks with low risk scores.
- If value is your main hunting ground, you can compare Telix Pharmaceuticals with a curated group of companies that combine quality fundamentals with attractive pricing by reviewing the 2 high quality undervalued stocks.
- If you want to uncover less crowded stories, consider a collection of under the radar businesses with solid underlying metrics by scanning the 15 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com