


EN
Quarterly Earnings Might Change The Case For Investing In Alamos Gold Stock (TSX:AGI)
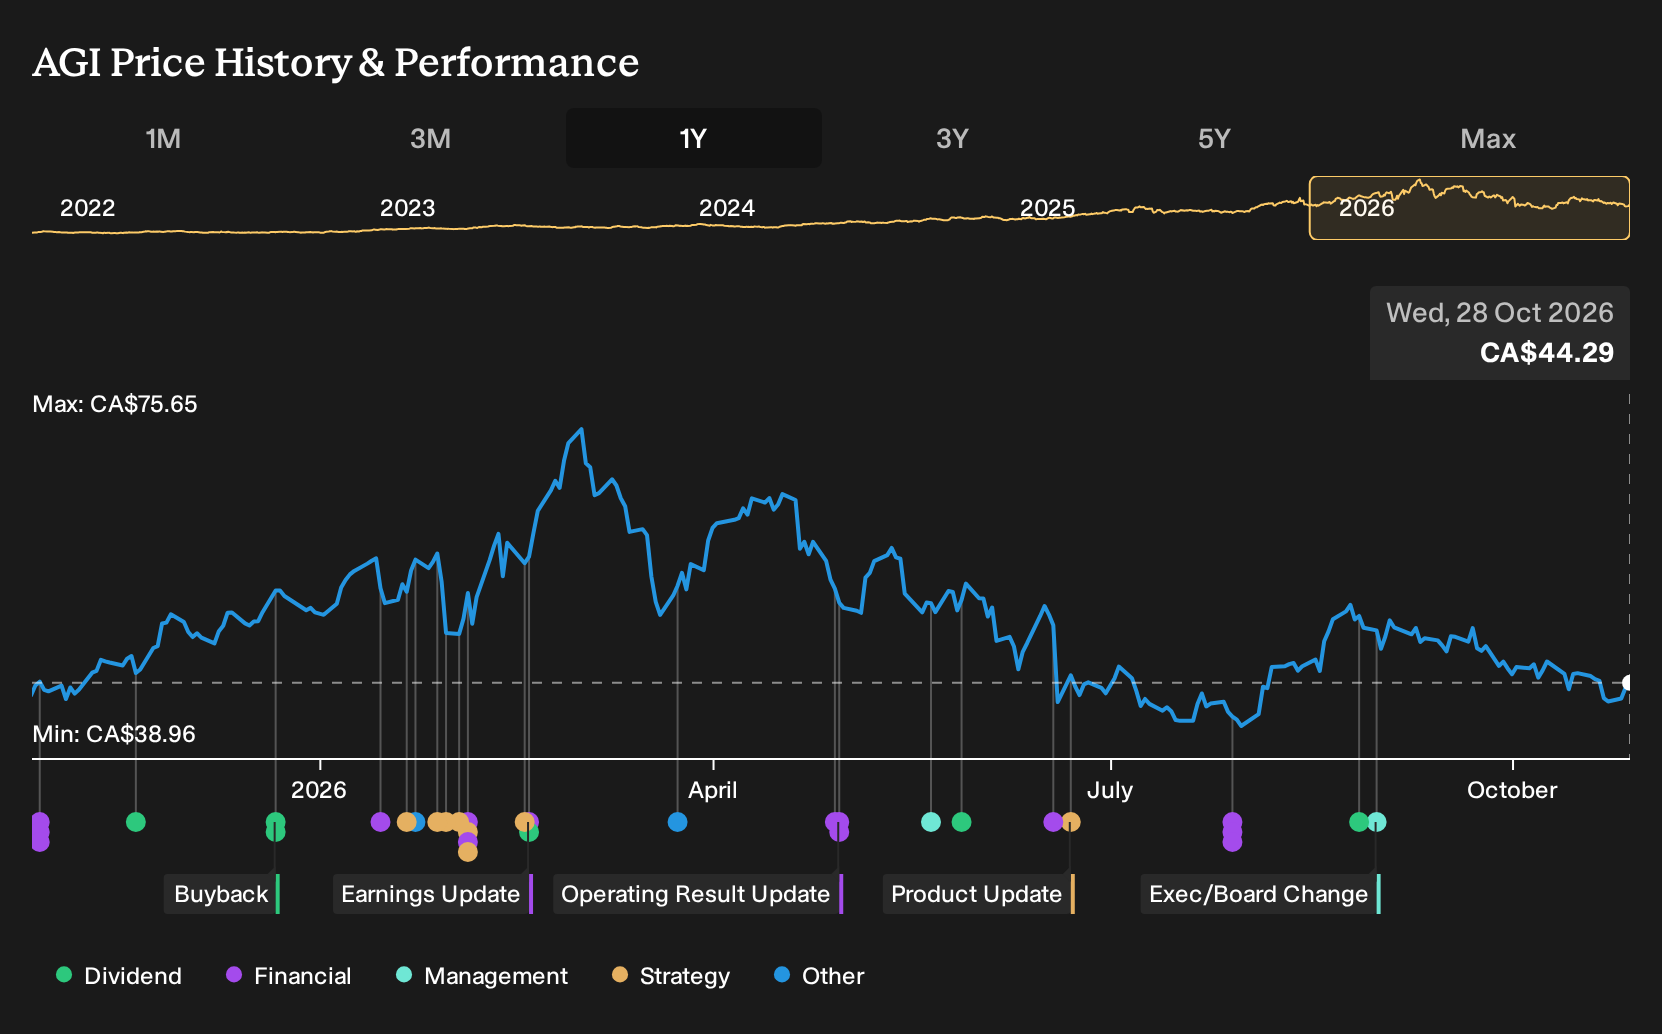
- Alamos Gold reported third quarter 2026 results with sales of US$510.4 million and net income of US$165.6 million, alongside updated nine month earnings and production figures.
- The company reported higher year to date sales and earnings per share, but lower quarterly gold production compared with a year earlier, and full year production guidance of 510,000 to 560,000 ounces.
- We will look at how Alamos Gold's investment narrative aligns with these third quarter earnings, particularly the decline in quarterly production.
Compare how Alamos Gold stacks up against other producers and scan a curated list of potential peers with the 35 elite gold producer stocks as the sector digests these latest production and earnings figures.
Alamos Gold Investment Narrative Recap
For an investor in Alamos Gold, the story hinges on whether the company can convert its existing mine portfolio and projects into consistent, cash generative production while managing costs. The third quarter showed higher sales but lower quarterly net income and lower gold output compared with a year earlier, which keeps execution risk around production and cost control front and center.
The short term catalyst still sits in stabilising output from current operations and keeping all in sustaining costs from drifting higher. The production guidance of 510,000 to 560,000 ounces frames expectations. The decline in third quarter volumes does not radically change the big picture, but it keeps attention firmly on operational delivery.
The nine month earnings update is most relevant here. Sales of US$1,701.2 million and net income of US$627.4 million for the period, both above the prior year, show that Alamos Gold can still generate higher revenue and earnings even as quarterly production steps down.
That mix of higher year to date profitability with softer recent volumes puts execution at individual mines under the microscope. Progress on integrating assets like Island Gold with Magino and containing any further cost inflation remains the key operational catalyst, while the biggest risk is that production or cost targets slip and erode the earnings profile implied by recent results.
What The Current Alamos Gold Forecasts Assume
Alamos Gold's current analyst narrative rests on forecasts that point to US$3.6b in revenue and US$1.5b in earnings by 2029. This implies revenue growth of 16.9% per year and an earnings uplift of about US$300m from US$1.2b today to the US$1.5b consensus level in 2029.
Uncover why Alamos Gold's fair value indicates a 48% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bullish angle on Alamos Gold treats the Island Gold expansion as the real swing factor, rather than near term production softness. The most optimistic analysts were pencilling in revenue growth of 28.1% a year and earnings of US$2.3b by 2029 before these quarterly numbers. Use this earnings miss and guidance to test whether that story still fits for you.
Explore 4 other Alamos Gold fair value estimates, including one that suggests up to 279% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Alamos Gold research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alamos Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alamos Gold's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alamos Gold?
If the Alamos Gold story has sharpened your thinking and you want to stress test that view against other opportunities, the Simply Wall St Screener can help you scan a broader opportunity set in a focused way.
- If capital preservation is high on your list, start with companies that pair resilience with measured risk using the 8 resilient stocks with low risk scores.
- For investors hunting for mispriced quality, filter for financially strong businesses that trade below their estimated worth through the 4 high quality undervalued stocks.
- Income focused readers can zero in on companies with higher yields and sturdier payout profiles by checking the 3 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com