


EN
What Alfa Laval Doubters Got Wrong
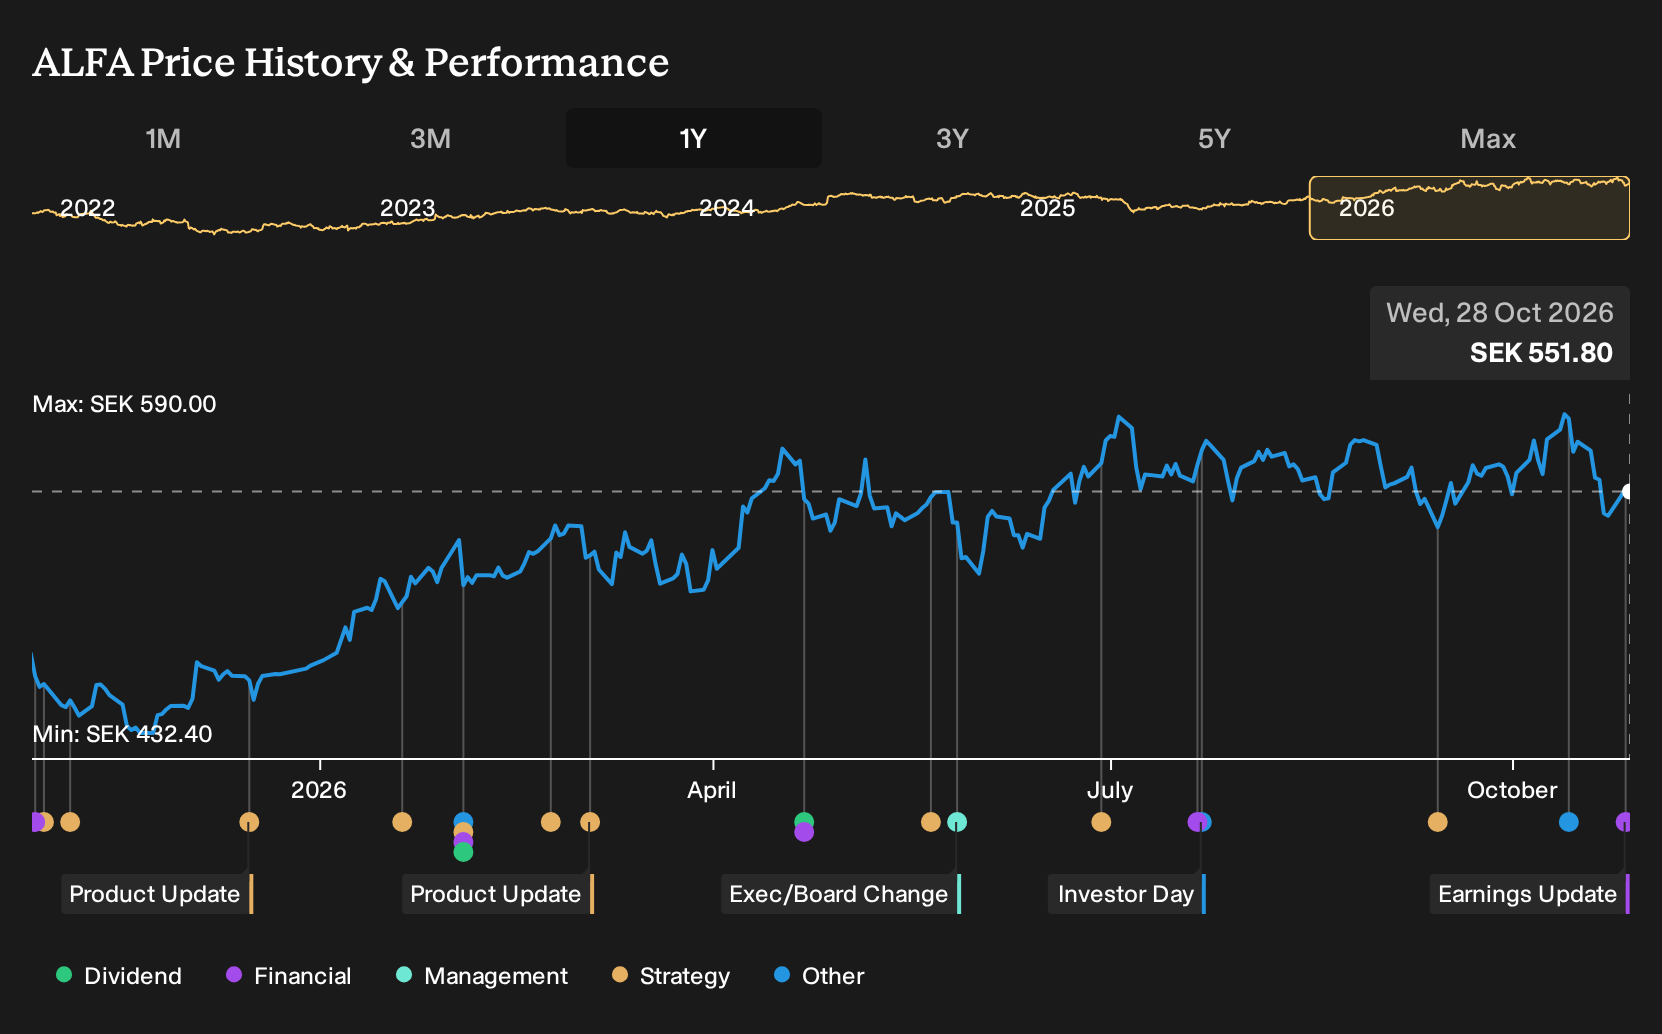
If you only skimmed Alfa Laval headlines this year, the eye catcher might have been its largest-ever HVO pre-treatment contract for Acelen’s Brazilian SAF biorefinery, a concrete bet on renewable fuels equipment. Holding Alfa Laval over the past year would have returned 23.2%, including dividends. If you were weighing a purchase back on 28 October 2025, what exactly did you have to believe about these kinds of decarbonization projects to feel comfortable buying in?
The easy part of this move is behind Alfa Laval. Zero in on 192 high quality undervalued stocks for companies trading below our estimates.
The Two Alfa Laval Stories Investors Had To Weigh Up
The shares cost SEK460 at the start of the period, which left you deciding how much upside or downside the ongoing decarbonization and water treatment push might really justify for Alfa Laval.
The bullish narrative argued that a fair value of SEK530, the price implied if its optimistic assumptions played out, was reasonable if expanding LNG and hydrogen exposure from the Fives Cryogenics deal materially lifted long term earnings power.
The bearish view pointed to a fair value of SEK345 and focused on the risk that faster decarbonization would leave legacy fossil fuel oriented heat transfer and separation products at risk of becoming obsolete.
What The Evidence Around Alfa Laval Actually Tested
The largest HVO pre treatment order for Acelen and the Desmet integration both leaned toward the optimistic Alfa Laval story that decarbonization projects could support equipment demand. At the same time, Q3 2026 results showed revenue at SEK18,596 million and net income at SEK2,233 million, with net margin slipping from 13.3% to 12.0%. As a result, profitability resilience remained an open question. Overall, the evidence cut both ways.
The key assumption here was not just whether low carbon orders arrived, but whether they held or lifted earnings quality. When you look at another industrial, track whether projects tied to new themes coincide with stable or improving net margin rather than only higher sales or contract headlines.
What Alfa Laval's Recent Run Now Asks You To Believe
Alfa Laval trades at SEK552 today, after a 23.2% gain over the past year. The selected Narrative’s Fair Value sits above that price and leans on how effectively the business can turn its current project backlog into earnings power rather than on new themes alone.
The Narrative puts most weight on Alfa Laval’s order visibility, data center and Framo capacity programs and rising service share. The crux for anyone paying SEK552 is whether that elevated order book and investment push can translate into sustained, efficiently executed volumes without persistent margin pressure.
"Bullish analysts expect Alfa Laval to convert its record order book, data center capacity programs, marine CapEx cycle and growing energy transition pipeline into higher through-cycle earnings power than the current share price assumes. The main requirement is that Alfa Laval turns its elevated investment in data center cooling, Framo pumping systems and global service capability into sustained, efficiently executed volumes, while avoiding margin erosion from product mix or project-related issues."
The price and this Narrative do not agree. → Uncover what this Narrative says Alfa Laval is actually worth
Looking Beyond Alfa Laval
After thinking through Alfa Laval, you might look one step sideways. Data centers behind that order book still need something basic.
High powered computing throws off a huge amount of heat. Air cooling alone struggles, so operators rely on liquid systems built for constant use.
One specialist engineer designs the power and thermal gear that keeps these halls running. Its equipment helps AI facilities stay online, efficient and within temperature limits.
This is not about eye catching chips. It is about whoever quietly owns the pipes, pumps and controls that everything else depends on.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 68% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com