


EN
Core (TSE:2359) Stock Can Q2 Earnings Sustain Margin Gains
Core came into this Q2 2027 print with a reputation for steady earnings power and a modest P/E tag, yet the stock had slipped over the past week and month. Fresh results show basic earnings per share of ¥44.12 on revenue of ¥6,791.58 million, keeping profit generation solidly in focus. The real story is the margin picture. Net income of ¥634.46 million for the quarter sits against a trailing twelve month net profit margin of 10.7%, which is particularly relevant for long term holders in light of the recent share price drift.
Like Core's earnings profile but uneasy about the recent share price drift around those margins? Compare it with other companies that pair resilient profitability with sturdy balance sheets in our list of solid balance sheet and fundamentals stocks (23 results)
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥6,791.58 million vs. ¥6,385.29 million (up about 6.4%)
- Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): ¥634.46 million vs. ¥638.44 million (broadly flat, slightly lower)
- Basic EPS (Q2 2027 vs Q2 2026): ¥44.12 vs. ¥44.44 (marginally softer)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 10.7% vs. 9.7% (higher profitability on recent earnings)
Core’s earnings and margins improved while its P/E stayed much lower than rivals. Ask Charlie what makes Core look undervalued versus peers.
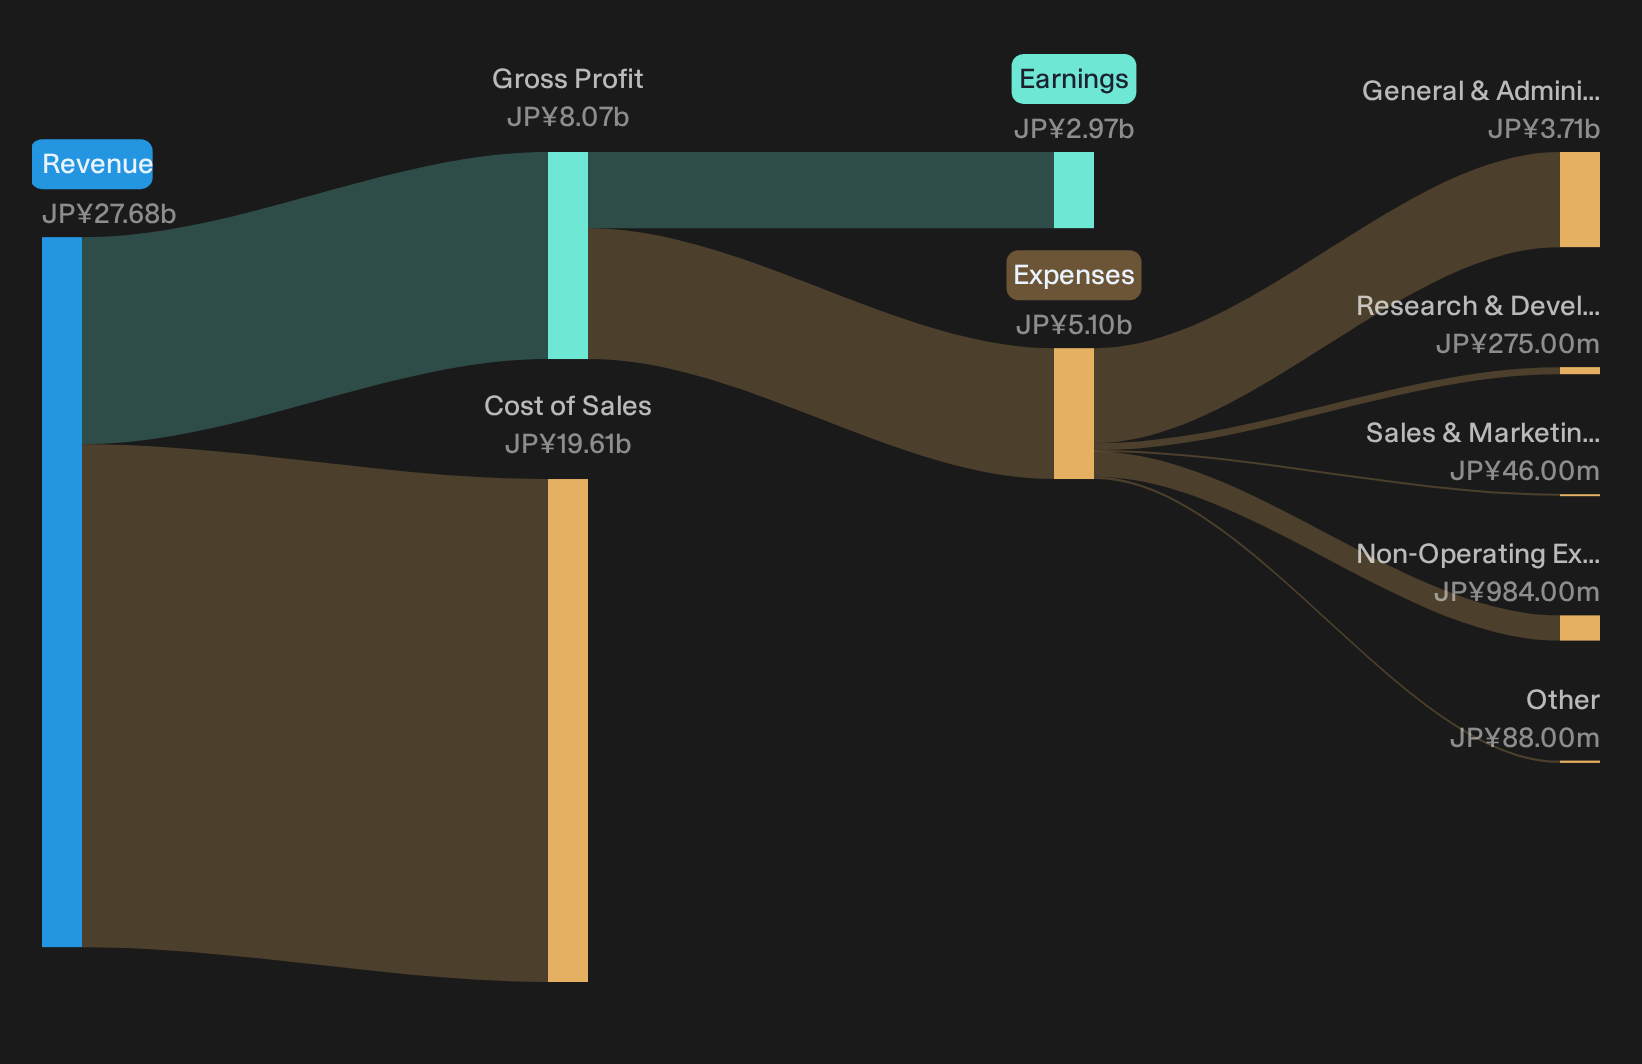
Core earnings, steady profits and bullish signals
For anyone leaning positive on Core as a steady digital infrastructure player, these Q2 numbers mostly cooperate. Revenue of ¥6,791.58 million compares to ¥6,385.29 million a year ago, which points to a business still finding work across its ICT and industrial niches. Trailing net margin at 10.7% versus 9.7% supports the idea that Core can turn that activity into consistent profit, even with basic EPS almost flat year on year. For a services firm in competitive Japanese IT, that mix keeps the constructive long term story alive.
Core risk checks, where the bear case bites
More cautious investors will focus on the softer parts of this print. Net income excluding extra items is essentially unchanged at ¥634.46 million compared with ¥638.44 million, and basic EPS of ¥44.12 is slightly weaker. That plateau in earnings power sits alongside a share price that drifted about 6.3% over 7 days and about 1.3% over a month. For a stock framed as a reliable ICT contractor, this raises fair questions about how much operating leverage Core really has if pricing pressure or project mix shift even modestly.
With earnings power flattening this quarter while the share price trades below DCF estimates, the key question is whether Core has the balance sheet strength to support those dividends and fund future projects. Check the full solvency and liquidity breakdown in our financial health analysis of Core stock.Hunt For Mispriced Cash Flows
Core just showed that earnings stability and recent share price drift can coexist uncomfortably. The potential opportunity is to research stocks that could be undervalued before the market reacts to any mismatch.
- Company 1 - 39% below our estimate - builds virtual performers and interactive events that brands adopt for online campaigns.
- Company 2 - 47% below our estimate - runs talent platforms and HR tools that employers adopt when fragmented systems fail to track workforce data.
- Company 3 - 42% below our estimate - expands multi service auto sites that engage drivers as they transition from purchase to maintenance.
That is three of the list. See every one of the 15 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com