


EN
Cawachi (TSE:2664) Q2 Earnings Flag Thin Margins Beneath Premium Valuation
Cawachi carries a reputation as a premium priced retail stock, yet Q2 2027 earnings landed with a quieter kind of progress. The company posted basic earnings per share of ¥51.48 on revenue of ¥72,162m, while trailing net profit margin sits at 1.1% after a heavy ¥2.3b one off hit over the past year. The share price, at ¥4,070 after today’s close, leaves the stock trading below a discounted cash flow value estimate, even as the P/E of 30.4x keeps the bar high for believers in the long term thesis.
Love the premium Cawachi brand but uneasy about a 1.1% net margin and a rich 30.4x P/E? Check out our list of stocks that pair stronger profitability with sturdier balance sheets in the list of solid balance sheet and fundamentals stocks (23 results)
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥72,162m vs. ¥74,332m (reported top line was slightly lower year on year)
- Net Income (Q2 2027 vs. Q2 2026): ¥1,143m vs. ¥1,412m (quarterly profit was weaker than the prior comparable period)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥51.48 per share vs. ¥63.22 per share (earnings per share declined versus last year’s quarter)
- Trailing Net Profit Margin (Last 12 Months vs. Prior Year): 1.1% vs. 1.6% (profitability narrowed, with results affected by a ¥2.3b one off loss)
Earnings only tell part of Cawachi's story, because the cash that actually comes in and out of the business is what valuation focused investors usually watch most closely. If you look at Cawachi's cash flows instead of the latest earnings line, the stock could be a clear 17% undervalued.
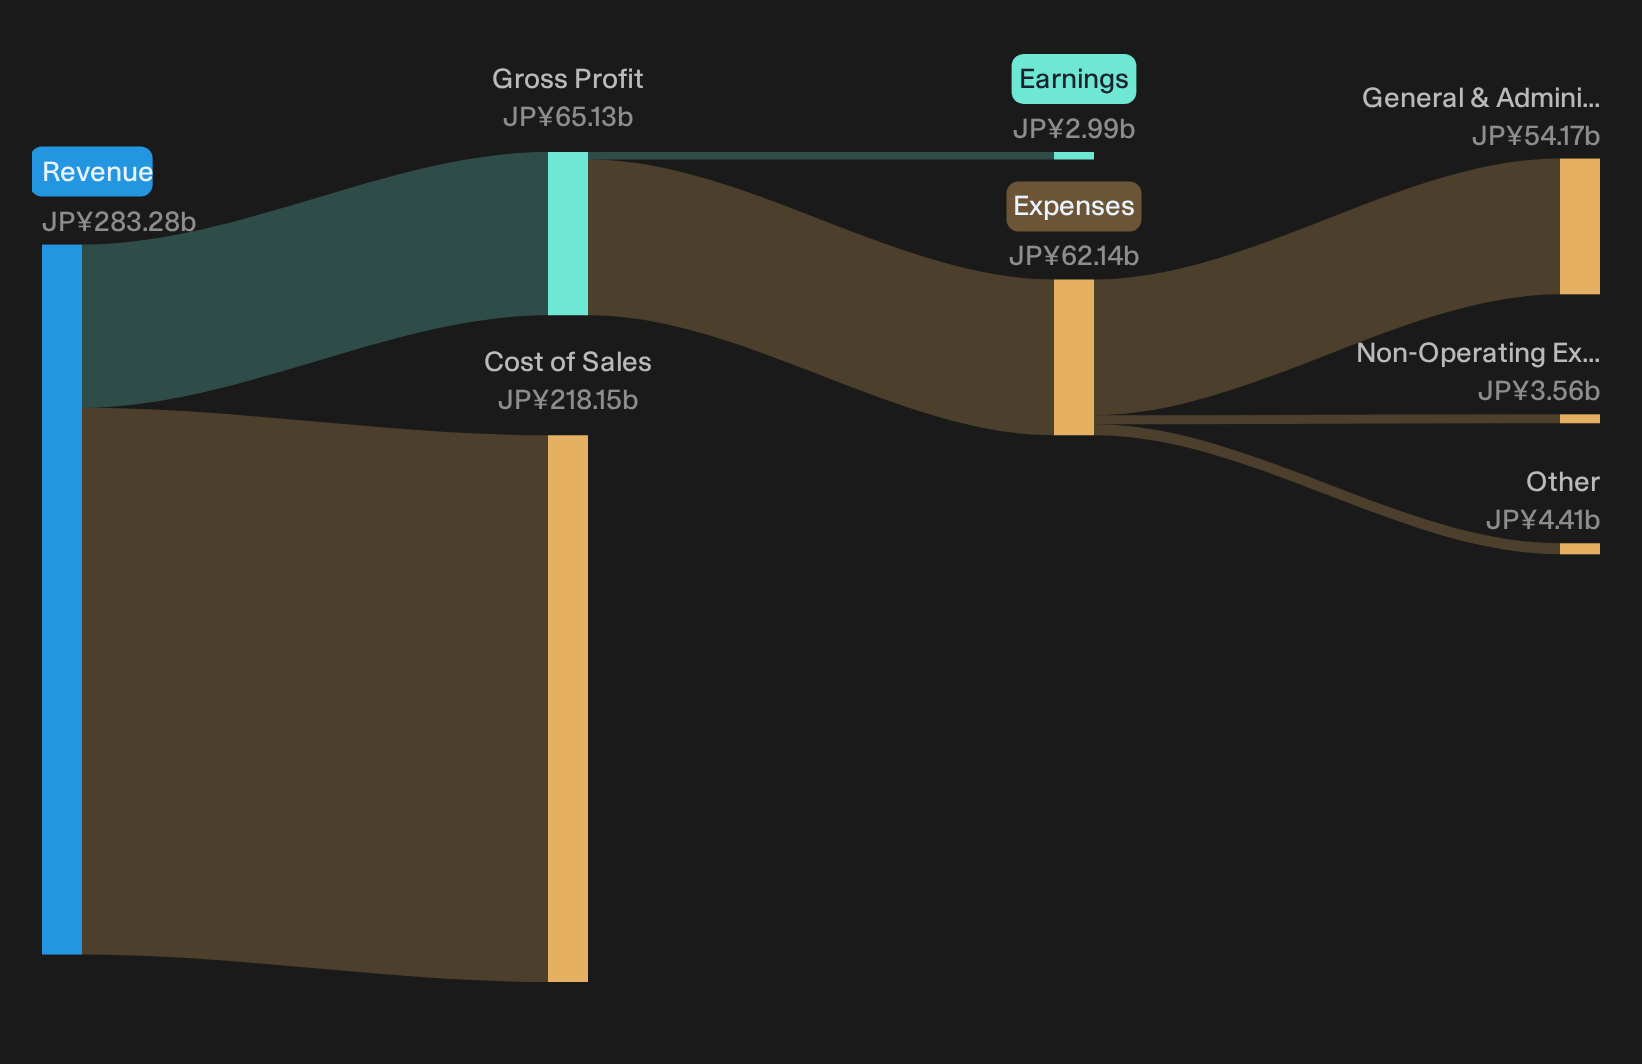
Cawachi’s Defensive Story Meets Softer Earnings
Bulls lean on Cawachi as a defensive healthcare retailer tied to everyday demand. The latest quarter still fits that slow and steady script, with positive earnings and a 1.1% trailing net margin, even after a ¥2.3b one off hit. Revenue of ¥72,162m and quarterly profit of ¥1,143m point to an operation that continues to generate cash and keep the doors open. Recent share price gains over 30 and 90 days also suggest investors have not abandoned the idea of Cawachi as a resilient, if modest, compounder.
Thin Margins Keep The Cawachi Bear Case Alive
Caution around Cawachi focuses on a mature, crowded drugstore market and pressure on profitability. The latest figures give that concern some backing. Revenue and net income both sit below the prior year period, while trailing net margin eased from 1.6% to 1.1%, even after adjusting for the one off loss. A business selling essentials with such slim profitability leaves little room for error on pricing or costs. Recent share price strength does not fully offset the signal from those thinner economics, so the more cautious narrative still carries weight.
After a 1.1% profit margin and a big one off adjustment, the thin cushioning leaves little room for mistakes. Review the independent risk analysis for Cawachi which shows 4 important warning signsHunt Beyond Cawachi’s Headline Margins
Cawachi just reminded investors that a premium label can still come with tight economics. The real opportunity could be spotting stocks that look mispriced before the crowd closes the gap.
- Company 1 - 44% below our estimate - serves smaller enterprises seeking combined deposit, lending and leasing solutions for complex financing needs.
- Company 2 - 39% below our estimate - creates virtual talent and digital events that entertainment partners use to engage online fan communities.
- Company 3 - 40% below our estimate - offers low code business apps that departments adopt when email and spreadsheets can no longer manage workflows.
That is three of the list. See the full list of 15 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com