


EN
Protagonist Therapeutics (PTGX) Is Back In The Spotlight, What Is Catching Attention?
Protagonist Therapeutics (PTGX) is drawing attention after analysts recently raised earnings per share estimates in unison. This shift often reflects changing expectations around a biotech pipeline and its funding needs.
At a share price of $142.14, Protagonist Therapeutics has seen momentum build over 2026, with a year to date share price return of 63.04% and a 1 year total shareholder return of 82.58% that sits on top of a very large 3 year gain of more than 8x and a multi year run that exceeds 3x. Recent conference appearances and upcoming investor events keep the story in front of institutions as analysts lift earnings expectations.
Spot similar high-conviction biotech stories in our hand picked list of 19 high quality undiscovered gems to compare how Protagonist Therapeutics stacks up against other under-the-radar compounders.After a surge like Protagonist Therapeutics has just logged, the choice sharpens quickly. Is it better to accept today’s price, or wait and risk the story outrunning a pullback that never comes?
Most Popular Narrative: 19% Undervalued
Protagonist Therapeutics is framed by the prevailing narrative as undervalued, with an implied fair value of $174.69 against the latest close at $142.14. This places significant emphasis on execution across its royalty engine and pipeline.
The transition to a royalty and milestone funded model, with around US$850 million in cash and no anticipated equity based financings in the foreseeable future, gives Protagonist Therapeutics room to advance its pipeline and run a US$300 million share repurchase program. This can influence per share earnings metrics even if total profit is unchanged.
See why 3 investors see Protagonist Therapeutics as 19% undervalued.
Result: Fair Value of $174.69 (UNDERVALUED)
Still, two weak spots could flip the Protagonist Therapeutics story fast if they break the wrong way: ICOTYDE or MIMRYLO royalties undershooting, or rich P/E expectations compressing sharply.
Find out about the key risks to this Protagonist Therapeutics narrative.
Another View: Protagonist Therapeutics Through The P/E Lens
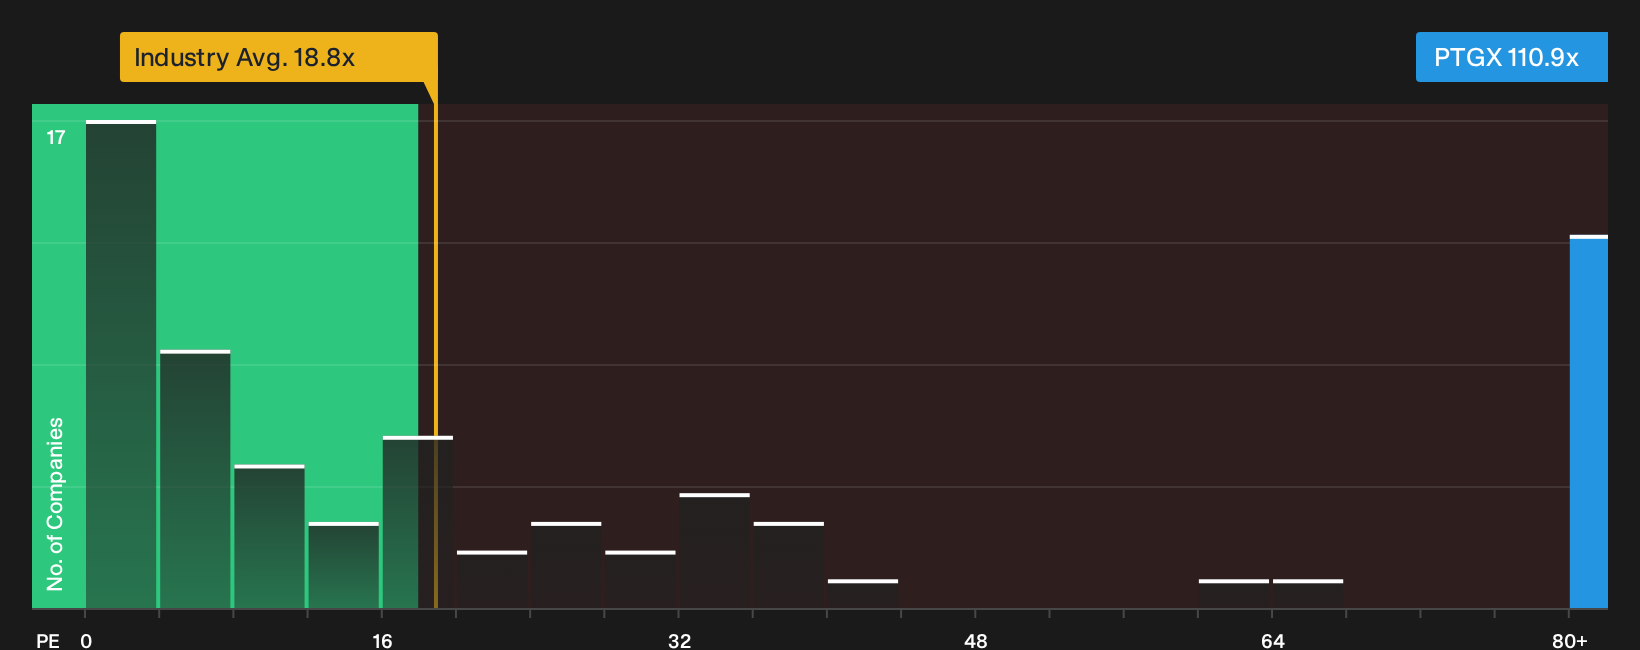
There is a very different message when Protagonist Therapeutics is viewed through its P/E ratio. The stock trades at 110.9x earnings, compared with 94.9x for peers and 18.8x for the broader US Biotechs group. The fair ratio sits at 27.6x. That gap signals real valuation risk if sentiment cools, even if royalty checks arrive on schedule. Is this a premium you are comfortable underwriting?
To see how the current earnings multiple stacks up against what the numbers imply, and whether the market could drift closer to that fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Feeling the mixed message around Protagonist Therapeutics and its valuation risk taking shape. Pull up the numbers, stress test the assumptions, and then weigh those upside angles yourself with the 4 key rewards.
Looking for more ideas beyond Protagonist Therapeutics?
Do not stop with one biotech story. Use the screener to surface fresh opportunities that fit your risk profile, income needs, and appetite for mispriced quality.
- Target mispriced quality by scanning a curated 26 high quality undervalued stocks list that filters for stronger fundamentals and cleaner balance sheets.
- Prioritise resilience with a 32 resilient stocks with low risk scores set of companies filtered for sturdier finances and lower overall risk scores.
- Hunt for potential standouts in a 9 elite penny stocks with strong financials pool that focuses on financially stronger small companies rather than pure speculation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com