


EN
Learn Why The Bull Case For Nitto Denko Stock Could Change Following Share Buyback Plan
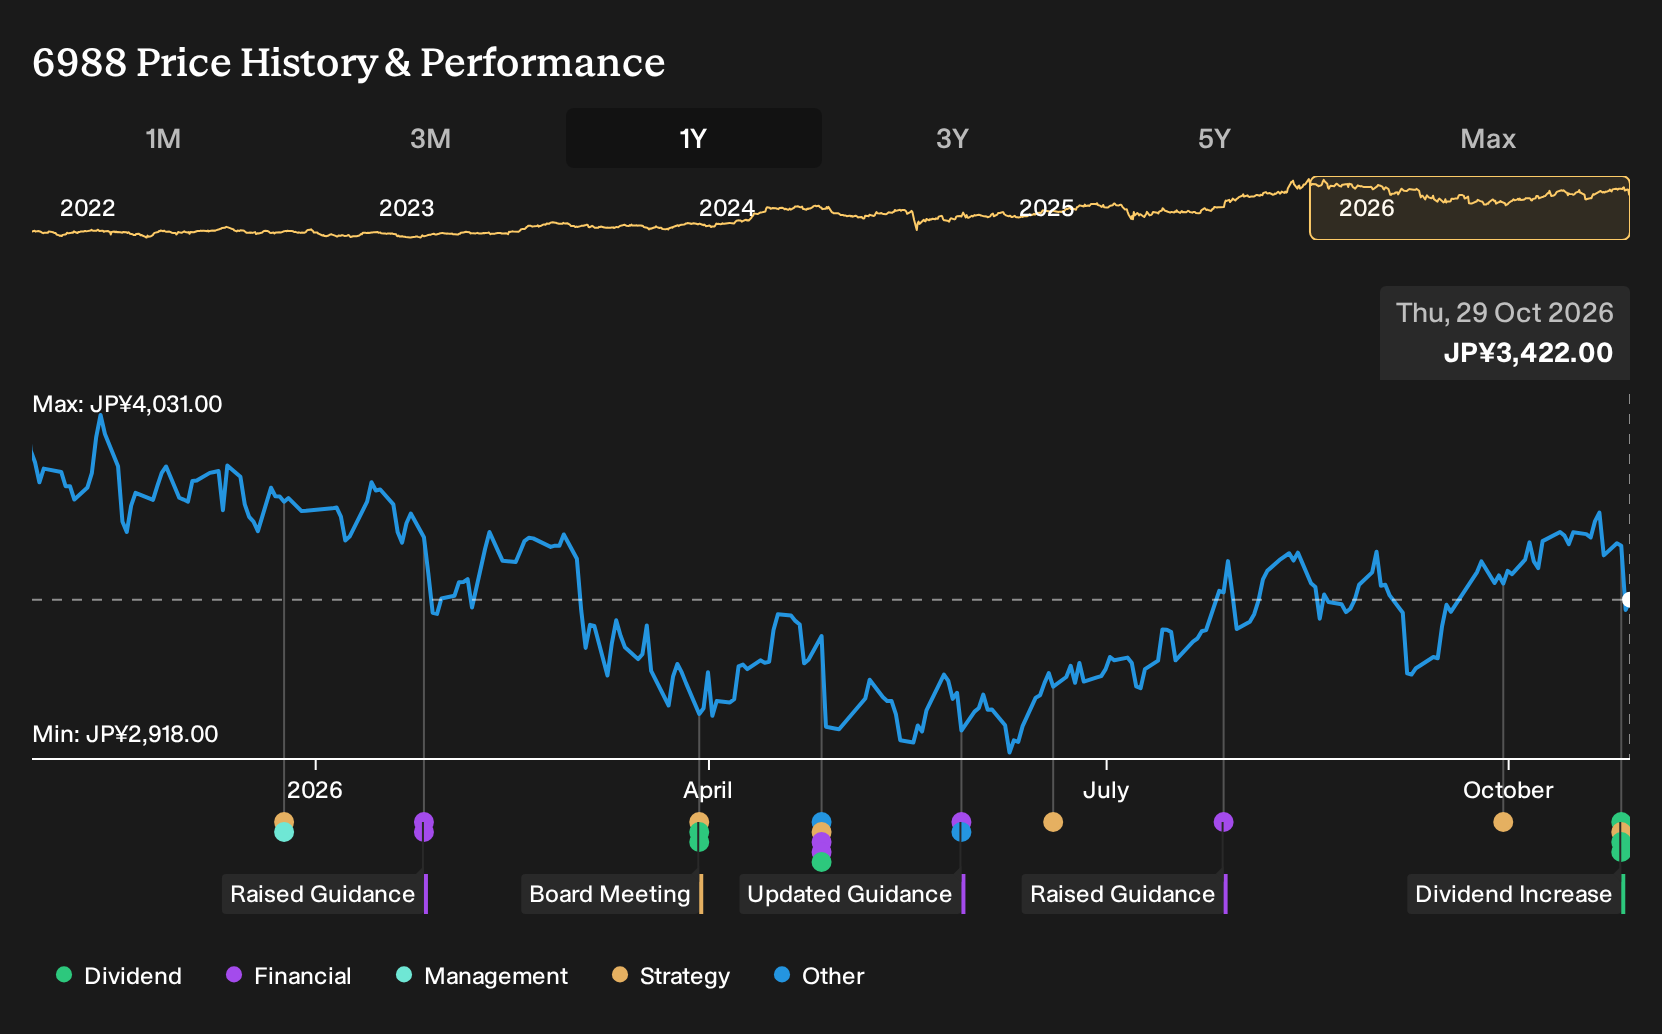
- Nitto Denko announced on October 27, 2026 a share repurchase program of up to 17,000,000 shares, or 2.97% of outstanding shares, for ¥50,000 million and set a second quarter dividend of ¥36.00 per share with updated full year dividend guidance.
- The combination of buyback capacity and higher cash distributions indicates that Nitto Denko is actively using its balance sheet and capital allocation framework to focus on shareholder returns alongside its existing investment plans.
- We will now examine how Nitto Denko's investment narrative interacts with this new share repurchase plan and higher dividend commitment.
Scan how Nitto Denko's capital return move compares by reviewing the hand-picked 29 dividend fortresses that is aligned with similar shareholder payout stories.
Nitto Denko Investment Narrative Recap
Nitto Denko still asks you to believe that heavy investment in semiconductor materials, Human Life applications and high end display products can turn large CapEx into higher quality earnings over time. The near term swing factor is execution at new plants and whether end demand in chips, displays and healthcare absorbs added capacity without squeezing pricing.
The biggest operational risk right now sits with input costs and competitive pressure. Rising raw material expenses and tougher semiconductor and display rivals could keep margins tight, especially with net profit growth already slower than the 5 year pace. The fresh buyback and higher dividend do not materially change these near term business drivers.
The clearest operationally relevant move in this news set is the share repurchase program of up to 17,000,000 shares for ¥50,000 million running through March 24, 2027. That sits alongside the Nitto RISE 2028 plan, where roughly ¥300 billion to ¥400 billion of CapEx is already earmarked for semiconductor, Human Life and display projects.
For you as a shareholder, the key question is whether Nitto Denko can keep funding that large investment envelope while also returning cash without stretching the balance sheet. Execution on semiconductor process materials, wastewater membranes and oligonucleotide CDMO projects remains the main catalyst, while the buyback simply tightens the link between that operating performance and per share outcomes.
Nitto Denko's consensus story ties together ¥1,223.2b of forecast revenue and ¥171.0b of projected earnings by 2029, with analysts including 5.1% yearly revenue growth and an earnings increase of about ¥34.9b from ¥136.1b today.
Uncover why Nitto Denko's fair value signals an 11% potential upside to its current price, a discount that could narrow quickly as sentiment shifts.
Exploring Other Perspectives
One alternate view on Nitto Denko leans hard into the semiconductor catalyst. Bullish analysts were already pencilling in revenue of about ¥1,306.0b and earnings near ¥185.3b by 2029, well above the baseline. You can interpret this buyback and higher dividend as fresh information that may lead those optimistic forecasts to be revisited.
Explore another Nitto Denko fair value estimate, including one that suggests up to 12% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgement.
- A great starting point for your Nitto Denko research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Nitto Denko. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nitto Denko's overall financial health at a glance.
Looking for more investment ideas beyond Nitto Denko?
If Nitto Denko has sharpened your focus on capital returns and balance sheet strength, it can pay to widen the lens and see how other companies line up on dividends, financial resilience and potential mispricing using the Simply Wall St Screener.
- For income-focused investing, scan a curated set of payout heavyweights by reviewing the 29 dividend fortresses that match different yield and stability preferences.
- If capital preservation matters most, shorten your shortlist to companies with sturdier finances by starting with a 25 resilient stocks with low risk scores that already screens for resilience.
- To hunt for potential future winners before they attract wider attention, start your next watchlist with a 72 high quality undiscovered gems backed by solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com