


EN
Is Delta Air Lines (DAL) Still Reasonable After A 167% Run?
Delta Air Lines has ridden a powerful three year share price run, and with the stock recently closing at US$80.35 the real question is whether that level still lines up with the earnings the airline is producing. For anyone already on board or thinking about buying a ticket, the issue is less about momentum and more about what the current price asks you to pay for each dollar of profit.
- Over the past 3 years the stock has delivered a very large 167.0% return, which raises a clear question about how much of Delta's earnings power may already be reflected in the valuation.
- Fresh news on aircraft supply and rising fuel costs, including pressure from higher jet fuel prices and the longer dated timing of new Boeing 737 Max 10 capacity, can affect expectations for future profitability and the earnings base investors use to assess the stock.
- The analysts covering Delta Air Lines have run their own numbers. See what analysts think Delta Air Lines's shares could be worth.
The stock's next move may depend on whether Delta Air Lines' current price is well supported by the earnings investors are paying for today.
If you want to stress test the same earnings question across a wider field than just Delta Air Lines, filter for companies through the 26 high quality undervalued stocks.
Is Delta Air Lines Still Cheap on Earnings?
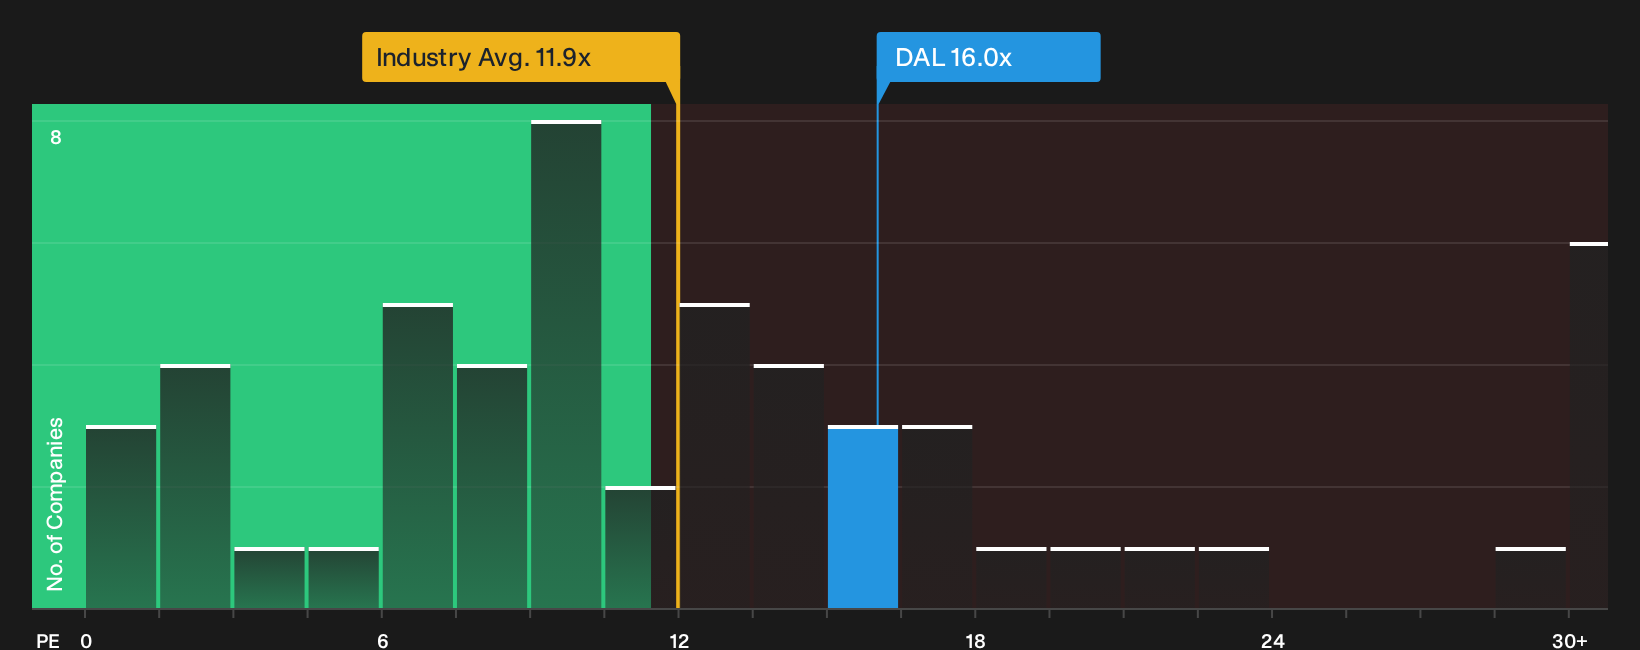
The P/E ratio is a useful yardstick for Delta Air Lines because investors often anchor airline valuations to current and expected earnings. At roughly 16.0x earnings, Delta trades above both the broader airlines sector on about 11.9x and the closer peer group near 11.8x. This means you are paying a higher price per dollar of profit than for many competitors.
The fair value model, which blends Delta's own growth outlook, profitability profile, size and risk into a tailored reference multiple, points to a higher P/E than where the shares change hands today. On that framework, the current premium to peers still screens as undervalued. Despite fuel cost pressure and the delayed timing of new Boeing 737 Max 10 capacity only recently clearing a regulatory hurdle, the market multiple implies investors are not paying up for an aggressive earnings story relative to what this model suggests. That gap between the live P/E and the fair value signal is what the valuation lens below is designed to quantify in more detail. Explore the numbers behind Delta Air Lines's P/E valuation.
The Delta Air Lines Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Delta Air Lines leaves off. They spell out which specific assumptions on revenue growth, profit margins and earnings power would need to hold for the stock to look meaningfully mispriced relative to today's quote, and each narrative anchors a fair value estimate to a defined set of potential catalysts and risks so you can track over time which version of Delta Air Lines' story appears to be unfolding on the Community page.
Community views on Delta Air Lines split between a premium story that is not fully priced in and a cautious read on thin industry economics.
Bull case: 21% undervalued
"Delta is capitalizing on resilient revenue streams such as premium, loyalty, and international segments, with diversified premium, loyalty, cargo, and MRO revenue now representing 61% of total revenue…"
Discover why this Narrative puts Delta Air Lines at 21% undervalued.
Bear case: 27% overvalued
"Yet with its early warning about waning travel demand in March, my original assumptions in February regarding revenue growth and future PE had to be revised downwards…"
Explore why this Narrative puts Delta Air Lines at 27% overvalued.
One more Delta Air Lines check before you close the tab
Price multiples and narratives tell part of the story, yet the analyst blueprints for where Delta Air Lines could be a few years from now offer a very different comparison point. Explore where analysts expect Delta Air Lines to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com