


EN
AMD Stock Outlook: AMD's Meta Deal Boosts AI Growth Prospects
Strategic equity investments between hardware suppliers and hyperscale cloud providers are redefining tech partnerships, directly tying silicon roadmaps to massive data center expansion. By taking direct financial stakes in key customers, semiconductor leaders lock in long-term chip deployment while ensuring their computing architectures power next-generation artificial intelligence workloads.
Deepening this strategic alignment, Advanced Micro Devices (AMD) recently committed $1 billion to Meta Platforms' (META) latest equity offering.
About Advanced Micro Devices
Advanced Micro Devices, better known as just AMD, is a global semiconductor company developing high-performance processors, graphics processing units (GPUs), AI accelerators, and adaptive computing solutions. Its products power data centers, artificial intelligence infrastructure, personal computers, gaming systems, and embedded applications. AMD is expanding its role in the AI chip market through its EPYC server CPUs, Instinct accelerators, and Helios rack-scale systems.
AMD Shares Rally on AI Growth Expectations
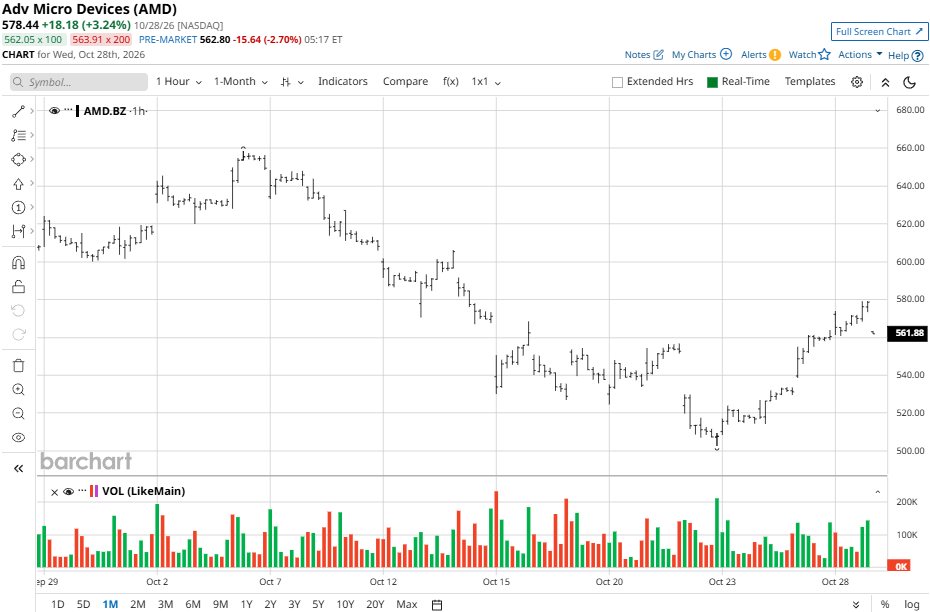
AMD stock has delivered a powerful rally in 2026, supported by accelerating artificial intelligence investment, strong demand for data center chips, and optimism about the company's ability to compete in the AI infrastructure market. Shares closed at $578.44 on Oct. 28, up approximately 170% year-to-date (YTD), substantially outperforming the broader market. AMD also crossed a $1 trillion market capitalization in September as investor enthusiasm for AI-related semiconductor stocks intensified.
Q2 2026 Earnings Results
AMD reported second-quarter 2026 revenue of $11.54 billion, up 50% year-over-year (YoY) and approximately 2.3% above analyst estimates of $11.28 billion. Non-GAAP diluted earnings per share reached $1.66, exceeding the $1.55 consensus estimate by approximately 7.1%. The results reflected robust demand for AI computing and server processors, reinforcing AMD's position as a key competitor in the expanding AI semiconductor market.
Financial performance strengthened across several key metrics. GAAP gross margin increased to 54% from 40% a year earlier, while non-GAAP gross margin reached 56%, compared with 43% in the prior-year quarter. GAAP net income climbed to $2.30 billion from $872 million. Data Center revenue surged 107% to $6.72 billion, driven by demand for EPYC CPUs and Instinct GPUs. Client and Gaming revenue increased 6% to $3.84 billion, while Embedded revenue rose 19% to $977 million.
Looking ahead, management forecast third-quarter 2026 revenue of approximately $13 billion, plus or minus $300 million, implying around 41% YoY growth at the midpoint. AMD expects non-GAAP gross margin of approximately 56%.
With its fiscal third-quarter earnings report scheduled for Nov. 3, investors are watching revenue growth, AI accelerator deployments, server CPU demand, and management's forward guidance.
AMD Invests in Meta
Advanced Micro Devices announced a $1 billion investment in Meta Platforms' equity offering, strengthening its strategic partnership with the Facebook parent company and expanding collaboration across artificial intelligence infrastructure. The agreement covers CPUs, GPUs, networking, computing systems, and software designed to support Meta's growing AI workloads and digital services.
AMD said its Helios rack-scale systems are already operating at Meta, while AMD EPYC server processors power Meta's Muse AI agent. The companies are also working to provide immediate support for Meta's AI models, including Muse Spark Open and Muse Glimmer. Building on years of collaboration involving AMD Instinct GPUs, EPYC processors, Pensando networking, and ROCm software, the partnership highlights AMD's push to capture a larger share of the AI data center market. The expanded agreement could strengthen AMD's position as demand for advanced AI computing infrastructure continues to grow.
Is AMD Stock a Buy After the Meta Deal?
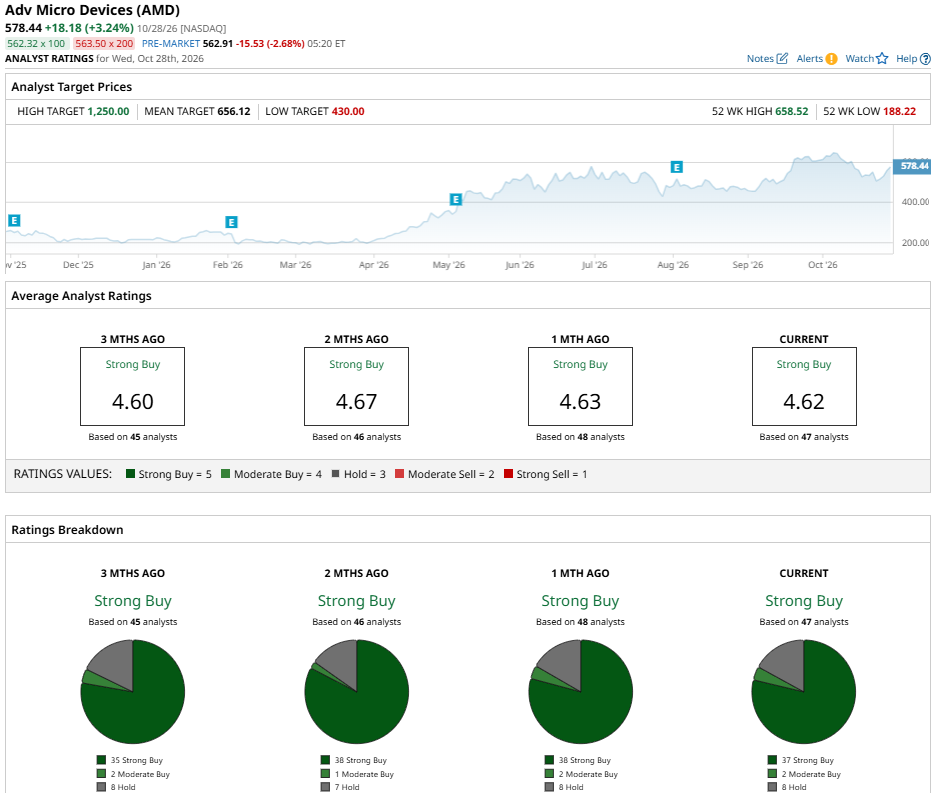
Advanced Micro Devices is strengthening its position in the AI semiconductor market through its expanded partnership with Meta, including a $1 billion investment and collaboration on AI infrastructure. Wall Street maintains a “Strong Buy” consensus rating on AMD, with an average price target of $656.12, indicating approximately 14% upside from the current market price. Among 47 analyst ratings, 37 are “Strong Buy,” two are “Moderate Buy,” and eight are “Hold.” However, investors should weigh AMD's AI growth opportunities against valuation risks, competition, and the company's ability to sustain earnings momentum.
On the date of publication, Ruchi Gupta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.