


EN
What Bumrungrad Hospital Doubters Missed
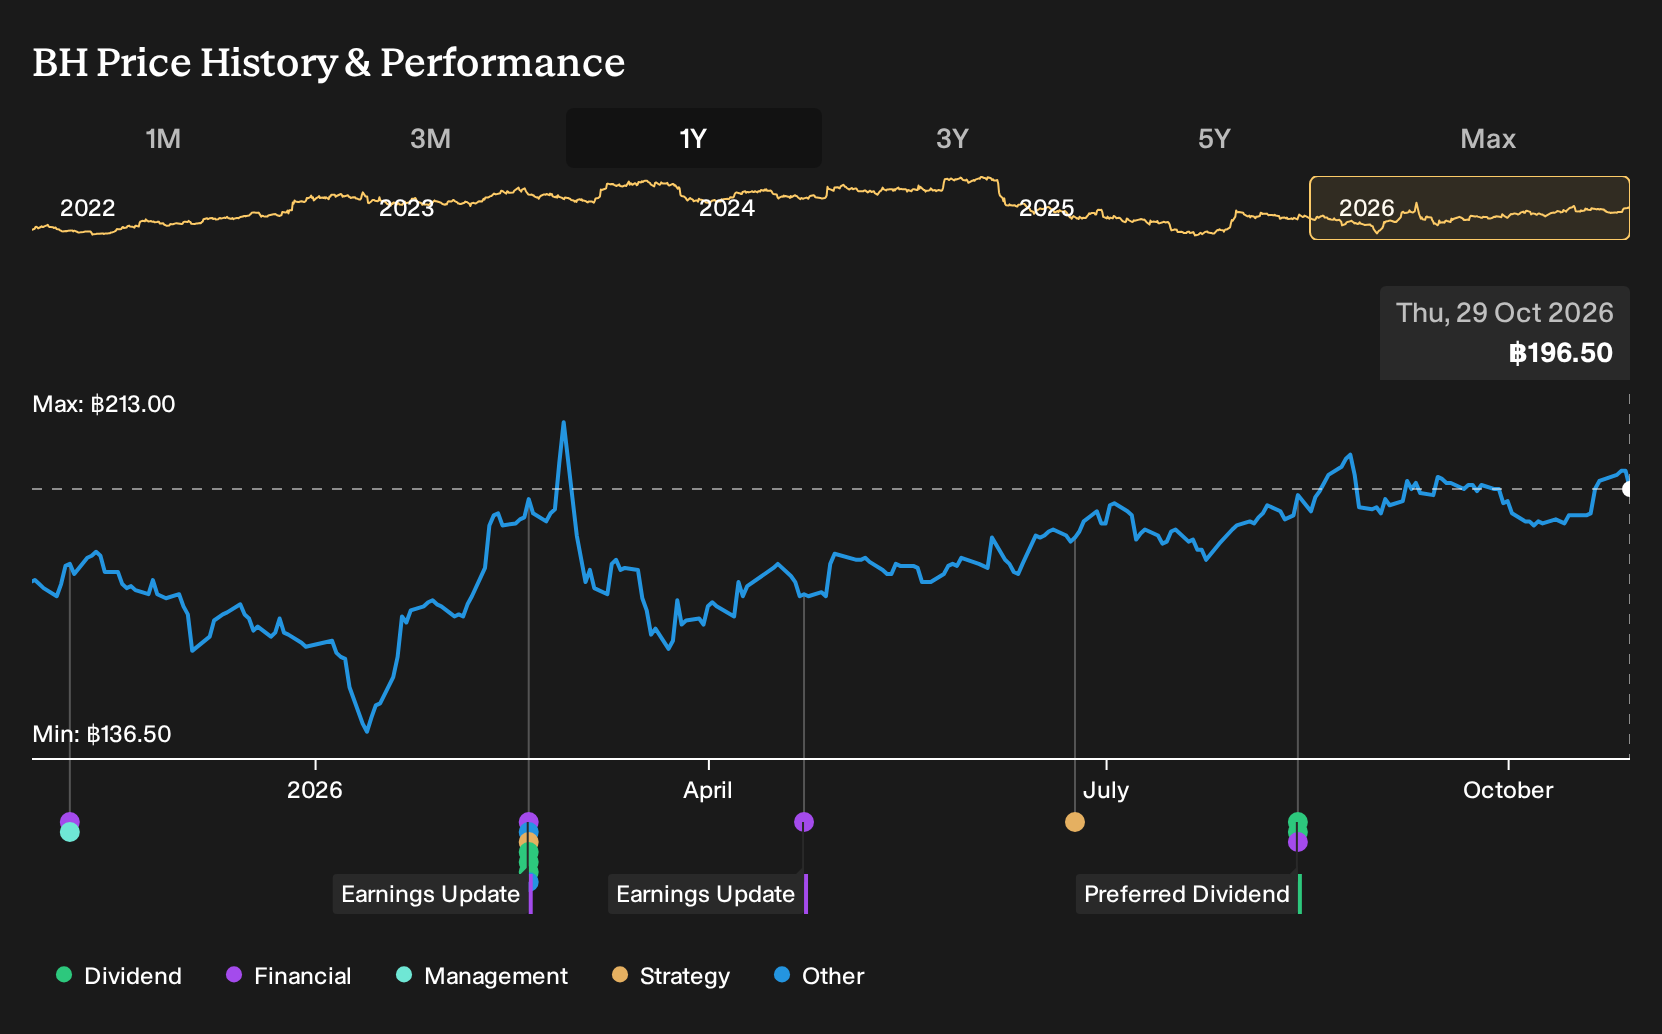
If you focused on Bumrungrad Hospital during this stretch, the eye-catching update was not a headline deal but the Q2 2026 filing that showed THB 6,274.836 million in revenue and THB 1,889.113 million in net income, with net margin at 30.1%. For Bumrungrad Hospital shareholders, the return over the past year was 22.1%, including dividends. If you were deciding whether to buy in back on 29 October 2025, what exactly did you need to believe about this business?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Bumrungrad Hospital has already moved. See which of 191 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Weigh On Bumrungrad Hospital
The shares cost THB174 at the start, and any investor looking at Bumrungrad Hospital then had to decide which future seemed more reasonable.
The bullish narrative put fair value at THB210, based on revenue growing 5.1% a year and profit margin settling near 27.5%, helped by new oncology and robotic surgery capacity.
The bearish view saw fair value at THB151, stressing reliance on international medical tourists and the risk that geopolitical shocks could hit patient volumes and earnings.
What The Results Changed For The Bumrungrad Hospital Thesis
The Q2 2026 report for Bumrungrad Hospital showed revenue at THB 6,274.836m and net income at THB 1,889.113m, above Q2 2025 levels, which supported the growth element of the optimistic story. Net margin slipped from 30.4% to 30.1%, so profitability strength was somewhat closer to the cautious case. Overall, the evidence pointed in both directions.
The key assumption here was that Bumrungrad could grow while protecting high margins. For any hospital stock, it is useful to track revenue, net income, and margin together to see whether expansion is coming through volume, pricing, or higher costs.
What Bumrungrad Hospital’s Price Already Assumes
Bumrungrad Hospital now trades at THB196, up from THB174 over the past year. This Narrative sees Fair Value below that quote, framing today’s level as already pricing in much of the international growth story rather than offering a clear valuation cushion.
The selected Narrative focuses on weakening Thai demand alongside reliance on complex overseas cases and new capacity in Phuket and Bangkok. For today’s price to hold up, an investor needs confidence that higher intensity international volumes and new facilities can offset softer domestic trends without eroding margins.
"The main factor that needs to work in Bumrungrad Hospital’s favor is that high-intensity international case mix and new capacity in Phuket, Bangkok and longevity services through VitalLife offset domestic softness and the expected initial dilution from the Phuket ramp up, while maintaining the company’s strong balance sheet and returns profile."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
How Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 26% below our estimate - uses clinically supported probiotics to deepen adult and oral health direct channels.
- Company 2 - 43% below our estimate - converts a tech-heavy project backlog into higher margin mechanical and electrical work.
- Company 3 - 45% below our estimate - channels heavier marketing and hiring into international store openings and digital-led sales.
That is three of the list. See the full list of 206 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com