


EN
Viatris (VTRS) Stock Looks Undervalued With Sales Support Behind It
Viatris has delivered a powerful share price run in recent years, and with fresh product news in eye care, the obvious question is whether the current valuation is still grounded in what the business actually generates in sales. For anyone watching the ticker today, the issue is not just what moved the stock, but whether the present price lines up with the revenue base behind it.
- Viatris has returned 138.7% over the past 3 years, which puts a lot of weight on the question of how its share price lines up with its underlying sales profile.
- FDA approval for RYZUMVI for presbyopia can influence how investors think about Viatris' future prescription volumes and pricing power, which feeds directly into the sustainability of its sales driven valuation.
- The analysts covering Viatris have run their own numbers. See what analysts think Viatris's shares could be worth.
The stock's next move may depend on whether the current price is well supported by Viatris' sales when set against the Fair Ratio benchmark.
If you want a cleaner benchmark for Viatris and the presbyopia story you just read about, compare it mentally with companies in 36 healthcare AI stocks.
Is Viatris Still Cheap on Sales?
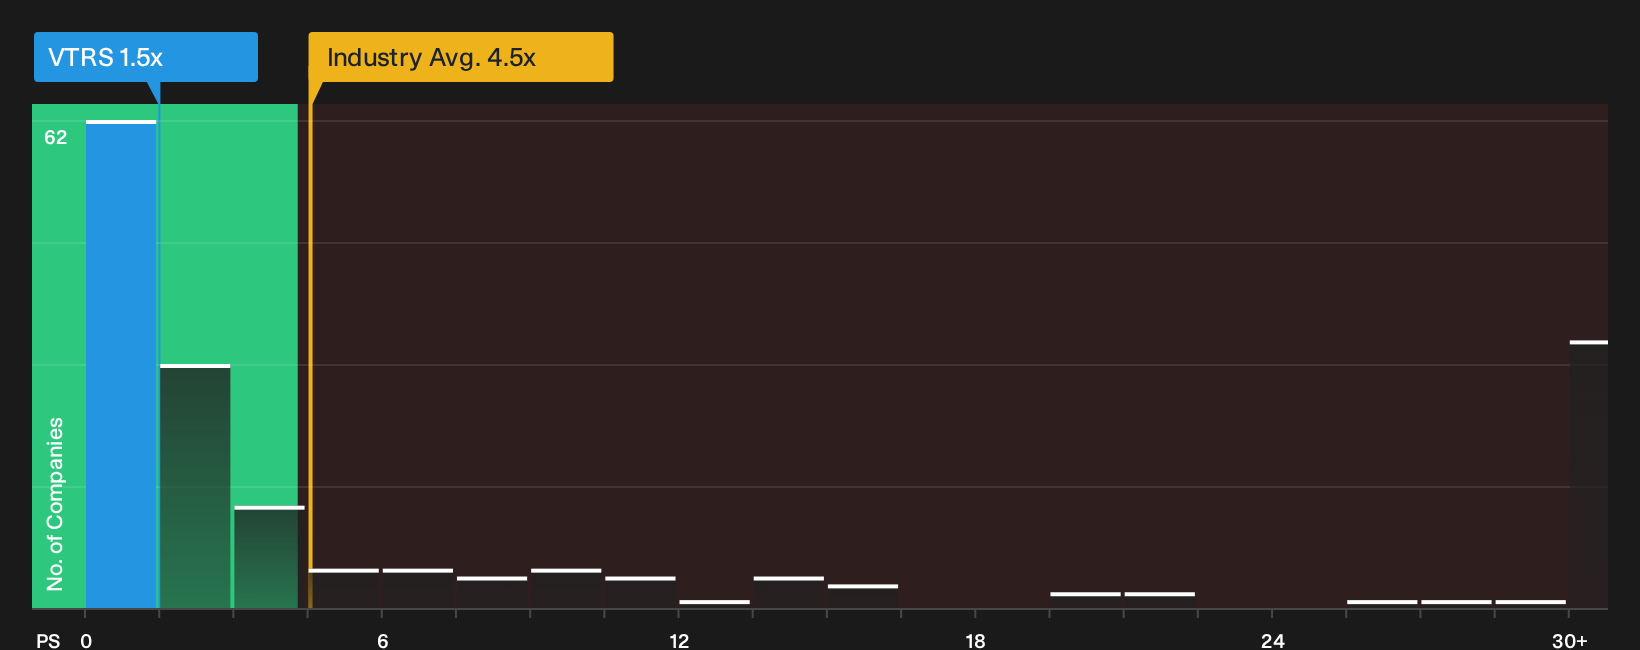
The P/S ratio fits Viatris because current sales are a clearer anchor than reported earnings, which are harder to interpret with a P/E of 52.5x. On this measure, Viatris trades on a P/S of 1.5x, which is well below the Pharmaceuticals industry average of 4.5x and also beneath the peer group at about 5.0x. That gap shows investors are paying a lower price for each dollar of Viatris revenue than for many comparable drug makers.
The Fair Ratio, which blends in factors like sector, profitability patterns, size and risk, points to a higher P/S than where the stock trades today, so the shares screen as undervalued on this framework. Because the recent FDA approval for RYZUMVI in presbyopia adds another specific product to the portfolio, the current discount in the P/S multiple to both peers and the tailored benchmark may appear even more striking to some investors. Explore the numbers behind Viatris's P/S valuation.
The Viatris Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Viatris pick up where the P/S puzzle leaves off and explain which assumptions on growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today's price. Each narrative links its number to a clear view on how Viatris' future expansion, profitability and risk profile might evolve, giving you a reference point you can revisit as new information emerges on the Community page.
Viatris draws sharply different reactions in the community, with one group arguing the stock is too cheap and another seeing expectations already stretched.
Bull case: 52% undervalued
"Viatris continued to generate massive cash flows and used them to reduce debt, stabilize margins, and invest selectively in new areas such as biosimilars and cardiovascular treatments..."
Discover why this Narrative puts Viatris at 52% undervalued.
Bear case: 44% overvalued
"The numbers currently reflected in the share price imply that Viatris shares already discount a successful transition toward value-added medicines, continued growth in regions such as Greater China and sustained capital returns, which leaves limited room for disappointment if execution slips..."
Explore why this Narrative puts Viatris at 44% overvalued.
Before you act on Viatris’ valuation, there is one more piece to check
Price ratios only tell part of the story for Viatris, because the people setting priorities and their pay structures can tilt outcomes in ways the multiples alone never show. See who runs Viatris and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com