


EN
What You Need To Know Ahead of Hewlett Packard Enterprise's Earnings Release
With a market cap of $80.1 billion, Hewlett Packard Enterprise Company (HPE) develops intelligent solutions across areas like servers, hybrid cloud, networking, and financial services, serving enterprises and public sector organizations worldwide. It delivers its products and services through a wide partner ecosystem including resellers, OEMs, and systems integrators.
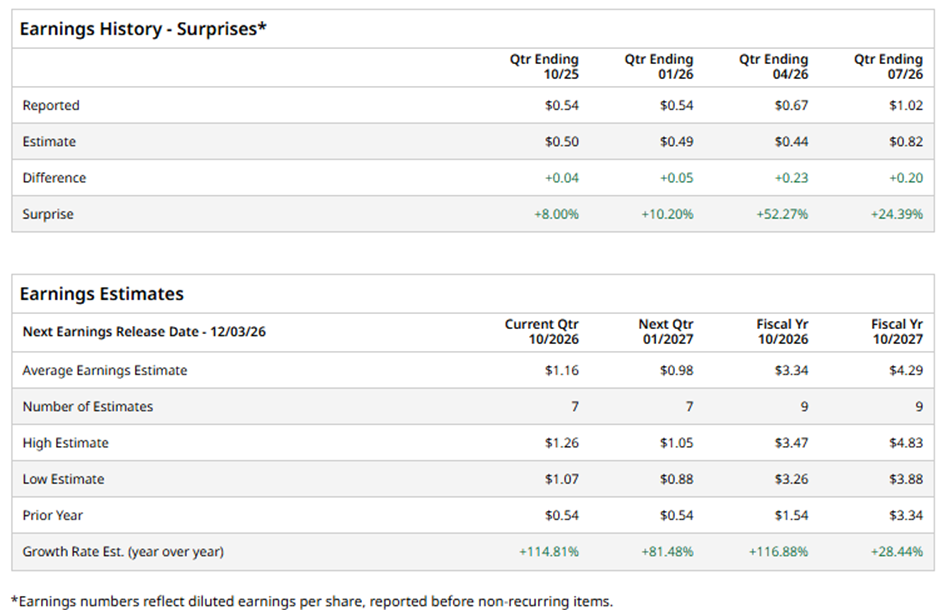
The Spring, Texas-based company is slated to announce its fiscal Q4 2026 results soon. Ahead of the release, analysts predict HPE to report EPS of $1.16, a 114.8% jump from $0.54 in the year-ago quarter. It has exceeded Wall Street's earnings expectations in each of the past four quarters.
For fiscal 2026, analysts expect the global technology company to post EPS of $3.34. a surge of 116.9% from $1.54 in fiscal 2025.
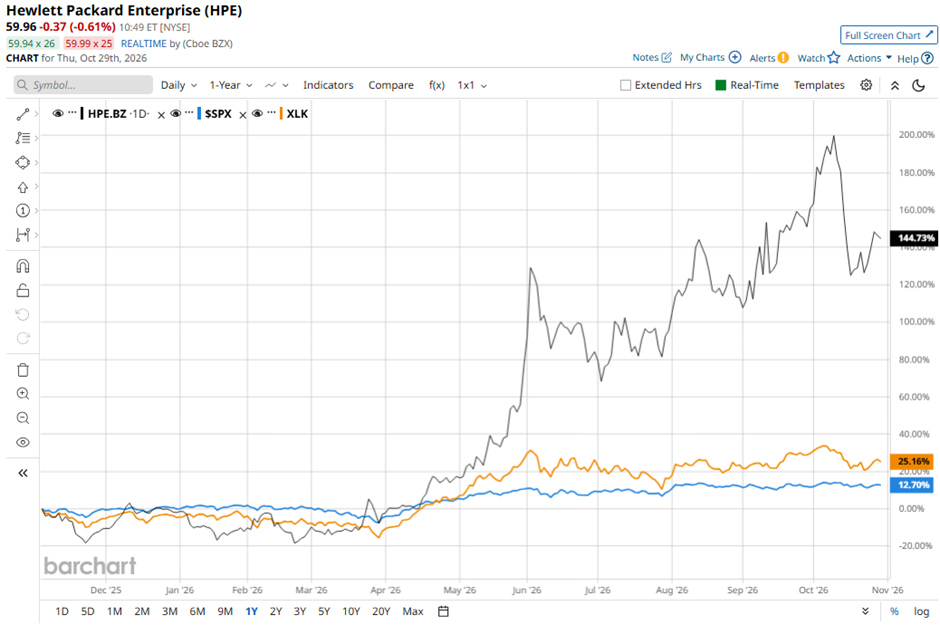
Shares of Hewlett Packard Enterprise Company have climbed 147.4% over the past 52 weeks, outpacing the broader S&P 500 Index's ($SPX) 11.9% gain and the State Street Technology Select Sector SPDR ETF's (XLK) 24.1% increase over the same period.
Hewlett Packard Enterprise shares rose 5% following its Q3 2026 results on Sept. 2, as revenue jumped 33.7% year over year to $12.21 billion and adjusted EPS of $1.11, both beating analysts’ estimate, driven by strong AI-related demand for servers and networking equipment. The company raised its fiscal 2026 revenue growth forecast to 34% - 37% and adjusted EPS guidance to $3.75 - $3.85 and upgraded fiscal 2027 revenue growth expectations to 13% - 17% and adjusted EPS growth to 16% - 20%.
However, persistent supply constraints involving memory, NAND, CPUs and drives remained a concern, despite inventory increasing to $11.82 billion and HPE’s expanded Oracle partnership to deploy Juniper Networking equipment across AI data centers reinforced expectations for continued AI-driven growth.
Analysts' consensus view on HPE stock remains cautiously optimistic, with a "Moderate Buy" rating overall. Out of 21 analysts covering the stock, 10 recommend a "Strong Buy," two "Moderate Buys," and nine "Holds." The average analyst price target is $73.21, indicating a potential upside of 22.1% from the current levels.
On the date of publication, Sohini Mondal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.