


EN
Dominion Energy (D) Stock Looks About Right Following Virginia Plant Approval
Dominion Energy has logged a strong few years in the market, which puts fresh focus on whether the current share price lines up with what its earnings can support. With regulatory decisions and grid investment plans in the spotlight, the question now is how much of that story is already reflected in the valuation.
- Over the past 3 years Dominion Energy has returned 84.1%, which makes the earnings behind that move central to any view of what the stock is worth today.
- Virginia’s approval of the planned 3,000 MW Cumberland gas-fired plant points to sizeable future capital spending that can shape earnings power, project timing and the pace at which cash flows may support the current market valuation.
- The analysts covering Dominion Energy have run their own numbers. See what analysts think Dominion Energy's shares could be worth.
For investors, the debate is whether Dominion Energy's earnings are strong and reliable enough to justify where the stock trades today.
If you are weighing Dominion Energy against other grid and power infrastructure opportunities, a focused screen of 43 power grid technology and infrastructure stocks may be useful.
Does Dominion Energy Look Fairly Valued on Earnings?
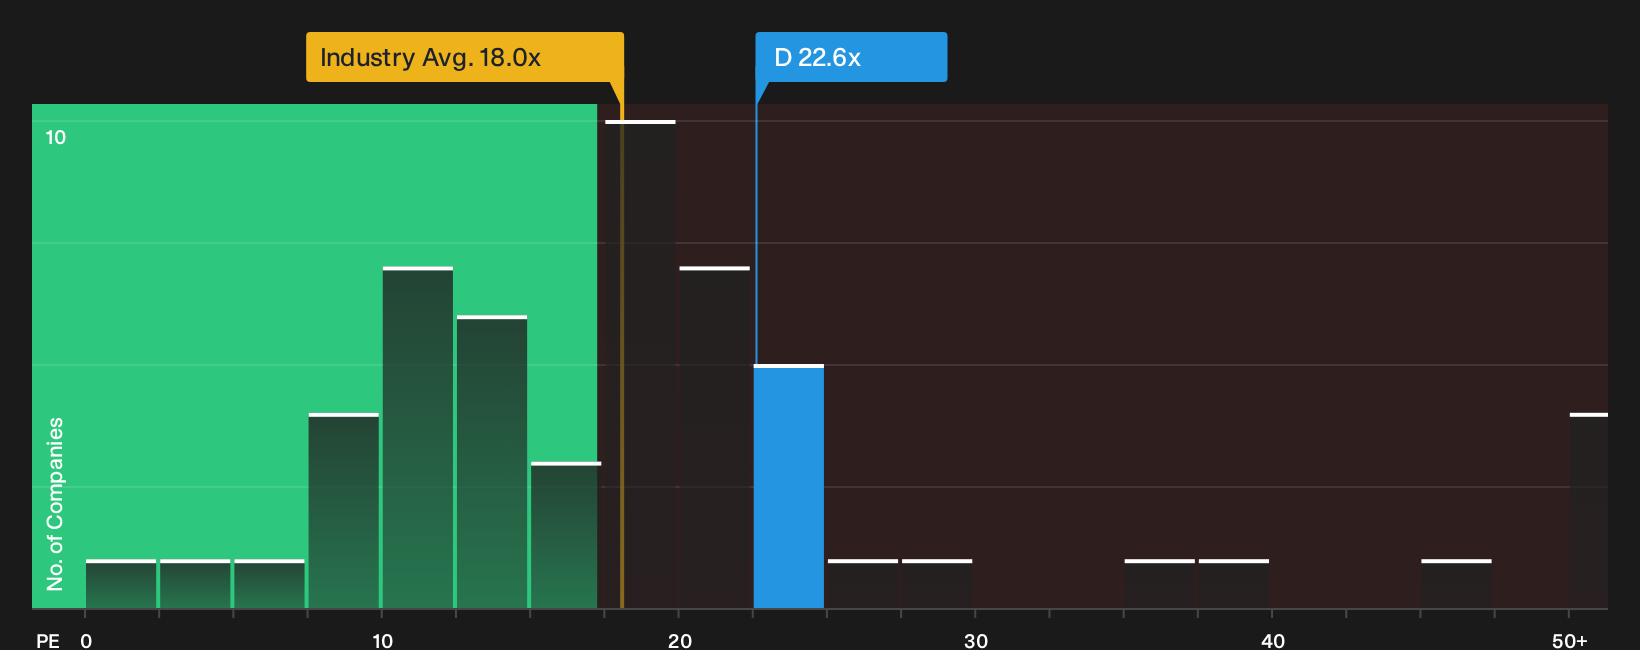
The P/E ratio suits Dominion Energy because earnings remain a central driver for a regulated utility that invests heavily and recoups those costs over time. On this basis, the stock trades on about 22.6x earnings, compared with roughly 20.7x for its closest peers and 18.0x across the wider integrated utilities industry, so investors are paying a higher price per dollar of profit than the sector average.
Virginia’s approval of the 3,000 MW Cumberland gas plant contributes to that premium because it highlights a large future build program that depends on regulators allowing adequate returns. At the same time, the current multiple sits close to what a tailored model suggests would be reasonable for Dominion Energy’s risk and earnings profile. Anyone evaluating the shares has to judge whether the regulatory path, capital plan and recent legal disputes over grid upgrades support that kind of earnings multiple over time. Explore the numbers behind Dominion Energy's P/E valuation.
The Dominion Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Dominion Energy's valuation puzzle leaves off by spelling out which future paths for earnings, margins and growth would need to hold for the stock to be worth meaningfully more or less than today’s price on the Community page. Rather than relying on a single P/E or model outcome, each narrative lays out the specific assumptions behind its view of fair value so you can compare them with results as they arrive.
One of the top community narratives on Dominion Energy: 8% undervalued
"The proposed all-stock merger with NextEra, together with Virginia moves to assign more grid costs directly to data centers and other large loads..."
Discover why this Narrative puts Dominion Energy at 8% undervalued.
One more piece of Dominion Energy's story before you decide
The next thing to check is how professional analysts see Dominion Energy a few years from now, and how those expectations stack up against the earnings multiple the market is already paying. Explore where analysts expect Dominion Energy to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com