


EN
Is W. P. Carey (WPC) Fairly Valued As Higher AFFO Guidance Lifts Confidence?
W. P. Carey (WPC) just posted third quarter 2026 results, pairing detailed earnings figures with a higher full year AFFO outlook and a lift in its quarterly dividend to US$0.950 per share.
Recent trading has been choppy for W. P. Carey, with the share price down about 15% over the past 90 days, while the 1 year total shareholder return is slightly positive at 0.6%. This suggests that short term momentum has cooled, even as longer term holders have still seen gains.
Scan beyond W. P. Carey and compare its latest move on guidance and dividends with our curated 6 dividend fortresses that are built around income resilience and balance sheet strength.
W. P. Carey is giving mixed signals, with higher AFFO guidance and a larger dividend set against a falling share price. Is this a sign of a weaker business, or simply a reset in sentiment as the valuation shifts?
Most Popular Narrative: 23% Overvalued
The prevailing view around W. P. Carey sets fair value at $51.35 against a last close of $63.08, so the narrative prices the stock above what underlying cash flows are judged to support. That gap frames the latest guidance upgrade and dividend bump as positives that still sit inside a valuation that, according to this framework, already bakes in plenty of optimism.
Price sits slightly above my fair value estimate, so the stock looks fairly priced rather than cheap. The ~5.95% gross yield is attractive for a diversified net-lease stock, but at this level the margin of safety is thin and the buy signal stays Risky. I'd rather wait for a pullback toward S1 or S2, where the risk/reward would improve. Until then, it stays on watch.
See why 1 investors see W. P. Carey as 23% overvalued.
Result: Fair Value of $51.35 (OVERVALUED)
Still, a sustained rise in financing costs or a hit to key tenant credit could quickly challenge the view that W. P. Carey is only modestly overvalued.
Find out about the key risks to this W. P. Carey narrative.
Another View: What The P/E Says About W. P. Carey
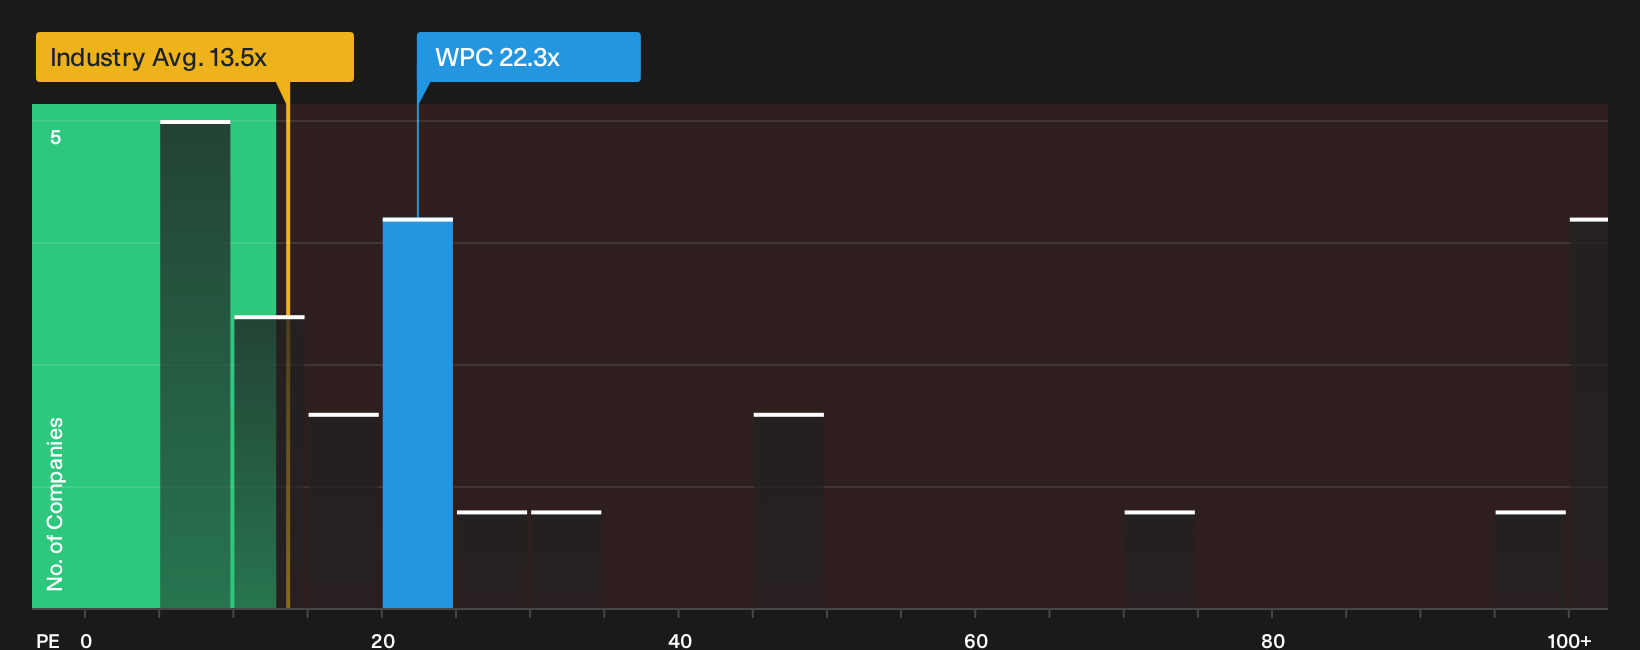
Multiples tell a different story for W. P. Carey. The stock trades on a 22.3x P/E, which looks cheap compared with peer companies on 73.4x, yet expensive compared with the broader Global REITs group on 13.6x. A fair ratio of 34.2x suggests the market could still shift. As an income investor, it comes down to which reference point you consider most relevant.
See what the numbers indicate about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages or clear opportunity? Put the new dividend, guidance shift and valuation metrics for W. P. Carey side by side, then weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond W. P. Carey?
If W. P. Carey has sharpened your focus on yield, valuation and risk, do not stop here. The next strong addition to your portfolio might already be on your screen.
- Target dependable income streams by scanning a curated set of high-yield opportunities through the 6 dividend fortresses.
- Hunt for mispriced quality by running a focused search across companies highlighted in the 26 high quality undervalued stocks.
- Zero in on financial resilience by checking out companies filtered for robust balance sheets via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com