


EN
Eli Lilly (LLY) Retatrutide Beat A Rival Drug In Phase 3 Trial
- Eli Lilly (NYSE: LLY) reported that retatrutide outperformed Novo Nordisk's Ozempic in a major Phase 3 diabetes trial.
- The business unveiled plans to combine U.S. and international units into Lilly Global Markets, with a target of full implementation by 2027.
- Management outlined a leadership transition tied to the new structure, with new executive appointments expected to take effect in 2027.
- The retatrutide Phase 3 result and Lilly Global Markets reorganization are part of wider shifts our research has identified for Eli Lilly. We have also spotted 1 warning sign worth knowing about at Eli Lilly.
For readers looking to broaden ideas around next generation healthcare technology, consider exploring 36 healthcare AI stocks.
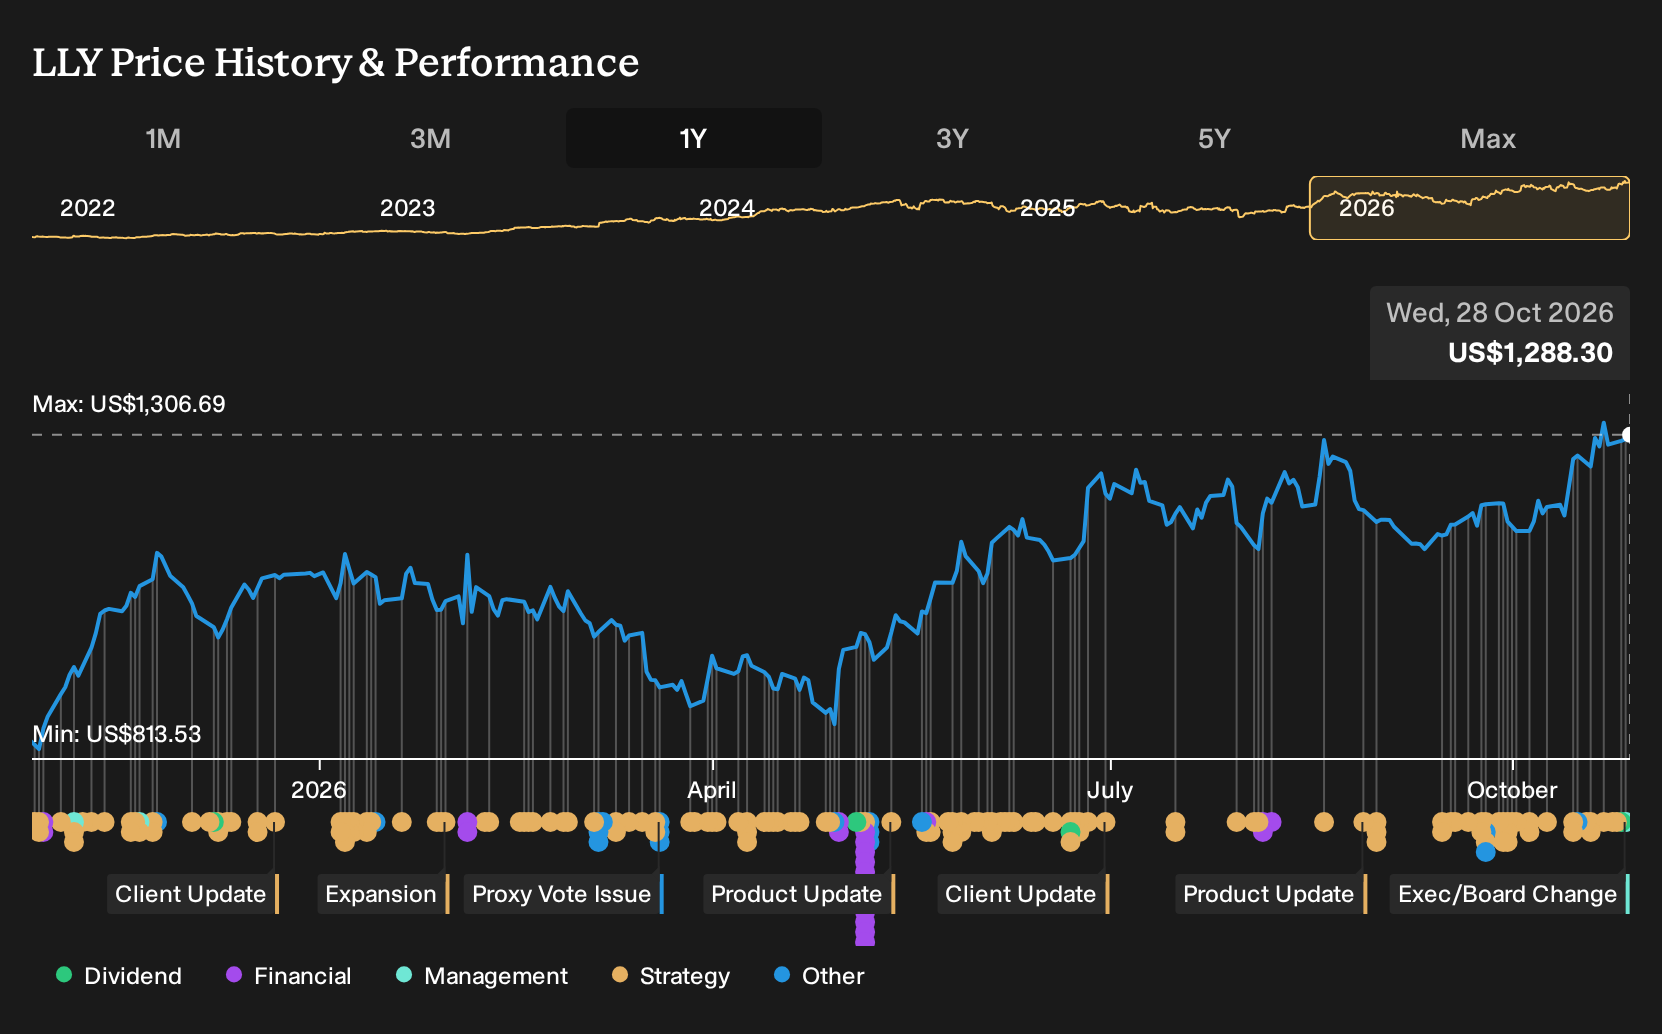
Eli Lilly is a large US pharmaceuticals group with a US$1.1b market cap that develops and sells human medicines across major markets including the United States, Europe, China and Japan. New late-stage diabetes drugs and global reorganization moves can influence how that pipeline reaches patients worldwide.
Retatrutide raises the bar while Eli Lilly rewires who runs the show
The Eli Lilly Narrative hinges on turning incretin science, manufacturing heft and global reach into durable earnings power, and this leadership reset lands right where those moving parts meet.
"The main thing that has to go right is that Eli Lilly continues to turn strong demand for GLP-1 and related cardiometabolic drugs into durable access and reimbursement, including through programs such as Medicare’s GLP-1 Bridge and expanding self-pay and employer channels, while managing pricing pressure and legal risks..."
See how the full story points towards a $1,329 fair value for Eli Lilly.
The retatrutide trial result directly supports the incretin-engine catalyst in that Narrative, while the new Lilly Global Markets structure and 2027 leadership slate test the execution layer that has to deliver access and reimbursement. A single commercial organisation under Ilya Yuffa is designed to link U.S. and international market decisions more tightly to that GLP-1 and cardiometabolic push against rivals such as Novo Nordisk and AstraZeneca.
The flip side is that this reorganisation leans into a model that is already carrying pricing pressure, high capital commitments and a flagged high debt load, so leadership cohesion and succession planning become part of the risk checklist rather than background detail. Retatrutide’s strong readout raises expectations on the pipeline, while the delayed 2027 leadership transition concentrates attention on whether the current team can hold guidance and legal exposure on track over the next year.
For you as an investor, the same news can either read as added conviction in an incretin-led expansion or as extra execution risk, depending which Eli Lilly Narrative you lean toward.
One more Eli Lilly question investors cannot ignore
Quarterly headlines only tell part of the story, because the longer term analyst models point to an end point for Eli Lilly that looks very different from today’s snapshot. See where analysts expect Eli Lilly to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com