


EN
ConocoPhillips (COP) Beat Q2 Estimates, Is The Stock Fully Valued?
ConocoPhillips (COP) is back in focus after a Q2 report that topped analyst revenue and earnings estimates, alongside fresh commentary on cash returns and possible asset sales in Norway and the U.K.
ConocoPhillips shares have built a strong run over 2026, with a 30 day share price return of 18.26% and a year to date share price gain of 54.15%. The 1 year total shareholder return of 74.57% and 5 year total shareholder return of 143.22% point to momentum that investors are still rewarding. Recent headlines around estimate revisions, the Q2 revenue beat and fresh commentary on cash returns and potential North Sea divestments appear to have reinforced confidence. This helps explain why the stock has pushed up to around $149 even as the broader oil and gas sector continues to digest mixed operating updates.
Compare ConocoPhillips’ momentum with other energy plays by scanning our hand picked 26 high quality undervalued stocks that also pair fundamentals with recent share price strength.
The recent surge in ConocoPhillips now raises a simple tension. Are investors responding to the Q2 beat, cash return plans and portfolio tweaks, or has sentiment just sprinted ahead of what the business itself justifies?
Most Popular Narrative: Fairly Valued
ConocoPhillips closed at $149.06, almost identical to the narrative fair value of $149.04 based on a 7.24% discount rate. This puts the current rally right in line with what this framework calls fair.
The company’s outlined path to a $7b free cash flow uplift by 2029, supported by lower free cash flow breakevens from the mid US$40s WTI range today to the low US$30s, indicates that margin expansion and higher earnings power are still ahead of what recent results fully capture.
See why 106 investors see ConocoPhillips as 0% overvalued.
Result: Fair Value of $149.04 (ABOUT RIGHT)
Still, large, long-life projects like Willow and Port Arthur LNG, along with higher capital needs in the Permian, could challenge the ConocoPhillips fair value story.
Find out about the key risks to this ConocoPhillips narrative.
Another View: ConocoPhillips Through The SWS DCF Lens
The narrative fair value puts ConocoPhillips roughly in line with the market price. The SWS DCF model tells a very different story, with an estimate of $364.98 per share versus the current $149.06. That is a large gap. Which view deserves more weight in your own work?
Look into how the SWS DCF model arrives at its fair value.
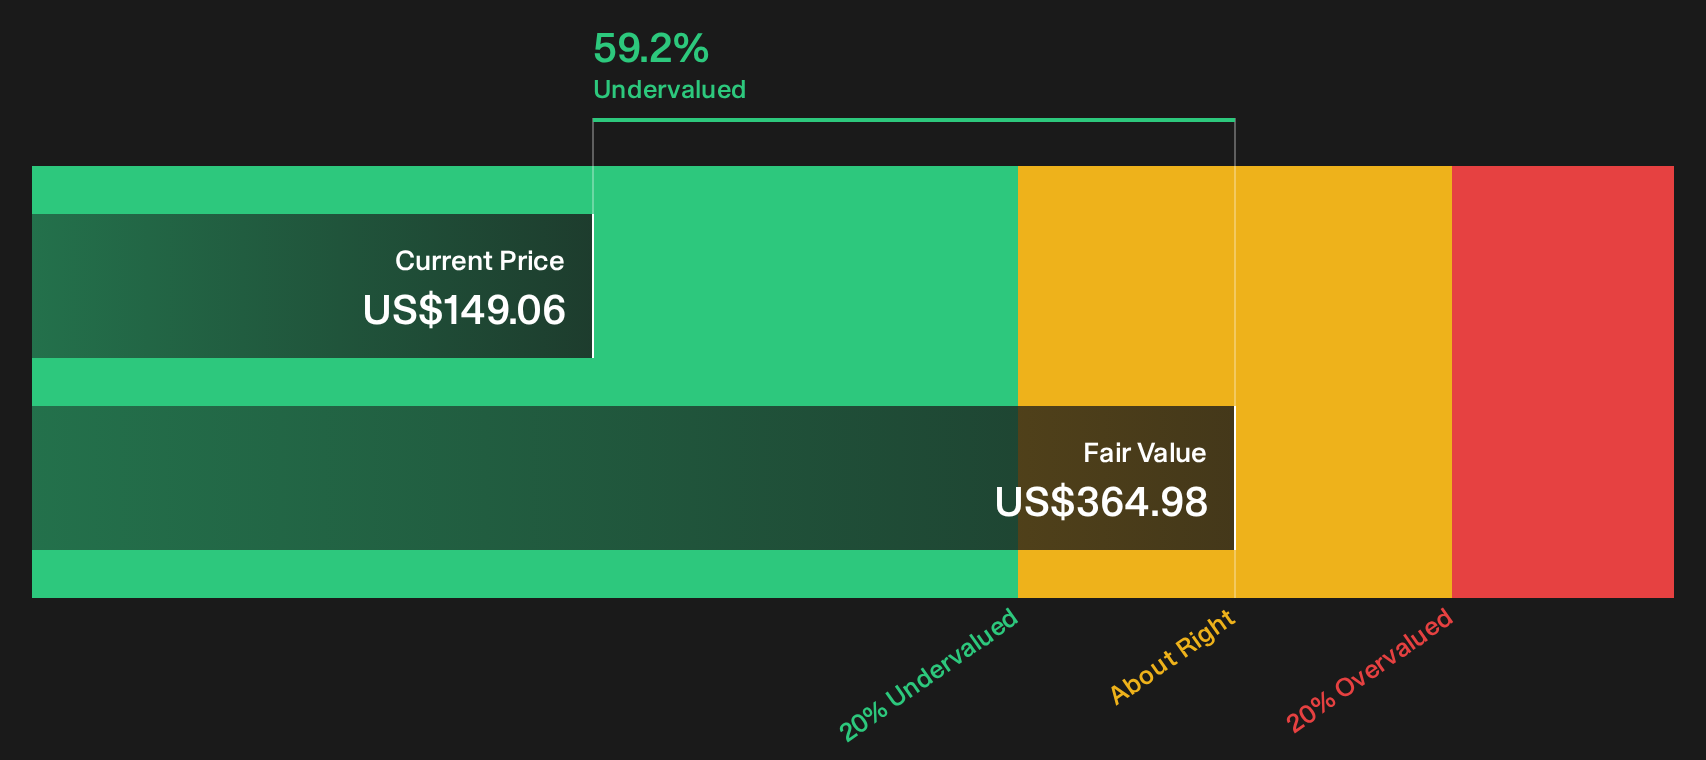
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ConocoPhillips for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on ConocoPhillips so far? Move fast, test the assumptions against your own thresholds, and pressure test both the upside and the risk signals through 1 key reward and 2 important warning signs
Looking for more ConocoPhillips sized investment ideas?
If ConocoPhillips has sharpened your focus, do not stop with a single ticker. Use the Simply Wall Street Screener to line up your next watchlist candidates before the crowd moves on.
- Target steady compounding potential by reviewing companies we flag as 32 resilient stocks with low risk scores that may help balance more volatile holdings.
- Hunt for quality at attractive prices by scanning our 26 high quality undervalued stocks that blend solid fundamentals with currently compressed valuations.
- Spot fresh opportunities early by checking the 19 high quality undiscovered gems before they gain wider market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com