


EN
Is Castle Biosciences (CSTL) Priced About Right After A 134% Rise?
Castle Biosciences has delivered a sharp share price rise over the past few years, and that kind of move naturally leads investors to ask whether the current US$36.68 price is supported by the company's sales. With the recent gains still fresh, the stock now invites a closer look at how much revenue is actually sitting behind each dollar of market value.
- The share price is up 133.6% over the past 3 years, which puts real weight on the question of whether the business's sales can bear that kind of re-rating.
- The company depends on commercial uptake of its diagnostic tests and disciplined cost control, so future expectations for sales growth and operating leverage can heavily influence how investors judge today's pricing.
- There is a second opinion on Castle Biosciences worth weighing. See what analysts think Castle Biosciences's shares could be worth.
The stock's next move may depend on whether the current market value looks sensible when lined up against Castle Biosciences' sales base.
If you want to stress test this same sales based valuation question beyond Castle Biosciences, widen the lens using 26 high quality undervalued stocks
Is Castle Biosciences Fairly Priced on Sales?
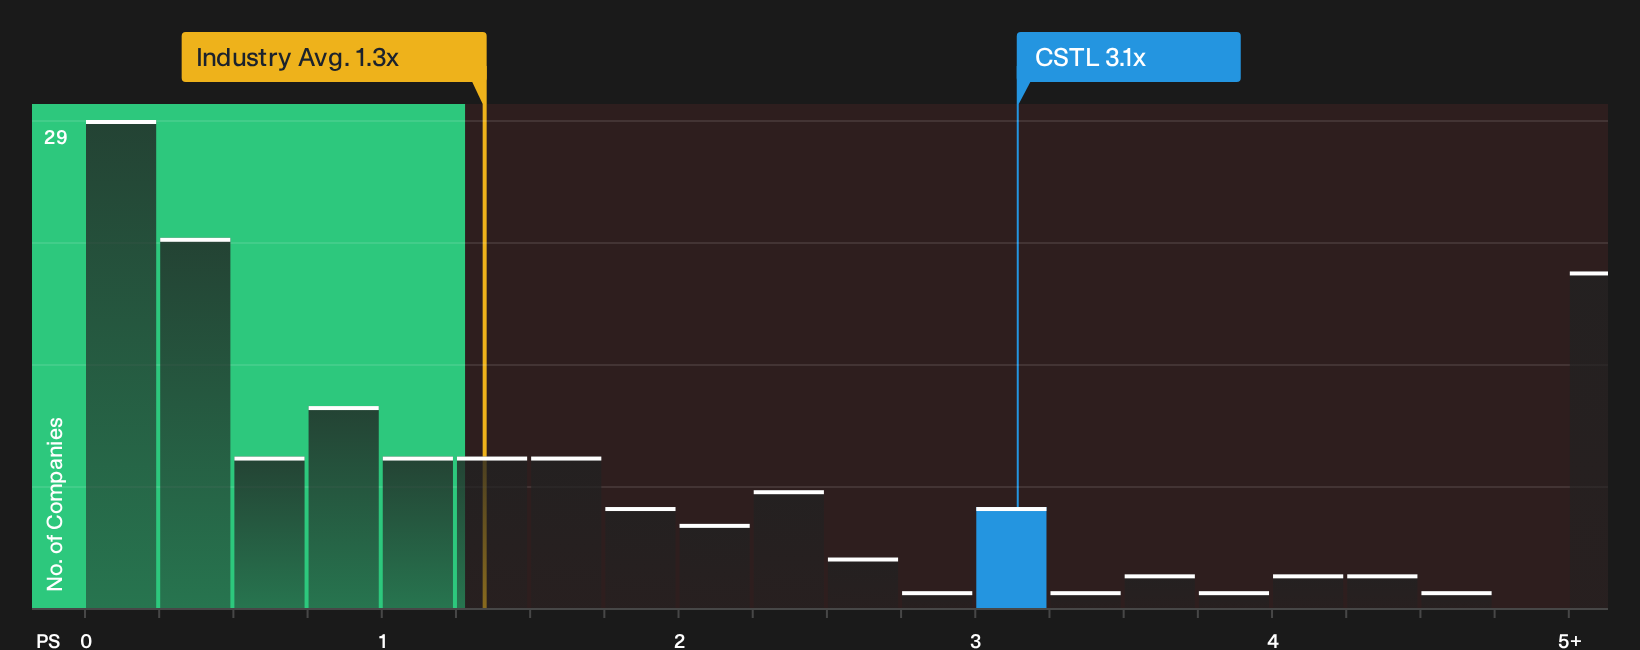
P/S fits Castle Biosciences because investors are effectively paying for the current and potential revenue from its diagnostic tests rather than established profits. From that perspective, the stock trades on a P/S of about 3.1x, compared with a Healthcare industry average of roughly 1.3x and a peer group closer to 1.0x, so each dollar of Castle Biosciences sales currently carries a higher price tag than many similar businesses.
The valuation model that blends the company’s growth profile, margins, size and risk suggests a P/S level close to where Castle Biosciences trades today, so the current multiple sits near the range this framework would expect. For you as a shareholder or prospective investor, the key question is whether the quality and durability of those revenues justify paying roughly three times sales instead of a level nearer peers, or whether that premium would only make sense if the business can keep scaling its test portfolio and cost base efficiently. Explore the numbers behind Castle Biosciences's P/S valuation.
The Castle Biosciences Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Castle Biosciences valuation puzzle leaves off by spelling out which assumptions on growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it does today, all housed on the Community page. Each narrative presents fair value as a clear, testable idea about how Castle Biosciences' business might develop so you can see how that view holds up over time.
Community views on Castle Biosciences split between those who see underappreciated execution upside and others who think expectations already look full.
Bull case: 19% undervalued
"Castle Biosciences is expanding its test menu into underpenetrated indications such as Barrett’s esophagus and atopic dermatitis, with TissueCypher volumes rising 63% to 14,988 reports in Q2 2026..."
Discover why this Narrative puts Castle Biosciences at 19% undervalued.
Bear case: roughly fairly valued
"While Castle Biosciences is lifting revenue and test volumes across its portfolio, operating expenses including cost of sales moved from US$90.4 million in Q2 2025 to US$106.6 million in Q2 2026..."
Explore why this Narrative puts Castle Biosciences at roughly fairly valued.
For Castle Biosciences, who is steering the ship, and on what terms?
Before you stop at the share price and P/S multiple, it is worth asking who is actually making the key calls at Castle Biosciences and how those leaders are rewarded for the outcomes you care about. See who runs Castle Biosciences and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com