


EN
Butterfly Network (BFLY) Could Be 32% Undervalued As Guidance Rises And Margins Improve
Butterfly Network (BFLY) just posted third quarter results that topped its own revenue expectations, delivered its highest gross margin to date, raised full year guidance, and secured FedRAMP authorization alongside a new Embedded partner launch.
Butterfly Network’s recent update landed after a powerful run, with the share price still at US$7.81 and a year to date share price return of 108.27%. Short term momentum has cooled, as the 30 day share price return fell 14.64% and the 90 day share price return dipped 4.41%, while the 1 year total shareholder return of 263.26% and a very large 3 year total shareholder return of about 9x suggest expectations around the story have already shifted meaningfully.
Scan for other healthcare and medtech stories with similar momentum by reviewing the hand picked 36 healthcare AI stocks that echo Butterfly Network’s latest progress.
After a move this sharp and a business still reporting losses of US$74.85 million on US$112.144 million of revenue, does Butterfly Network still offer a favourable trade off between upside potential and downside risk at US$7.81?
Most Popular Narrative: 31.5% Undervalued
Butterfly Network’s most followed narrative pegs fair value at $11.40, comfortably above the recent $7.81 close. This frames the upbeat reaction to its Q3 update as part of a broader thesis built around ultrasound on chip and licensing potential.
The shift from a handheld point of care focus toward a chip licensing platform is seen as opening up additional revenue streams and creating room for more partners over time. This supports higher growth assumptions in some models. Some research highlights that Butterfly Network is not viewed as tied to a single commercial relationship. Bullish analysts expect more key partners to emerge, which they see as important for both scale and diversification.
See why 38 investors see Butterfly Network as 31% undervalued.
Result: Fair Value of $11.40 (UNDERVALUED)
Still, if enterprise deals take longer to close or HomeCare and international projects stall, the bullish Butterfly Network licensing thesis could quickly lose momentum.
Find out about the key risks to this Butterfly Network narrative.
Another View: What Multiples Say About Butterfly Network
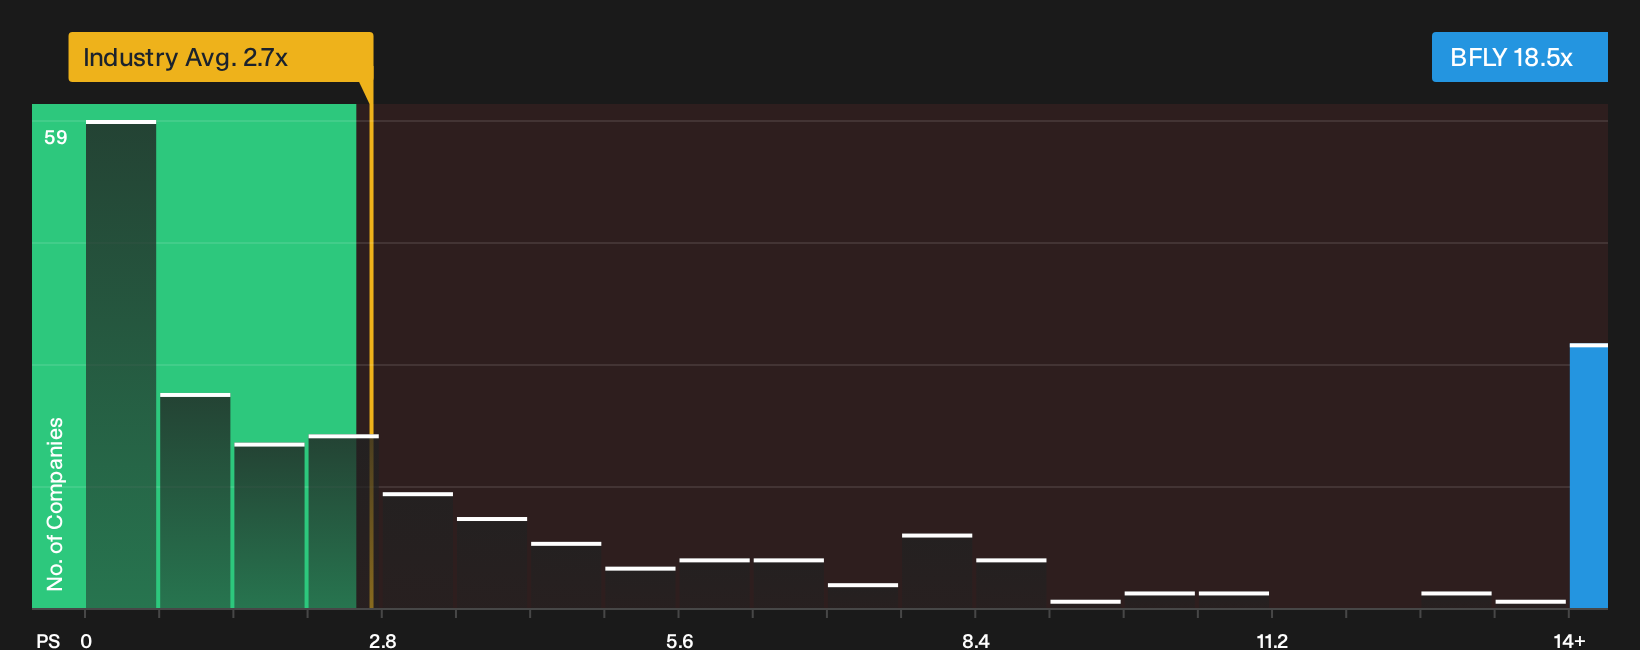
Analyst narratives sketch Butterfly Network as undervalued, yet the current P/S ratio of 18.5x tells a tougher story. That level is far above the US Medical Equipment group on 2.7x, peers at 3.5x, and even the fair ratio of 4.1x that the market could move towards over time.
If sentiment cools or expectations reset, a shift closer to that fair ratio would mean a much lower implied sales multiple. This raises the question of how much valuation risk investors are really comfortable carrying at US$7.81.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Butterfly Network is clearly split. Move quickly, review the data for yourself, then weigh up the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Butterfly Network?
If Butterfly Network has sharpened your curiosity, do not stop here. Use the Simply Wall Street Screener to hunt for fresh opportunities before others spot them.
- Target potential mispricing by reviewing the 26 high quality undervalued stocks, which combine quality fundamentals with room for sentiment to shift.
- Prioritise resilience by scanning the 32 resilient stocks with low risk scores, which pair steadier risk profiles with more durable balance sheets and cash positions.
- Get early to lesser known stories by tracking the 19 high quality undiscovered gems, which larger investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com