


EN
Missed Silvercorp Metals' Run? What Buyers Had To Believe
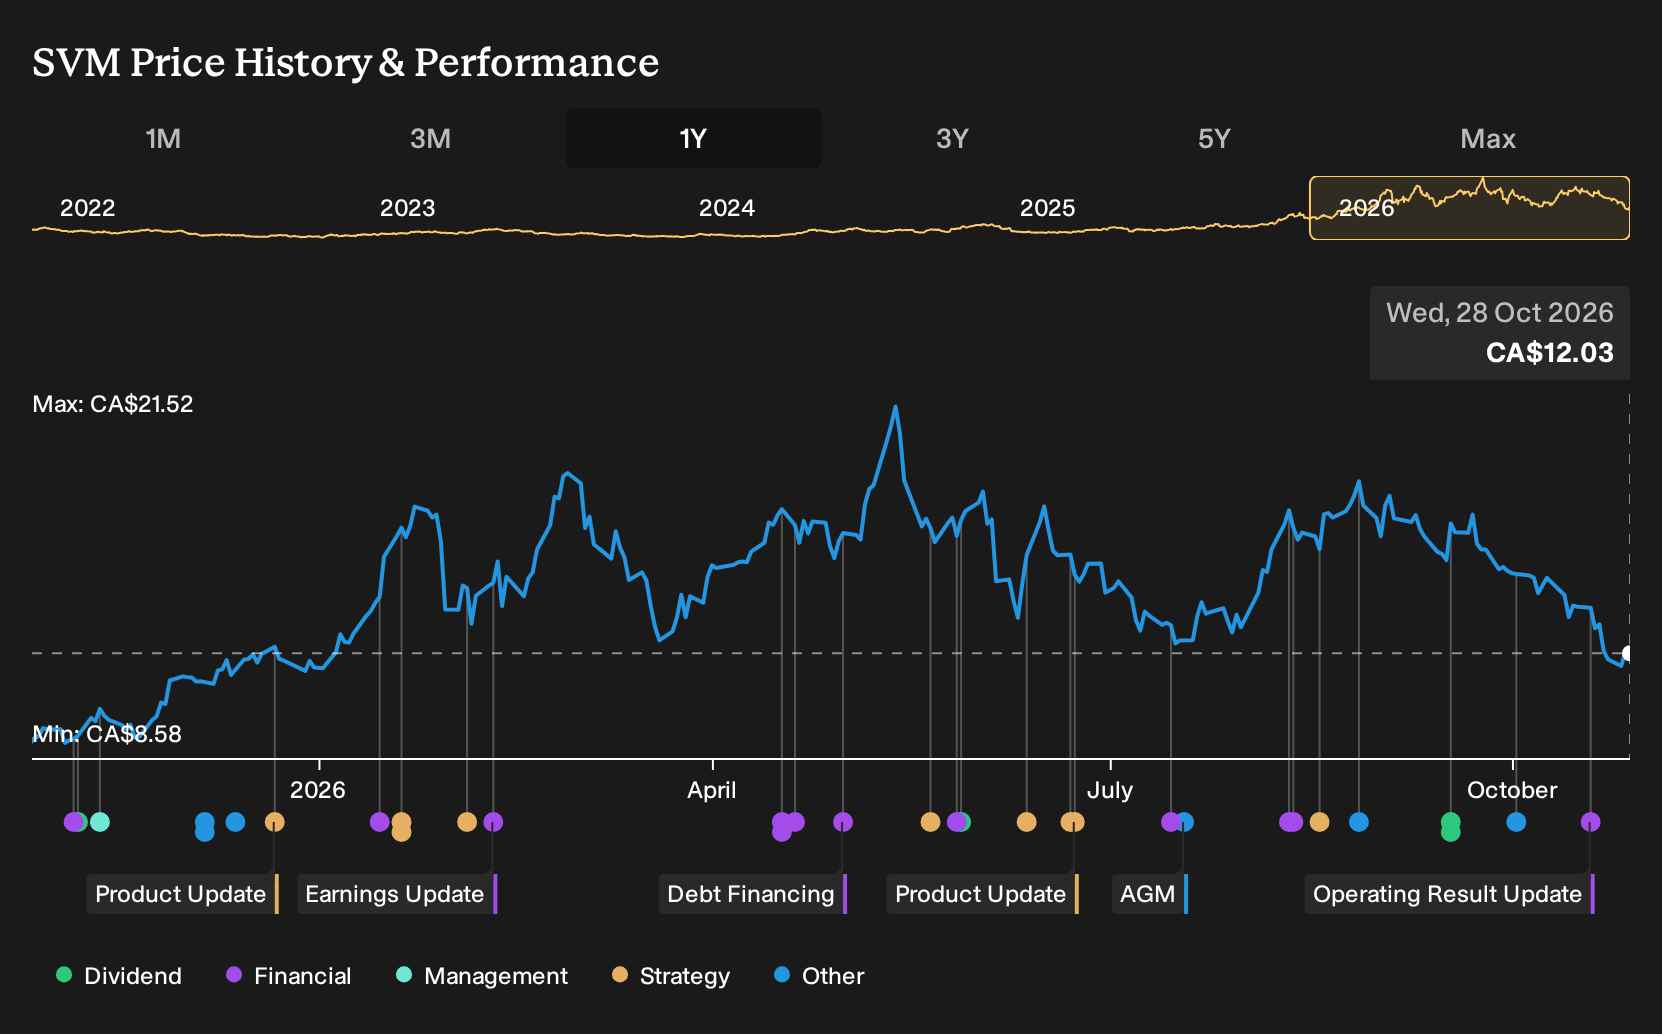
If Silvercorp Metals was on your watchlist instead of in your portfolio, the recent payoff may feel uncomfortable. For Silvercorp Metals shareholders, the return over the past year was 36.5%, including dividends. That outcome invites a blunt question. Back on 28 October 2025, when bulls talked about leverage to higher silver prices and a 5-year path to CA$28.58 at $100/oz silver, what business evidence, if any, really supported that high-price silver assumption?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
This theme extends beyond Silvercorp Metals. See which of 10 top silver producer stocks may still merit a closer look.
The Argument You Would Have Been Weighing On Silvercorp Metals
The shares cost CA$8.76 at the start of the period, and investors in Silvercorp Metals were choosing between two very different stories.
The bullish narrative pointed to a fair value of CA$28.58, hinging on silver reaching $100/oz, revenue growth of 91.6%, a 23.1% profit margin, and a future P/E of 12.2x over a 5-year span.
The bearish view suggested fair value closer to CA$7.47, stressing China concentration, rising production costs, and ESG and permitting risks for projects such as El Domo in Ecuador.
What The Results Changed For The Silvercorp Metals Story
The biggest new fact for Silvercorp Metals was Q1 2027, when revenue reached US$138.7m and net income excluding extra items was US$59.4m. That lifted net margin to 42.8% from 22.3% a year earlier. Profitability at that level gave fresh support to the optimistic narrative, although China focused risks and project execution questions meant the evidence still cut both ways.
The lesson is simple. When a thesis leans on margin expansion, track the reported net margin and absolute profit each quarter to see if the story is turning into cash or just staying in the model.
What Silvercorp Metals Buyers Are Paying For Now
Silvercorp Metals now trades at CA$12.03, with the current Narrative arguing that Fair Value sits above that level. The focus is on whether new gold projects and extra silver output can meaningfully change how concentrated the business is.
Anyone paying today is really judging whether Silvercorp Metals can maintain strong cash generation while expanding into Kyrgyzstan and Ecuador without eroding returns.
"Silvercorp is positioned to benefit from global growth in demand for silver, driven by the ongoing transition toward renewables and electrification (notably solar, EVs, and battery storage). This trend may support higher realized prices and revenue growth, especially given that 66% of its Q1 revenue was generated from silver."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking One Step Beyond Silvercorp Metals
Silvercorp Metals shows how established mines can look when a thesis connects with real operations. You might now wonder where fresh deposits are still being outlined.
One early stage explorer is advancing a large gold project that also includes copper. It is replacing older technical work with newer drilling and a modern report.
The aim is clear and focused. Transform a rough historical estimate into something compliant, detailed and easier to compare.
If that process alters the resource quality or overall scale, your watchlist could eventually feature a very different kind of precious metals story beside Silvercorp Metals.
That argument has a Narrative and a number behind it. → See the company one Narrative values 194% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com