


EN
Sterling Infrastructure (STRL) Stock Still Looks Undervalued As Record Results Reset Views
Sterling Infrastructure has been on a powerful multi year run, and after a sharp recent pullback, the question is how firmly its current share price rests on its earnings power. With fresh headlines highlighting record results and a richer outlook, the valuation debate has shifted squarely to what investors are paying for the company’s profit stream today.
- Over the past 5 years, Sterling Infrastructure has delivered a very large total return. This now puts a lot of pressure on the earnings story to justify that kind of share price reset.
- Recent record results and a larger expected revenue base, driven in part by the E Infrastructure Solutions and CEC electrical operations, can support a higher level of earnings. This matters directly for how rich or restrained an earnings based multiple might look.
- The analysts covering Sterling Infrastructure have run their own numbers. See what analysts think Sterling Infrastructure's shares could be worth.
The stock’s next move may depend on whether Sterling Infrastructure’s current market price lines up with what its latest earnings can reasonably support.
If you want a wider starting point for research around the kind of earnings story Sterling Infrastructure is wrestling with today, filter for stocks using the 26 high quality undervalued stocks.
Is Sterling Infrastructure Still Cheap on Earnings?
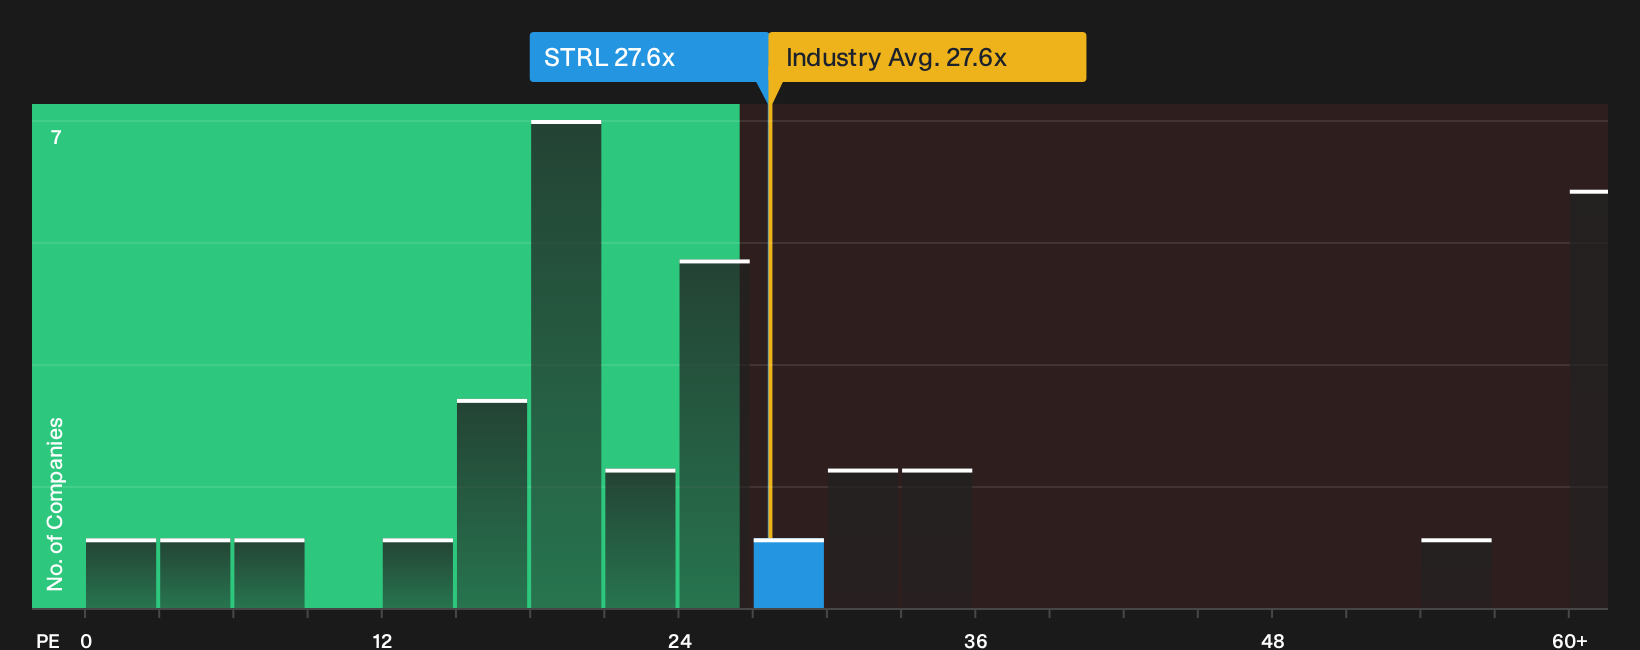
P/E is a useful lens for Sterling Infrastructure because investors are focused on how much they are paying for each dollar of its reported earnings. On this measure, Sterling trades on a P/E of 27.6x, which is almost identical to the wider construction industry on 27.6x, yet sits above the peer group average of 21.7x. That mix suggests the market is valuing the stock more in line with a broad sector basket than with closer competitors.
Because the latest record Q3 2026 results and raised guidance have reset expectations higher, the gap to the peer average hints that investors are already paying up for Sterling Infrastructure’s current earnings profile. The Fair Ratio model, which factors in the company’s margins, growth assumptions, size and risks, points to a higher P/E than where the shares trade today, so the current tag screens as undervalued on this framework. Despite the strong headlines around guidance, the existing multiple still comes through as lower than this tailored benchmark, leaving room for readers to decide whether that discount fairly reflects execution risk or looks overly cautious. Explore the numbers behind Sterling Infrastructure's P/E valuation.
The Sterling Infrastructure Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Sterling Infrastructure pick up where the P/E puzzle leaves off. They set out the specific earnings, growth and margin paths that would need to play out for the stock to look materially higher or lower than today’s price. Each scenario ties its number to a clear view on how Sterling Infrastructure's growth, profitability and risk profile might evolve, giving you a reference point you can revisit as fresh information comes through.
One of the top community narratives on Sterling Infrastructure: 54% undervalued
"The main thing that has to go right is Sterling Infrastructure continuing to add skilled labor and equipment fast enough to execute its E-Infrastructure backlog…"
Discover why this Narrative puts Sterling Infrastructure at 54% undervalued.
One more side of Sterling Infrastructure that deserves your attention
Sterling Infrastructure’s valuation story is only part of the picture, because internal checks have also flagged areas of concern that careful shareholders may want to weigh for themselves. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com