


EN
Wise Group (WSE), Why Is Its Latest Update Drawing Fresh Attention?
Wise Group (WSE) moved into the spotlight after issuing fresh guidance for Fiscal Year 2027, indicating net revenue growth in the upper half of its 15% to 20% range and an EBIT margin outlook near 23%.
Recent guidance landed against a weaker tape for Wise Group, with the share price down 9.1% over the past three months and year to date, and the 1 year total shareholder return declining 17.4%. However, the 3 year total shareholder return remains positive, indicating longer term momentum that has cooled in 2026.
Scan how Wise Group compares with other high-growth financial platforms by reviewing curated opportunities in the 26 high quality undervalued stocks that are already showing solid fundamentals and room for a rerating.
Wise Group now sits at the crossroads between a share price that has already cooled and guidance that still points to solid ambition. Has most of the rerating already happened, or does the current valuation leave meaningful upside on the table?
Most Popular Narrative: 36% Undervalued
Against a last close of $10.91, the most followed narrative for Wise Group points to a fair value of about $16.94, which implies a sizeable valuation gap that hinges on how its payments ecosystem scales over time.
Growing use of Wise Accounts, Wise cards and Wise Assets by 19 million active customers, together with a larger share of non cross border revenue, increases the scope for broader fee based income and can support net revenue and earnings.
See why 4 investors see Wise Group as 36% undervalued.
Result: Fair Value of $16.94 (UNDERVALUED)
Still, the Wise Group story can break if planned price cuts outpace efficiency gains, or if interest income from US$39b of customer balances weakens.
Find out about the key risks to this Wise Group narrative.
Another View: What Multiples Say About Wise Group
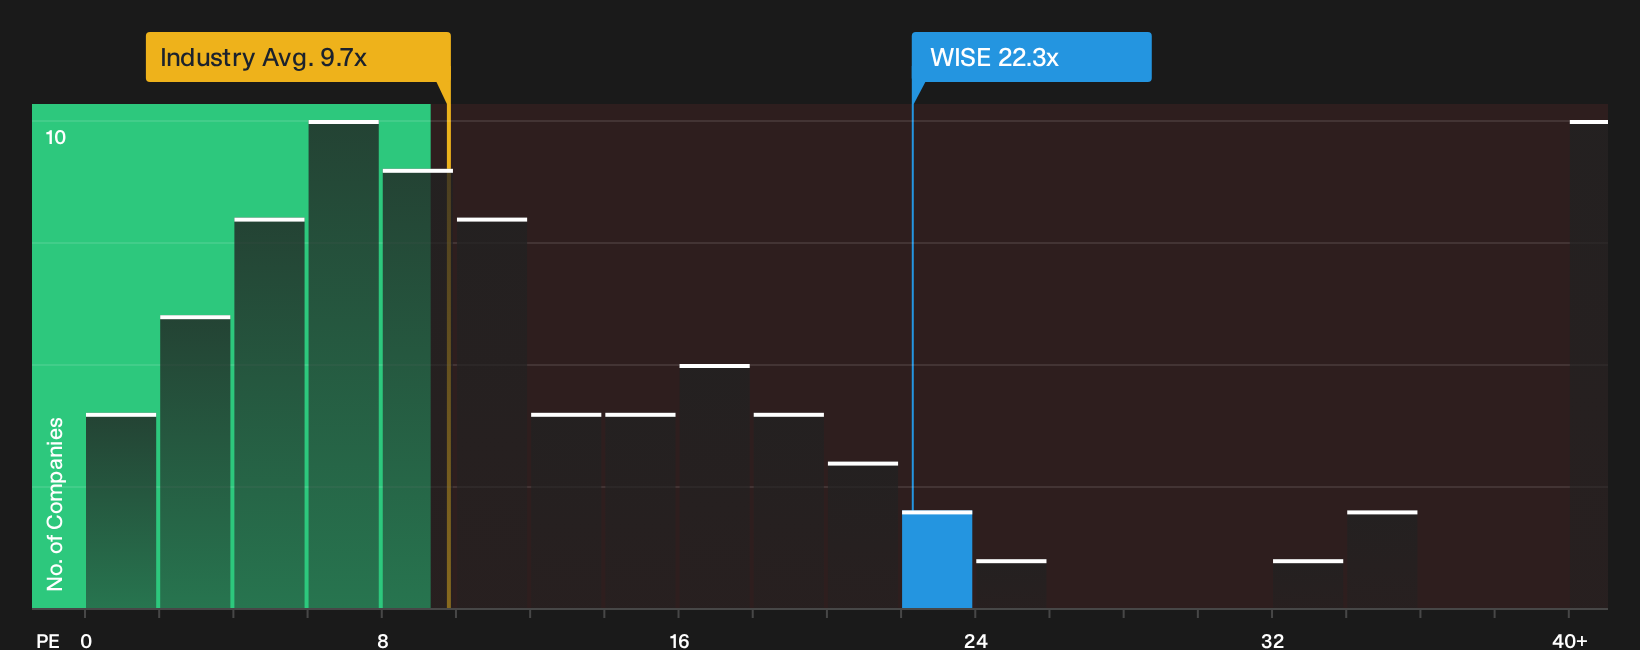
Analyst narratives paint Wise Group as materially undervalued, yet the current P/E of 22.4x sits above both the US Diversified Financial industry at 17.2x and the fair ratio of 15x. That gap suggests investors are already paying a premium. Is that margin of safety as wide as it looks?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The debate around Wise Group's value is clear enough. The key question is what you make of the numbers in front of you and how quickly you act on them. To see what optimistic investors are focusing on, review the 3 key rewards.
Looking for more investment ideas beyond Wise Group?
Wise Group may be front of mind today, but you do not want to overlook other opportunities that could fit your goals just as well.
- Target potential upside in smaller companies that already show financial strength by scanning the 9 elite penny stocks with strong financials.
- Spot opportunities where quality and valuation align by reviewing the 19 high quality undiscovered gems before others catch on.
- Guard your portfolio with candidates that prioritise resilience by filtering for the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com