


EN
Universal Display (OLED) Stock Stays Fully Priced After Strong Q3 Earnings
Universal Display has enjoyed a bounce in recent weeks after a tough few years, which puts fresh focus on whether the current share price is adequately supported by its earnings power. With the stock recovering from a long period of weaker returns, the key issue is how the latest business progress feeds into what investors are really paying for today.
- Over the past 5 years the stock has fallen 48.0%, which puts long term holders squarely focused on whether the present valuation now lines up with the earnings profile.
- Recent advances in OLED technology and commercial milestones in areas like automotive lighting can influence expectations for future profitability and the timing of cash generation that underpins any earnings based valuation.
- The analysts covering Universal Display have run their own numbers. See what analysts think Universal Display's shares could be worth.
For investors, the debate is whether Universal Display's current market price is justified by the earnings it is generating today and is expected to produce in the future.
If you are weighing Universal Display against other earnings focused stories in semiconductors and related tech, it can help to compare it with companies in 26 high quality undervalued stocks.
Where Does Universal Display Sit on Earnings?
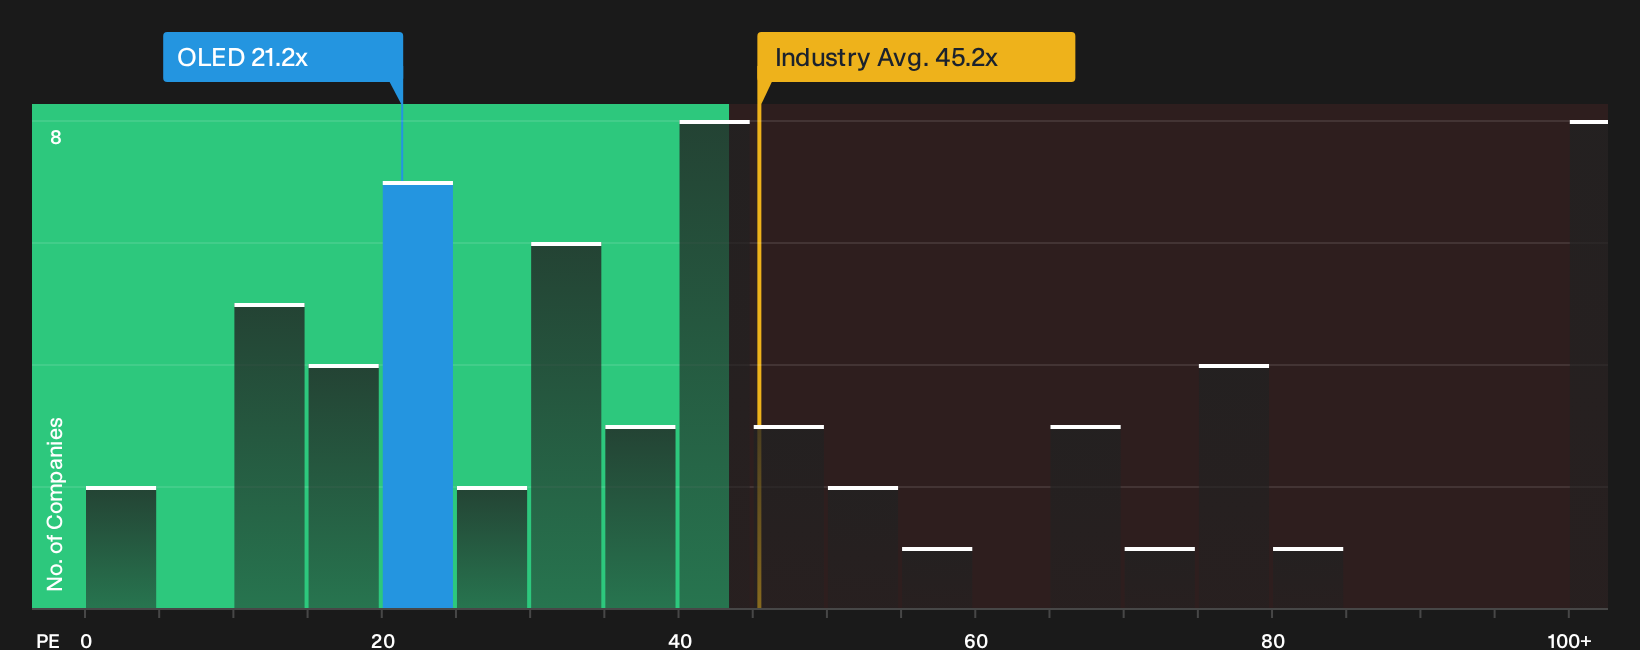
The P/E ratio is a useful lens for Universal Display because earnings are a key way investors track progress in commercialising its OLED portfolio. The stock currently trades on about 21.2x earnings, which sits well below the wider semiconductor industry average of roughly 45.2x and also under the peer group on about 48.8x. On this simple comparison, the market is attaching a lower earnings multiple to Universal Display than many chip related companies.
The fair value framework that blends factors like profitability, scale and risk suggests a P/E level for Universal Display that is close to where the shares trade, so the current multiple screens about right on that tailored yardstick. Because the latest earnings beat in Q3 2026 came alongside a reaffirmed revenue outlook rather than a step change, the valuation still leaves the stock priced at a discount to many peers on headline P/E multiples. Explore the numbers behind Universal Display's P/E valuation.
The Universal Display Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Universal Display and turn it into concrete scenarios that spell out what kind of growth, margins and earnings profile would need to play out for the stock to be worth materially more or less than it is today, and they sit on the platform's Community page. Each narrative ties a fair value estimate to a specific mix of potential catalysts and risks so you can track over time which version of Universal Display's story appears to be unfolding.
Community views on Universal Display are split between a long runway for OLED adoption and concern that execution and customer timing keep the brakes on.
Bull case: 22% undervalued
"The still early stages of OLED adoption in laptops, monitors and automotive displays, with OLED smartphone penetration around 65% compared with about 5% in IT and roughly 1% in automotive, leave a long runway for Universal Display’s materials and licenses to expand into new devices and vehicle platforms and potentially broaden the revenue base beyond handsets…"
Discover why this Narrative puts Universal Display at 22% undervalued.
Bear case: 27% overvalued
"Uneven ordering patterns like the recent pull-ins and timing shifts may continue to cause volatility in quarterly revenue and limit near term earnings visibility…"
Explore why this Narrative puts Universal Display at 27% overvalued.
Universal Display’s valuation still leaves one crucial angle unresolved
Numbers only tell part of Universal Display’s story, because the people setting priorities, taking capital allocation calls and agreeing their own pay packages can tilt long term outcomes in quiet but powerful ways. See who runs Universal Display and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com