


EN
Entegris (ENTG) Stock Looks Expensive As Supply Chain Constraints Persist
Entegris has delivered strong multi year gains, and the question now is whether the current share price can still be grounded in what the business earns. Recent swings around supply chain headlines keep pulling the quote around, while the underlying earnings power is what ultimately needs to carry that valuation.
- Over the past 3 years Entegris has returned 81.3%, which puts real weight on whether the recent price level is adequately supported by its earnings profile.
- Fresh concerns about component shortages and cleanroom constraints suggest some cash flows could arrive later than previously expected, which can matter a lot when you are assessing what investors are paying for each dollar of profit.
- Your read on Entegris is one view; the desks covering it have another. See what analysts think Entegris's shares could be worth.
The issue now is whether Entegris's current market value is reasonable once you line it up against the earnings that support it.
If you want a clearer sense of how Entegris compares in terms of earnings power and supply chain pressure, it can help to line it up against 54 AI infrastructure stocks.
Is Entegris Getting Expensive on Earnings?
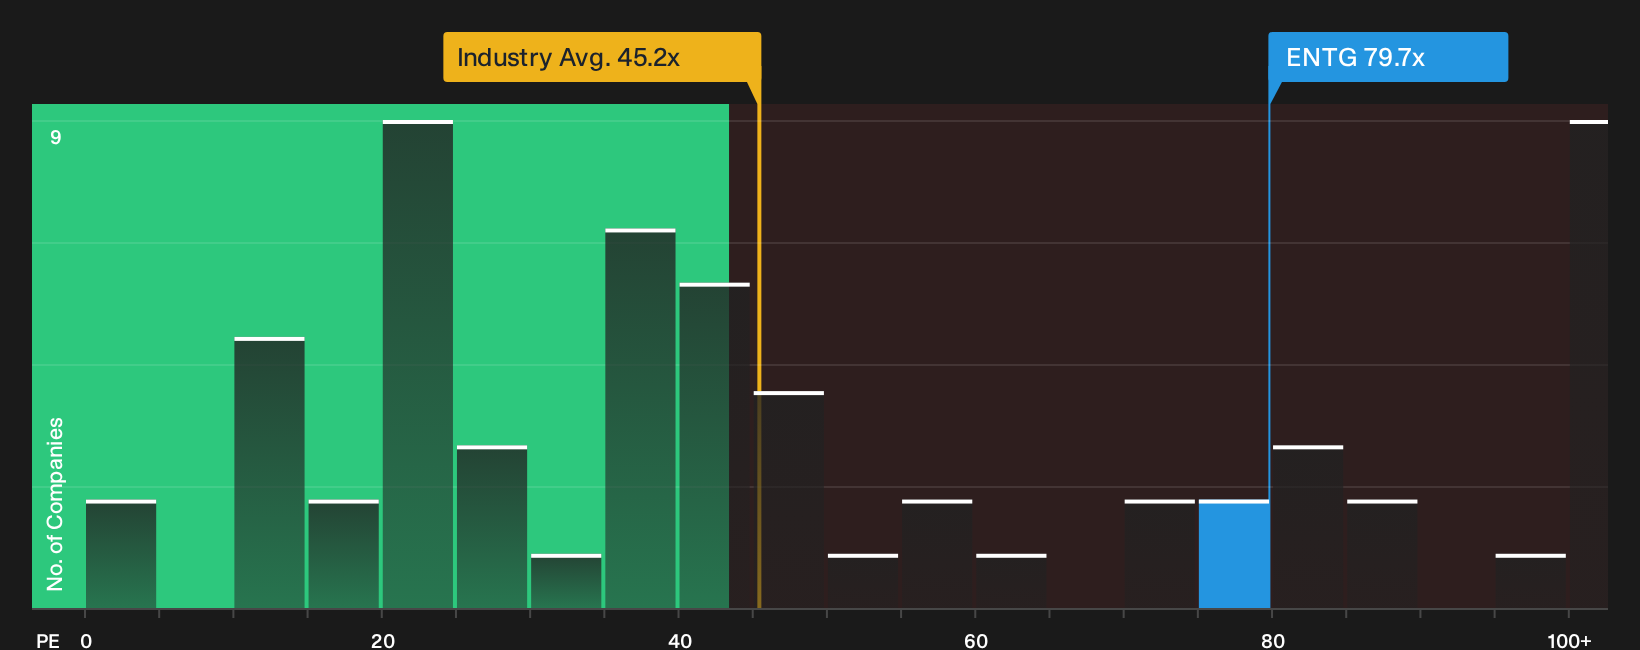
The P/E ratio tends to suit Entegris because investors often anchor semiconductor valuations to current and expected earnings power. Right now the stock trades on roughly 79.7x earnings, which is far above the broader semiconductor sector average of about 45.2x and above the peer group near 44.8x. That is a rich price for each dollar of profit today, so you need to be comfortable that Entegris can justify paying such a premium for its earnings stream.
Fresh warnings about extended supply chain and cleanroom bottlenecks into 2027 mean some investors may question paying this kind of multiple despite the recent share price pullback. On the model that adjusts for Entegris's growth profile, margins, size and risk, the current P/E still sits well above the level that framework would point to, which screens the stock as overvalued on this metric. Anyone considering the shares needs to weigh whether the business quality and long term earnings prospects warrant paying such a premium multiple relative to both the industry and a more tailored fair value yardstick. Explore the numbers behind Entegris's P/E valuation.
The Entegris Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Entegris pick up where the P/E puzzle leaves off and explain which paths for growth, margins and earnings would need to occur for the stock to appear meaningfully cheaper or more expensive than today's quote on the Community page. Rather than relying on a single multiple or one model output, each narrative sets out the key assumptions behind its view of fair value so you can track those against Entegris' future results as they are reported.
Community views on Entegris split between those who see AI driven demand and deleveraging still giving the stock room to run, and those who think that promise is already fully reflected in the price.
Bull case: 11% undervalued
"Rising AI related demand for advanced logic, HBM, DRAM and higher layer NAND is increasing Entegris’ materials and filtration content per wafer…"
Discover why this Narrative puts Entegris at 11% undervalued.
Bear case: 21% overvalued
"Although Entegris cites rising content per wafer at advanced nodes tied to AI workloads, the company has reported essentially flat revenue over the last two years…"
Explore why this Narrative puts Entegris at 21% overvalued.
One more piece of the Entegris puzzle before you move on
Before you act on where Entegris trades today, it helps to see how professional analysts currently map out its revenue, earnings and cash flow a few years down the road. Explore where analysts expect Entegris to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com