


EN
3 Undervalued Small Caps With Insider Buying Across Regions
Over the last 7 days, the United States market has remained flat, yet it has experienced a 10.0% rise over the past year with earnings projected to grow by 17% annually in the coming years. In this context, identifying small-cap stocks that exhibit potential for growth and have insider buying activity can be an intriguing opportunity for investors seeking to navigate these dynamic market conditions.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Financial Institutions | 9.9x | 3.3x | 22.95% | ★★★★★☆ |
| Regional Management | 6.6x | 0.5x | 29.57% | ★★★★★☆ |
| Enovis | NA | 0.6x | 36.48% | ★★★★★☆ |
| Bank of the James Financial Group | 11.5x | 2.6x | 22.54% | ★★★★☆☆ |
| Union Bankshares | 9.4x | 2.0x | 25.98% | ★★★★☆☆ |
| German American Bancorp | 12.6x | 4.8x | 41.59% | ★★★☆☆☆ |
| Tennant | 61.6x | 0.9x | 20.84% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.6x | 2.6x | 6.97% | ★★★☆☆☆ |
| Peoples Financial | 29.2x | 4.0x | 32.60% | ★★★☆☆☆ |
| Chain Bridge Bancorp | 12.5x | 5.1x | 46.53% | ★★★☆☆☆ |
We'll examine a selection from our screener results.
Capital Southwest (CSWC)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Capital Southwest is a business development company focused on providing financing solutions to middle-market companies, with a market capitalization of approximately $0.57 billion.
Operations: The company's revenue is primarily derived from investments, with a gross profit margin consistently at 100%. Operating expenses have shown variation over time, reaching $28.51 million in the latest period. Net income margins have fluctuated, with the most recent figure at 46.15%.
PE: 13.4x
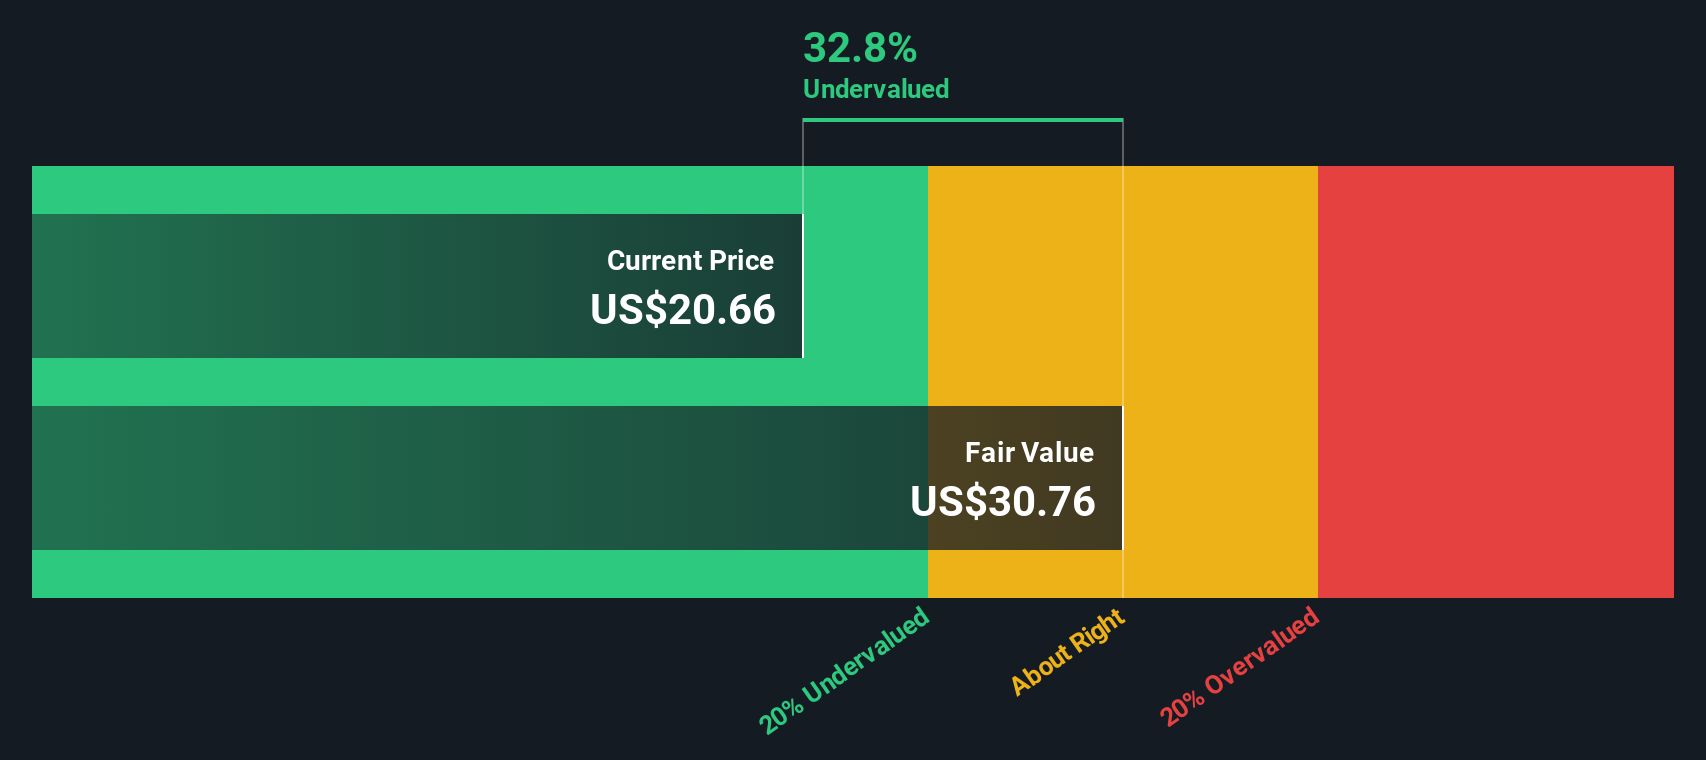
Capital Southwest, a smaller player in the U.S. investment landscape, showcases potential through strategic financial maneuvers and insider confidence. Recent insider purchases reflect trust in its growth trajectory. The company has bolstered its financial position with an increased SBA leverage commitment from $175 million to $250 million as of September 2026, enhancing capital deployment capabilities. Despite being dropped from the NASDAQ Composite Index in August 2026, it continues to pursue lower middle market opportunities with a focus on sustainable earnings growth projected at 22.8% annually.
- Click to explore a detailed breakdown of our findings in Capital Southwest's valuation report.
Assess Capital Southwest's past performance with our detailed historical performance reports.
GrafTech International (EAF)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: GrafTech International is a manufacturer of graphite electrode products used in the production of electric arc furnace steel, with a market capitalization of approximately $1.19 billion.
Operations: GrafTech International's revenue primarily comes from its Industrial Materials segment, with recent figures showing $509.08 million. The company has experienced fluctuations in its net income margin, with a notable decline to -38.43% as of the latest period. Operating expenses and non-operating expenses have consistently impacted profitability, contributing to these variations in net income margins over time.
PE: -1.7x
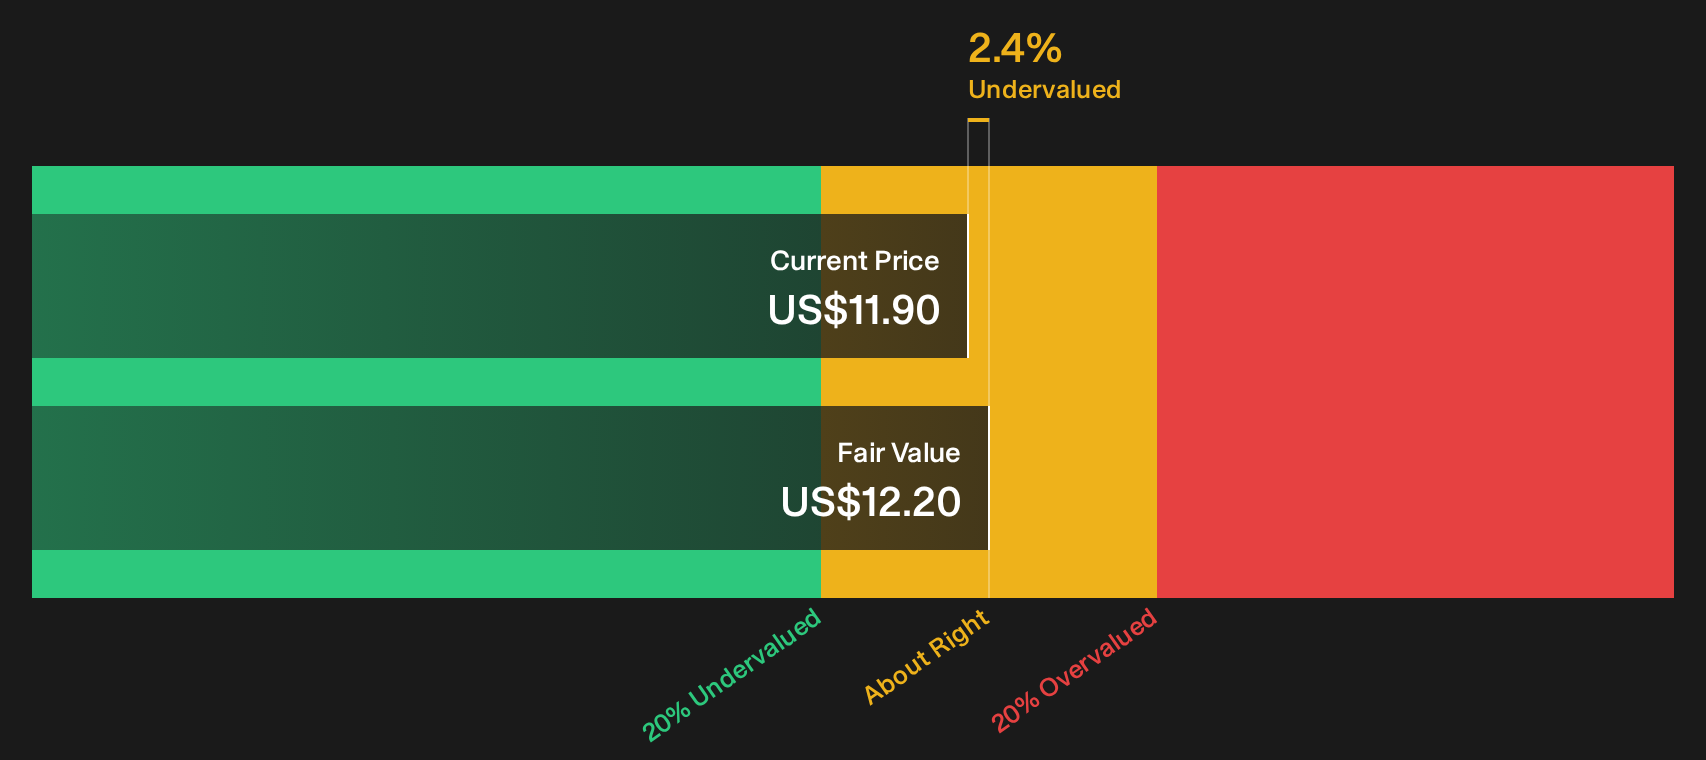
GrafTech International, a smaller company in the graphite electrode industry, recently reported increased production volumes but faced a net loss of US$46.77 million for Q3 2026. Despite these challenges, their strategic collaboration with Antora Energy to develop carbon-based materials for thermal batteries could diversify revenue streams and enhance domestic manufacturing. Insider confidence is evident as insiders have been buying shares since early 2026. The planned closure of their Monterrey facility aims to optimize operations and reduce costs, potentially improving long-term financial health.
- Navigate through the intricacies of GrafTech International with our comprehensive valuation report here.
Explore historical data to track GrafTech International's performance over time in our Past section.
Chiron Real Estate (XRN)
Simply Wall St Value Rating: ★★★★★☆
Overview: Chiron Real Estate focuses on investing in medical properties and has a market capitalization of $2.75 billion.
Operations: The company's revenue is primarily derived from investing in medical properties, with the latest reported revenue at $153.35 million. The gross profit margin has reached 100% in recent periods, indicating that there are no costs of goods sold impacting the gross profit. Operating expenses and non-operating expenses significantly affect net income, which has shown variability over time.
PE: 7.8x
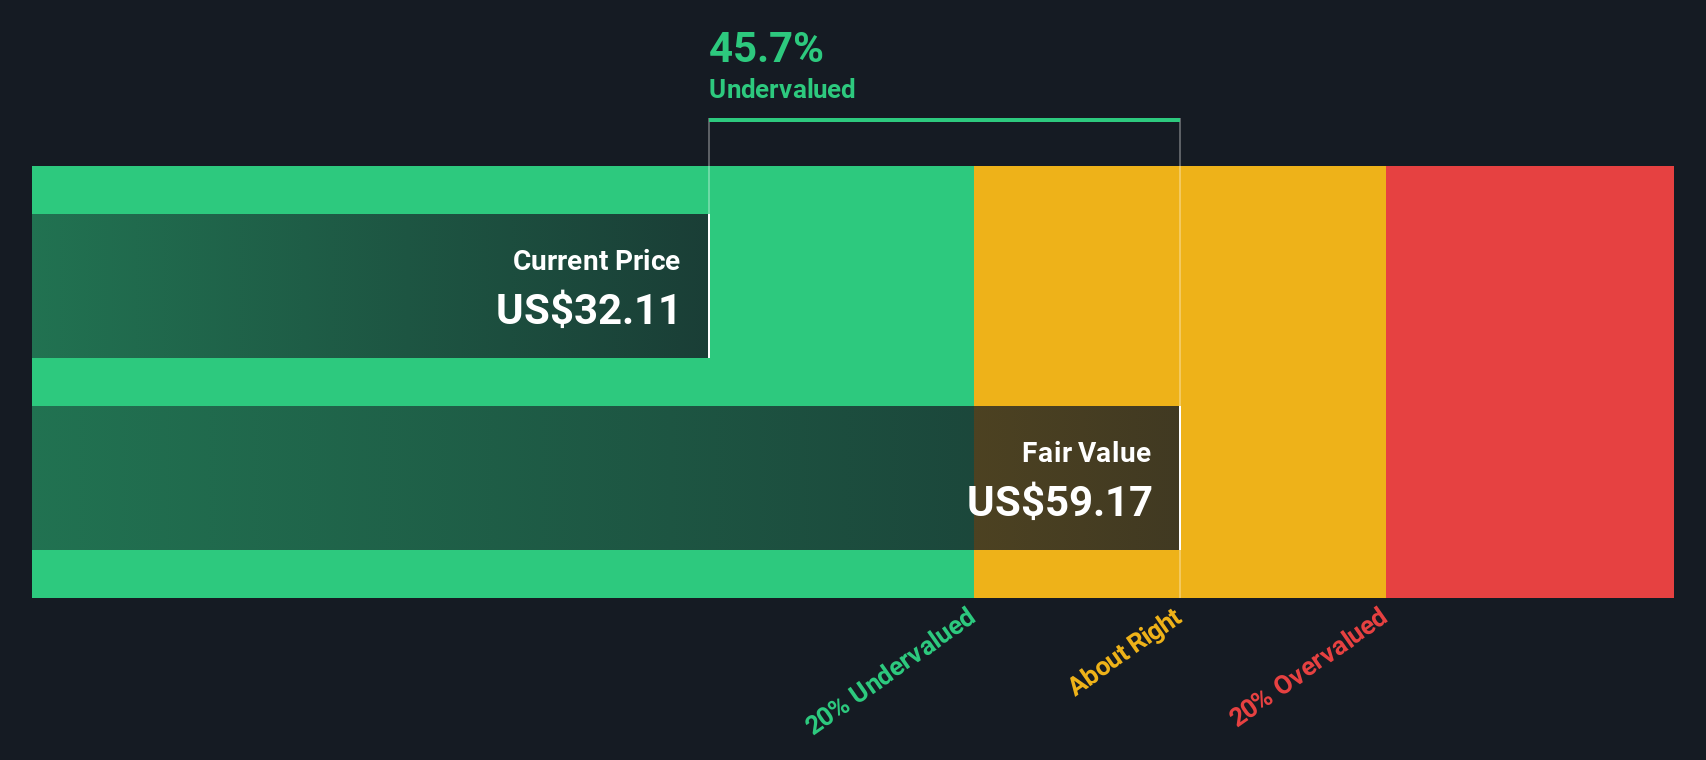
Chiron Real Estate, a smaller company in the U.S. market, recently appointed Charles P. Fitzgerald as Chairman, signaling potential strategic shifts with his extensive real estate investment background. Despite a challenging funding structure reliant on external borrowing and anticipated earnings decline of 125.2% annually over three years, Chiron's recent financials show strong net income growth to US$66.27 million for Q2 2026 from US$0.655 million the previous year, highlighting its potential amidst current undervaluation concerns.
Next Steps
- Click this link to deep-dive into the 64 companies within our Undervalued US Small Caps With Insider Buying screener.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com