


EN
Learn Why The Bull Case For SEEK (ASX:SEK) Could Change Following Growth Fund Reset
- SEEK held a shareholder and analyst call in October 2026 to explain revised arrangements for the SEEK Growth Fund’s second five year phase, which begins on 1 November 2026 and has already been approved by unitholders.
- The new framework for the SEEK Growth Fund’s Stage 2 matters because it reshapes how capital, risk and potential liquidity from fund assets interact with SEEK’s core employment marketplace economics.
- We will look at how SEEK's investment narrative intersects with the refreshed Growth Fund Stage 2 structure that management detailed.
Compare how SEEK’s refreshed Growth Fund structure stacks up against other capital allocation stories by scanning our curated list of 15 high quality undiscovered gems.
SEEK Investment Narrative Recap
To own SEEK, you really need to back the idea that its online employment marketplaces and AI driven matching can keep lifting paid ad yields while cost growth stays in check. The call on the refreshed Growth Fund structure sits around that story rather than inside it. The main near term swing factor still looks like execution on pricing, product and engagement across ANZ and Asia.
The biggest operational risk remains that management’s targets for at least 10% annual paid ad yield growth and cost growth capped at mid single digits prove too tight. The Growth Fund’s revised Stage 2 settings matter mainly if portfolio valuation pressure repeats, which could keep statutory earnings disconnected from what the operating businesses are doing.
For this Growth Fund update, the most relevant prior disclosure is management’s framework for Core and Non Core fund assets and the intention to deliver more than A$840 million of liquidity before any carried interest. That sits alongside A$166 million already returned and more than A$1b of potential near term asset sales flagged previously.
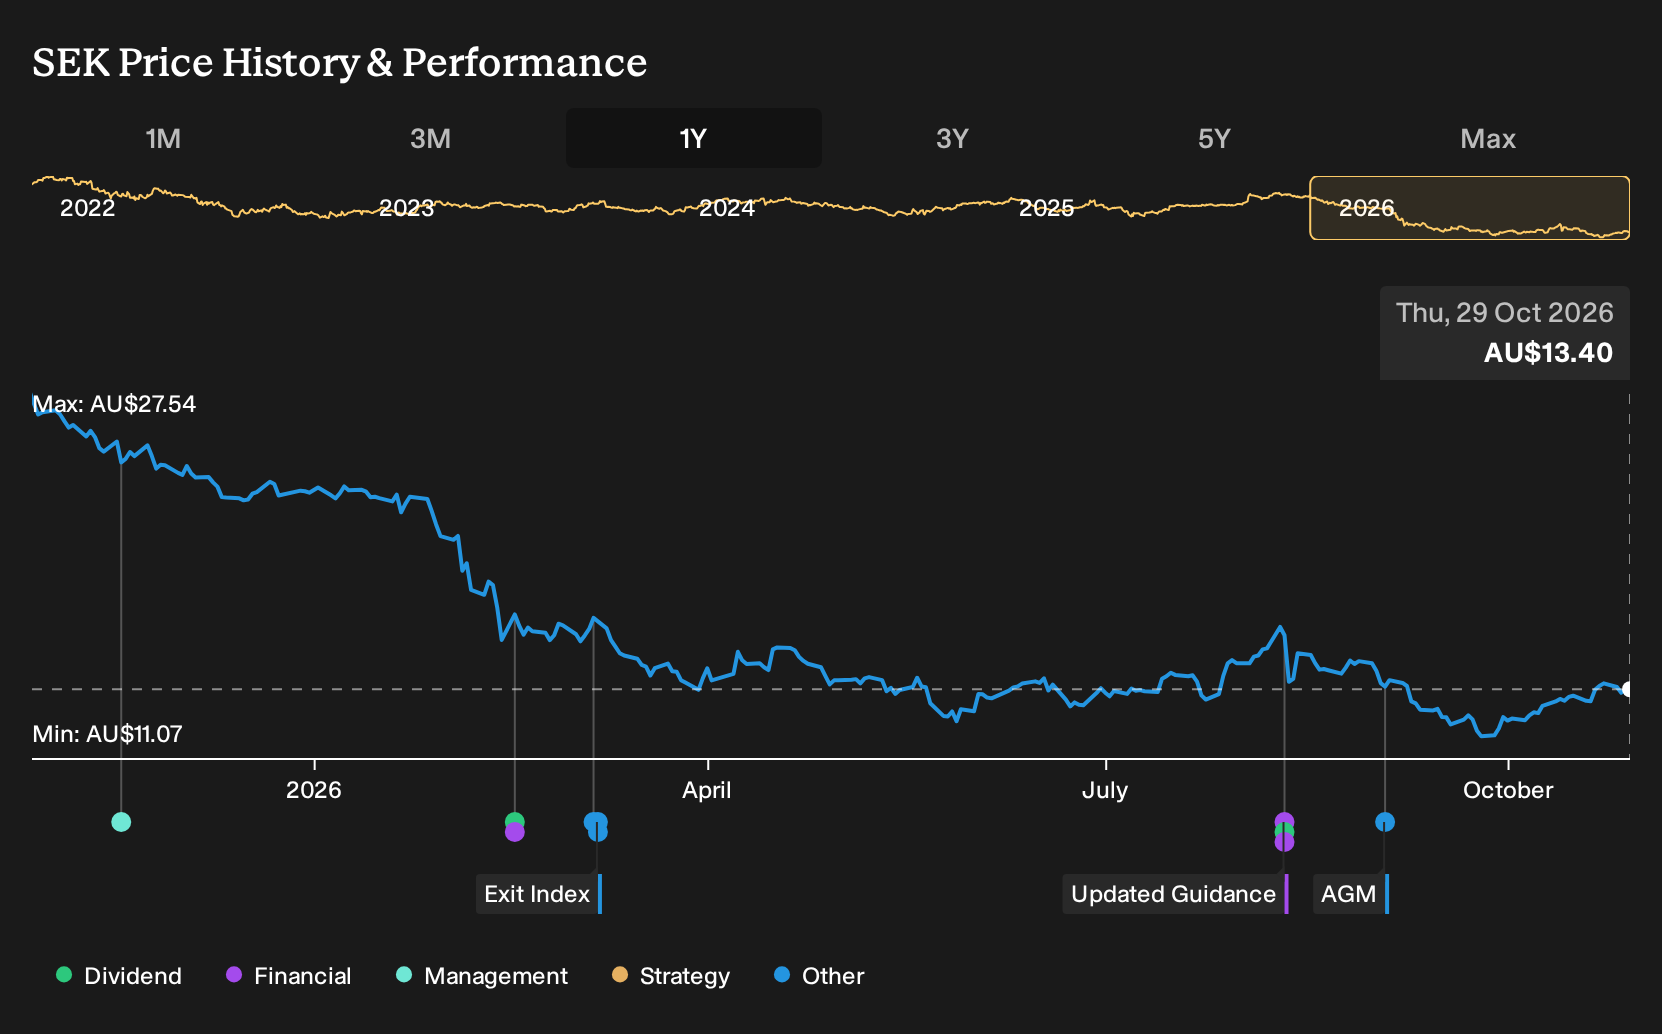
If SEEK executes on that plan, you are looking at a clearer separation between marketplace performance and non operating valuation noise, plus more cash that can support free cash flow metrics. The flip side is that any further write downs on Zhaopin or other fund holdings, after the A$356 million impairment already taken, would keep reported profit under pressure even if the core jobs platforms are tracking as hoped.
SEEK's current analyst story centres on revenues of A$1.5 billion and earnings of A$297.7 million by 2029. This is based on assumed 5.4% yearly revenue growth and a swing in earnings of about A$604 million from a loss of A$306.5 million today.
Uncover how SEEK's fair value indicates a 42% potential upside to its current price that may be short-lived.
Exploring Other Perspectives
One alternative view focuses on SEEK’s AI data advantage as the real swing factor. Before this Growth Fund call, the most optimistic analysts were working off revenue of about A$1.6b and earnings of A$337.1 million by 2029. That is far above consensus, and this Stage 2 update could easily shift both stories.
Explore 4 other SEEK fair value estimates, including one that suggests as much as 45% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SEEK research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SEEK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SEEK's overall financial health at a glance.
Looking For More Investment Ideas Beyond SEEK?
Once you have a view on SEEK, it can help to cross check that thesis against other opportunities that line up with your risk tolerance, income needs and time horizon. The Simply Wall St Screener is built for exactly that kind of side by side comparison.
- If capital preservation sits high on your list, start with companies that show resilient balance sheets and robust fundamentals through our list of solid balance sheet and fundamentals (12 results).
- If you prefer to focus on valuation and quality together, scan for businesses that combine strong cash generation with attractive pricing using the 2 high quality undervalued stocks.
- If reliable income matters most, shortlist potential payers that target higher yields and stability through the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com