


EN
What IMAX Buyers Were Betting On
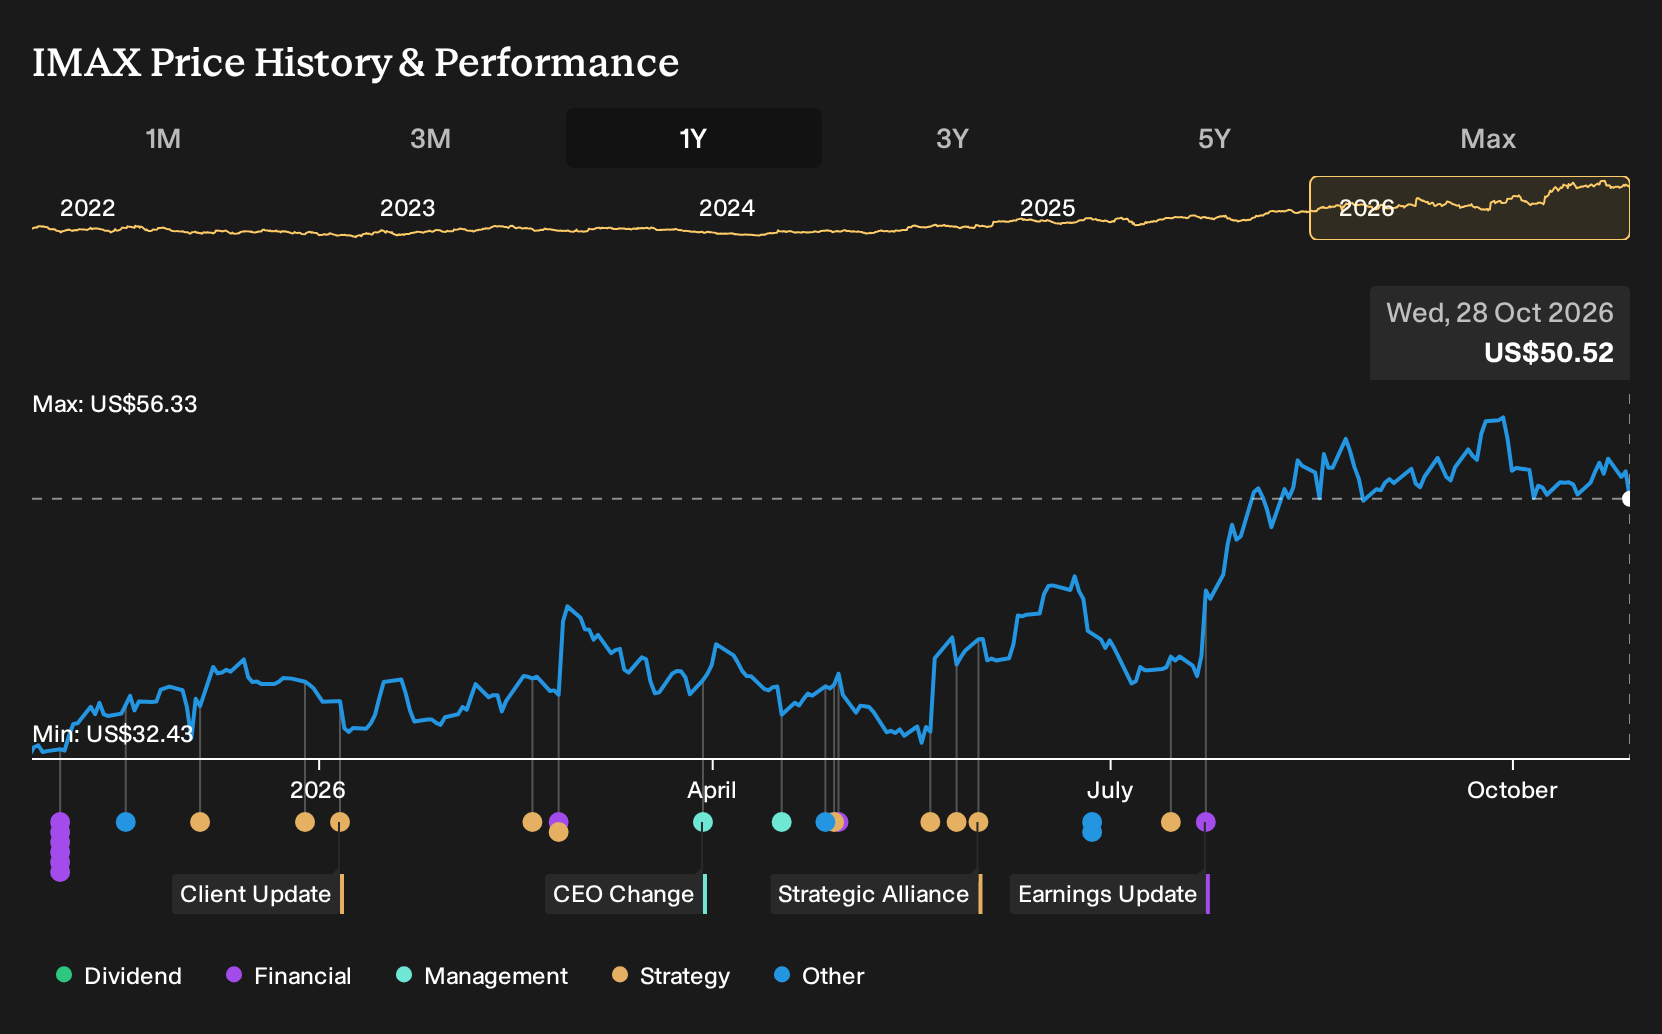
If you had backed IMAX a year ago, the outcome might surprise you. Holding IMAX over the past year would have returned 53.5%, including dividends. That result now sits alongside a year of record-breaking premium releases, fresh worries about streaming, and new experiments from in-vehicle screens to Asia-Pacific expansion. If you were weighing that decision on 28 October 2025, what would have mattered more: immersive growth stories or the risk that at-home viewing kept pulling audiences away?
If the move has made IMAX harder to judge, start where the gap is still open and scan 26 high quality undervalued stocks.
The Two IMAX Stories Investors Had To Hold In Their Heads
The shares cost US$32.77 at the start of the period, and anyone looking at IMAX then had to choose which of two very different stories sounded more realistic.
On the optimistic side, the bull narrative saw a Fair Value of US$38, a price implied by expectations of IMAX gaining a larger premium format share as its immersive technology and Asia-Pacific footprint expanded.
The bear narrative anchored to a Fair Value of US$18, built on the idea that rising at-home entertainment quality and weaker cinema habits for younger audiences could steadily shrink IMAX theater traffic.
What The IMAX Evidence Actually Pointed To
The most telling update came from IMAX’s Q2 2026 report. Revenue and net income were both higher than in Q2 2025, and net margin moved from 12.3% to 15.0%. That tilt toward stronger profitability backed parts of the optimistic case. At the same time, fresh in-vehicle and VR partnerships showed at-home and on-the-go viewing pressure was still real, so the evidence cut both ways.
The episode turned on one testable idea. When a story leans on premium experiences overcoming streaming, it is useful to track reported margin and new format deals side by side to see whether pricing power and partnerships are actually showing up in the numbers.
What IMAX’s Recent Run Already Prices In
Today IMAX trades at US$50.52 after returning 53.5% over the past year. The selected Narrative views fair value as above that level, framed around screen rollout, premium branding and a wider content mix supporting margins and cash generation.
The key judgment is whether IMAX can keep turning new premium screens and a broader slate into resilient, high incremental cash flow.
"The main thing that has to go right is that IMAX continues to convert its underpenetrated screen opportunity, strong box office titles such as The Odyssey, and growing local language and alternative content into sustained high incremental margins and recurring free cash flow."
One Narrative disagrees with today's price. → See where this Narrative says IMAX should trade
Where IMAX’s Story Connects
Once you have watched IMAX, attention can be hard to unsee. You are really betting on where people focus and how that focus gets used.
Cinemas direct that attention toward giant screens and premium seats. Another business points a different direction, turning watch time into finely targeted digital advertising.
Its tools help clients match ads to intent, power workplace software, and run AI-heavy computing behind the scenes.
The more time people spend searching, watching and working online, the more that infrastructure shapes how digital demand gets measured and sold.
That argument has a Narrative and a number behind it. → See the company one Narrative values 33% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com