


EN
Is Pacira BioSciences (PCRX) Stock Looking Stretched Or Reasonable?
Pacira BioSciences has seen its share price climb sharply over the past year, which naturally puts a spotlight on what investors are now paying for its earnings. With the stock changing hands at around US$36.39, the key issue is whether that price lines up with the profit power of the business.
- The 71.1% return over the past year raises the question of whether Pacira BioSciences' earnings are strong enough to underpin that kind of share price move.
- The company’s focus on commercializing non opioid pain treatments can influence how steadily profits convert from sales, which matters for how reliable its earnings base looks today.
- There is a second opinion on Pacira BioSciences worth weighing. See what analysts think Pacira BioSciences's shares could be worth.
The issue now is whether Pacira BioSciences' current share price is justified by the earnings that investors are effectively paying for.
If you are comparing Pacira BioSciences with other earnings-focused opportunities, it may be useful to evaluate it alongside a broader group of 26 high quality undervalued stocks.
Is Pacira BioSciences Getting Expensive on Earnings?
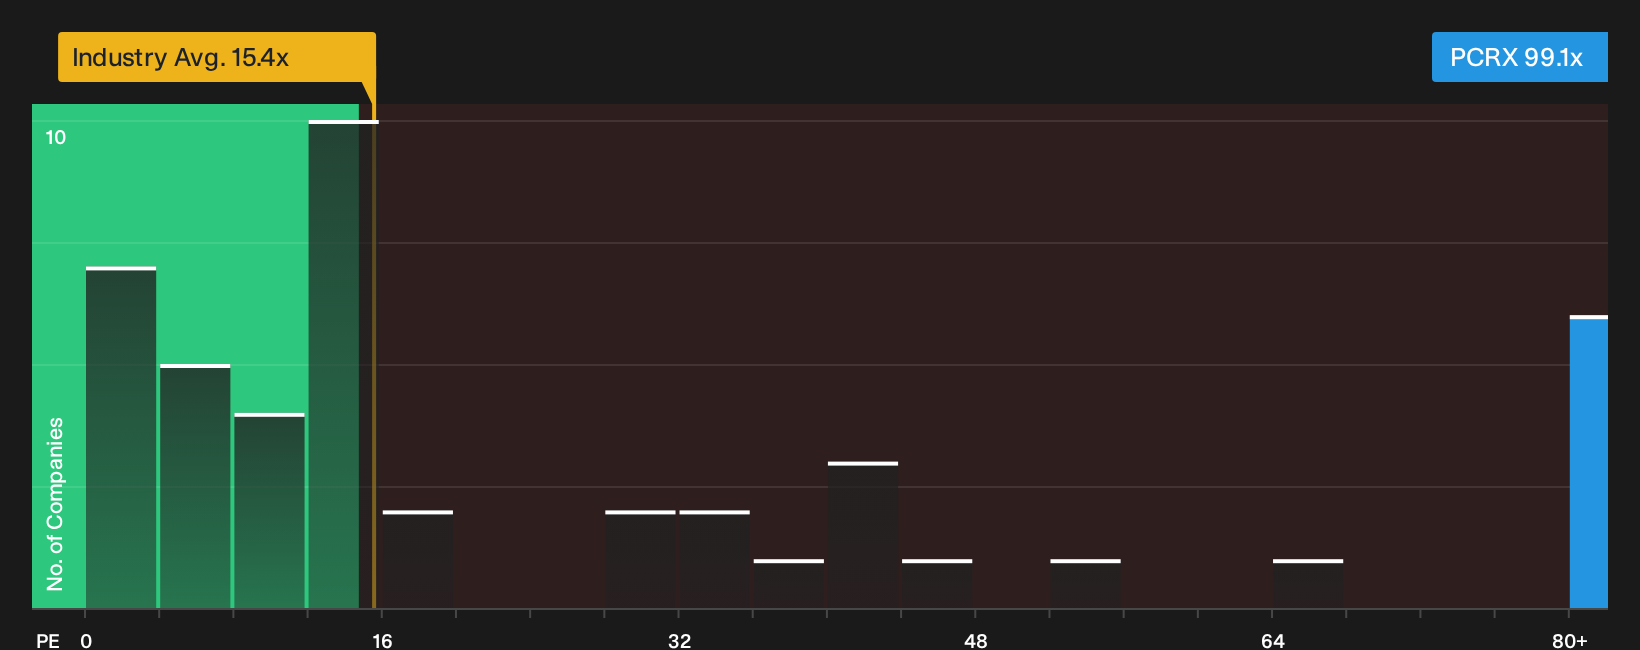
The P/E ratio fits Pacira BioSciences because investors are clearly focused on what they are paying for each dollar of profit. On this yardstick, the stock trades on a P/E of about 99.1x, compared with roughly 15.4x for the wider Pharmaceuticals industry and about 11.8x across its peer set.
The fair value framework, which adjusts for Pacira BioSciences' specific growth profile, profitability and risk, points to a materially lower P/E than the market is currently assigning. That gap is wide enough that the model is effectively flagging the shares as overvalued and heavily penalising the business on this metric. As a result, the implied fair multiple is better read as a warning signal than a precise target. For anyone assessing Pacira BioSciences today, the question is whether the earnings outlook and risk tolerance justify paying such a steep earnings multiple relative to both the tailored model and simpler benchmarks. Explore the numbers behind Pacira BioSciences's P/E valuation.
The Pacira BioSciences Narrative: What Would Justify Today's Price?
Narratives pick up where Pacira BioSciences' high P/E puzzle leaves off by spelling out which specific paths for growth, profitability and earnings would need to occur for the current share price to look either conservative or stretched. Each scenario links a fair value estimate to a particular mix of potential catalysts and risks, so you can track over time which version of Pacira BioSciences' story is gaining traction in the Community section on Simply Wall St.
Pacira BioSciences attracts two very different readings, with one camp seeing more embedded earnings power than the other at today’s price.
Bull case: roughly fairly valued
"The recent step up in non GAAP gross margin to roughly 80% reflects a higher structural level that, if maintained on a smaller SG&A base after the Zimmer divestiture, could translate into a sharper improvement in operating margin and earnings than current models assume..."
Discover why this Narrative puts Pacira BioSciences at roughly fairly valued.
Bear case: 8% overvalued
"Pacira BioSciences remains heavily reliant on EXPAREL and on supportive reimbursement policies, and the scheduled expiry of NOPAIN Act reimbursement at the end of 2027 introduces the possibility that a shorter or less favorable extension could reduce reimbursement support and compress revenue, operating margins and net income from current levels..."
Explore why this Narrative puts Pacira BioSciences at 8% overvalued.
Before you focus on Pacira BioSciences' valuation, there is one more angle to check
Price and earnings only tell part of the Pacira BioSciences story, and the research process has already thrown up specific risk flags that deserve your attention before you lean on any valuation work. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com