


EN
Akeso (SEHK:9926) Reports Phase III HARMONi GI1 Success, Is The Stock Cheap?
Akeso (SEHK:9926) is back in focus after reporting statistically significant Phase III HARMONi-GI1 results for ivonescimab plus chemotherapy in advanced biliary tract cancer, highlighted during presentations at the ESMO 2026 Congress.
Despite the positive HARMONi-GI1 data and other recent ivonescimab updates, Akeso’s share price has been under pressure, with a 30 day share price return down 21.45% and year to date share price return down 26.30%. At the same time, the 3 year total shareholder return is up 83.92% and the 5 year total shareholder return is up 116.60%, which suggests long term holders have still seen sizeable gains while recent momentum has cooled around the current HK$83.5 level.
Scan beyond Akeso and see how other biopharma stocks with fresh clinical or trial catalysts stack up by reviewing the 609 high quality undiscovered gems in this space.
Akeso now looks like a business with meaningful clinical momentum but a share price that has cooled sharply. The key tension is simple: Do the current HK$83.5 terms treat this as an opportunity or as a warning?
Most Popular Narrative: 46% Undervalued
Akeso’s most followed valuation narrative places fair value at about HK$154 per share, well above the current HK$83.5 level. This puts the recent pullback in the context of a much more optimistic long term earnings and cash flow story.
The company's strong R&D pipeline, including advanced bispecific antibodies and ADC candidates, provides a foundation for long-term growth, setting the stage for potential increases in net margins as products move from development to commercialization.
See why 3 investors see Akeso as 46% undervalued.
Result: Fair Value of HK$154 (UNDERVALUED)
Still, Akeso carries clear pressure points, including ongoing operating losses and heavy reliance on ivonescimab and cadonilimab to actually deliver on ambitious expectations.
Find out about the key risks to this Akeso narrative.
Another View On Akeso’s Valuation
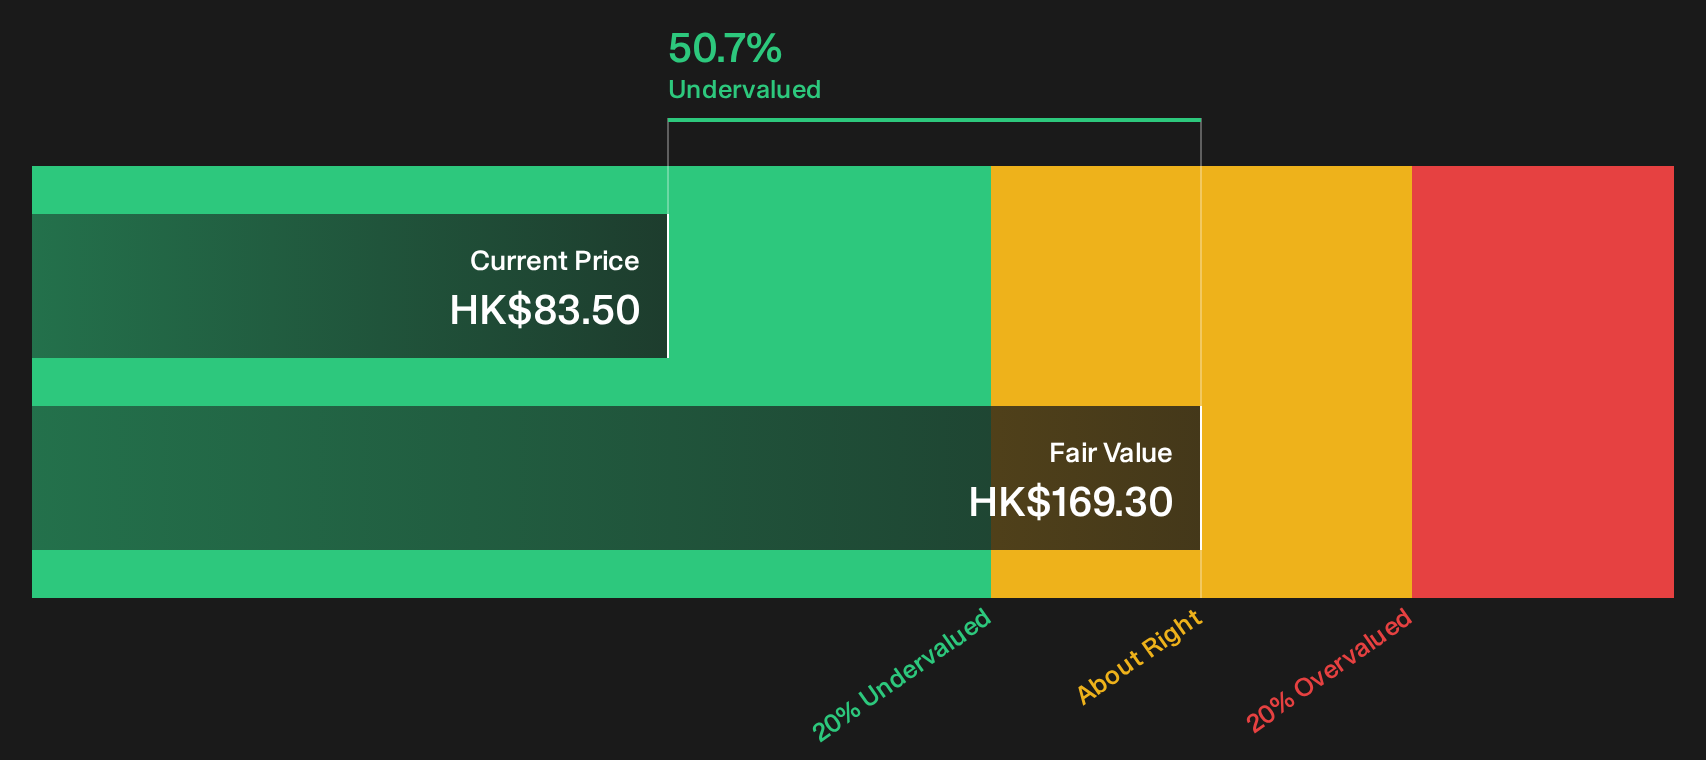
The SWS DCF model paints an even stronger case, with Akeso at HK$83.5 trading below an estimated future cash flow value of HK$169.3. That treats the current quote as heavily discounted. The key question is whether the cash flow path behind that number feels realistic to you.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on Akeso is clearly split, which is exactly when doing your own homework matters most. It can be worth moving quickly to pressure test both sides of the story using the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Akeso?
Do not stop with Akeso. Broaden your watchlist now and pressure test your thesis against other opportunities that match your risk, return, and income goals.
- Spot potential turnaround plays early by scanning the 131 elite penny stocks with strong financials that combine smaller market size with stronger financial filters.
- Hunt for quality at a discount by reviewing the 189 high quality undervalued stocks that pair healthier balance sheets with more attractive pricing.
- Build a steadier income stream by checking the 226 dividend fortresses that focus on higher yields with additional resilience checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com