


EN
What THK Doubters Overlooked
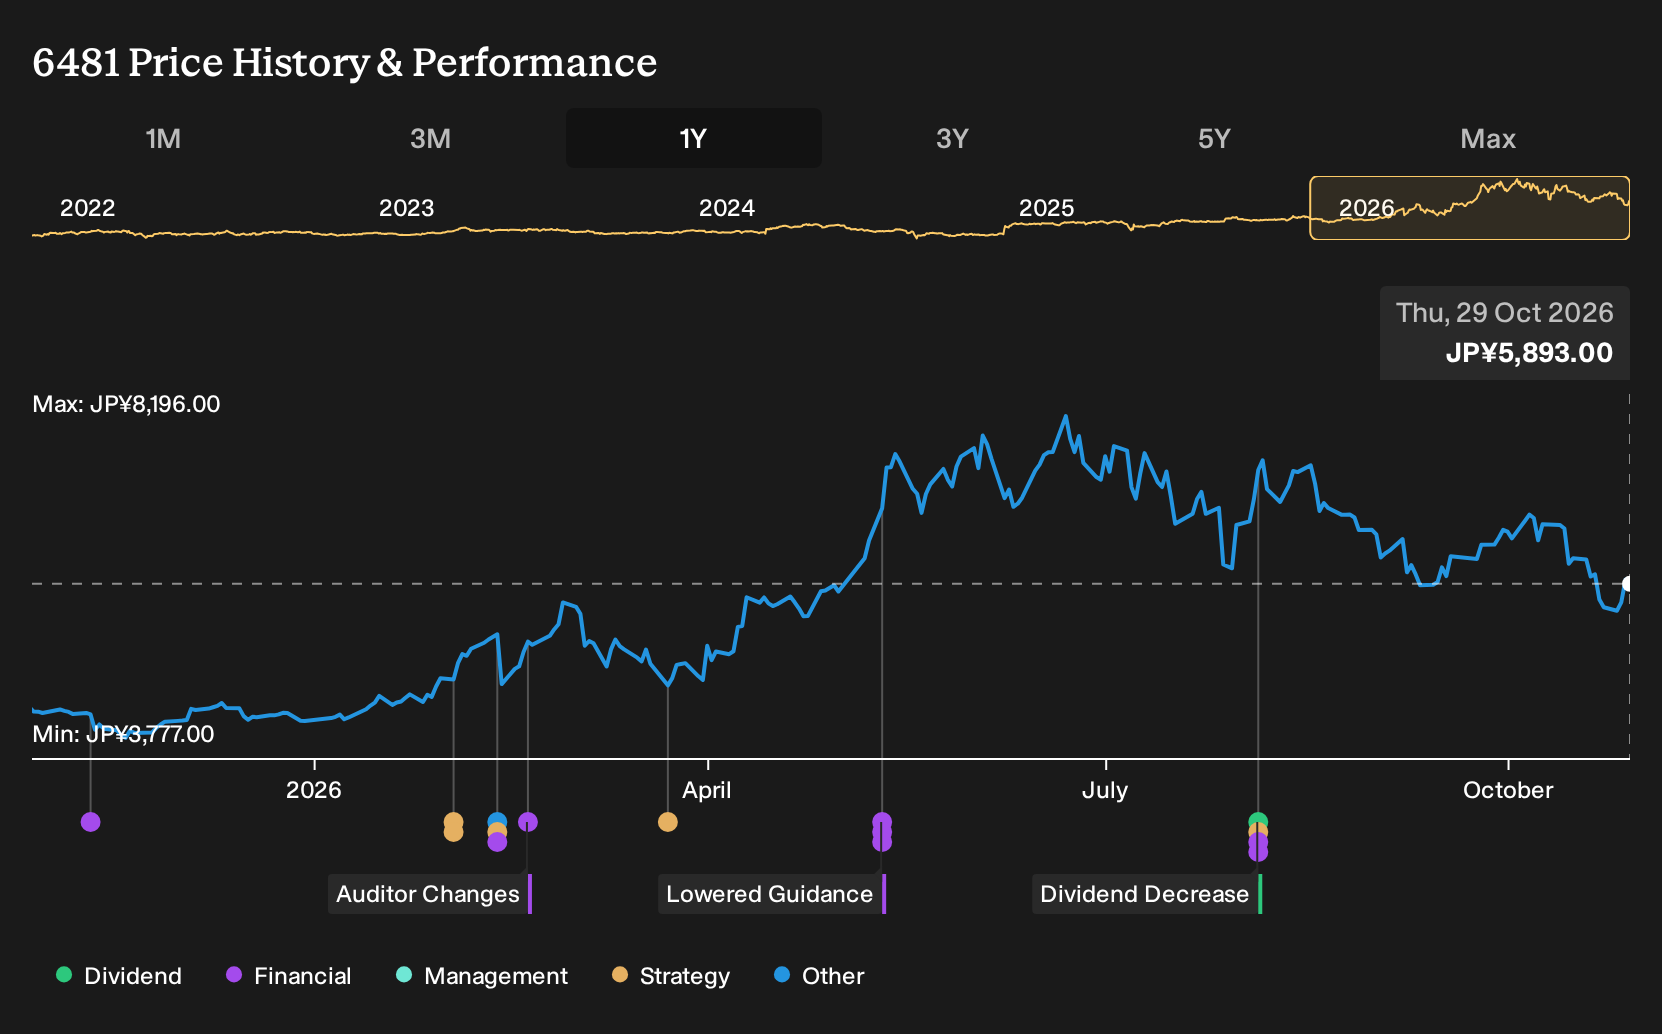
If THK sat on a watchlist instead of in a portfolio, the outcome over the past year may look like a painful missed call. For THK shareholders, the return over the past year was 48.8%, including dividends. That raises an obvious question. Back on 29 October 2025, when bulls were talking up digital transformation and faster product cycles while bears worried about commoditization and deglobalization, what evidence around THK’s push into AI and IoT modules could have helped you judge which story deserved more weight?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made THK harder to judge, start where the gap is still open and scan 15 high quality undervalued stocks.
Two Competing Stories Around THK
The shares cost ¥4,131 at the start of the period, and THK sat between two very different but reasonable stories about where its automation push might lead.
On the optimistic side, the bull narrative saw fair value at ¥5,000, assuming revenue growth of 6.8% a year and profit margins rising from 2.0% to 9.8% by 2028 as AI and IoT modules gained traction.
The bear view put fair value at ¥2,800, expecting revenue to decline 0.8% a year and warning that competition from lower cost Chinese and Korean rivals could keep pressure on pricing and margins.
What The Results Changed For THK
The clearest update came from THK’s Q2 2026 report. Revenue moved from ¥91,300m in Q2 2025 to ¥82,024m, which leaned toward the cautious case on growth. Net income rose from ¥3,408m to ¥13,246m and net margin shifted from 3.7% to 16.1%, which backed the bullish claim that restructuring and higher value automation could lift profitability. Overall, the evidence cut both ways.
The lesson is simple. When a thesis hinges on automation or AI lifting returns, track net margin alongside sales, not just headline revenue. Then check whether higher profitability arrives through cost reform or through clearly identified AI and IoT product lines in later filings.
What Today's THK Price Already Assumes
THK now trades at ¥5,893, and the selected Narrative places its Fair Value below that level. The gap reflects concern that earnings power may not fully match what the recent re-rating implies.
The Narrative leans on a view that structural shifts in automation and competition could outweigh internal reforms. For today’s price to make sense, a buyer would need confidence that THK can offset commoditization risk through faster transformation into higher margin FA and AI linked solutions.
"Rising competition from lower-cost Chinese and Korean rivals threatens to erode THK's pricing power, resulting in sustained gross and operating margin compression that will be compounded by structural industry commoditization; this limits margin recovery even if management executes its cost-cutting agenda."
The price and this Narrative do not agree. → Uncover what this Narrative says THK is actually worth
Which Company Could Surprise You Next?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 35% below our estimate - connects job seekers and service providers through hiring and lifestyle matching platforms.
- Company 2 - 37% below our estimate - focuses on specialist and mid-management placements via targeted recruitment and advisory channels.
- Company 3 - 31% below our estimate - supplies engineering talent through staffing, placement and senior specialist dispatch services.
Three companies from the same screener. Open all 23 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com