


EN
Is Oscar Health (OSCR) Stock Below Fair Value After New Products?
Oscar Health has surged over the past three years, and after such a powerful run, the real issue for investors is whether the current share price lines up with what the business is earning today. The stock’s recent pullback only sharpens the question of whether the earnings story is strong enough to support where Oscar Health now trades.
- Over the last three years, Oscar Health has delivered a very large share price gain, which raises the stakes on whether its earnings profile can carry that kind of move.
- Oscar’s newly announced 2027 product lineup, including entry into South Carolina and offerings like RetireEase and HelloMeno, can influence expectations for how quickly its health insurance earnings base might scale relative to its costs.
- Your read on Oscar Health is one view; the desks covering it have another. See what analysts think Oscar Health's shares could be worth.
The issue now is whether Oscar Health’s current market value is justified by its earnings when set against the Fair Ratio benchmark.
If you want to test the same earnings versus price question beyond Oscar Health, you can line it up against other insurers and health names using 36 healthcare AI stocks.
Is Oscar Health a Bargain on Earnings?
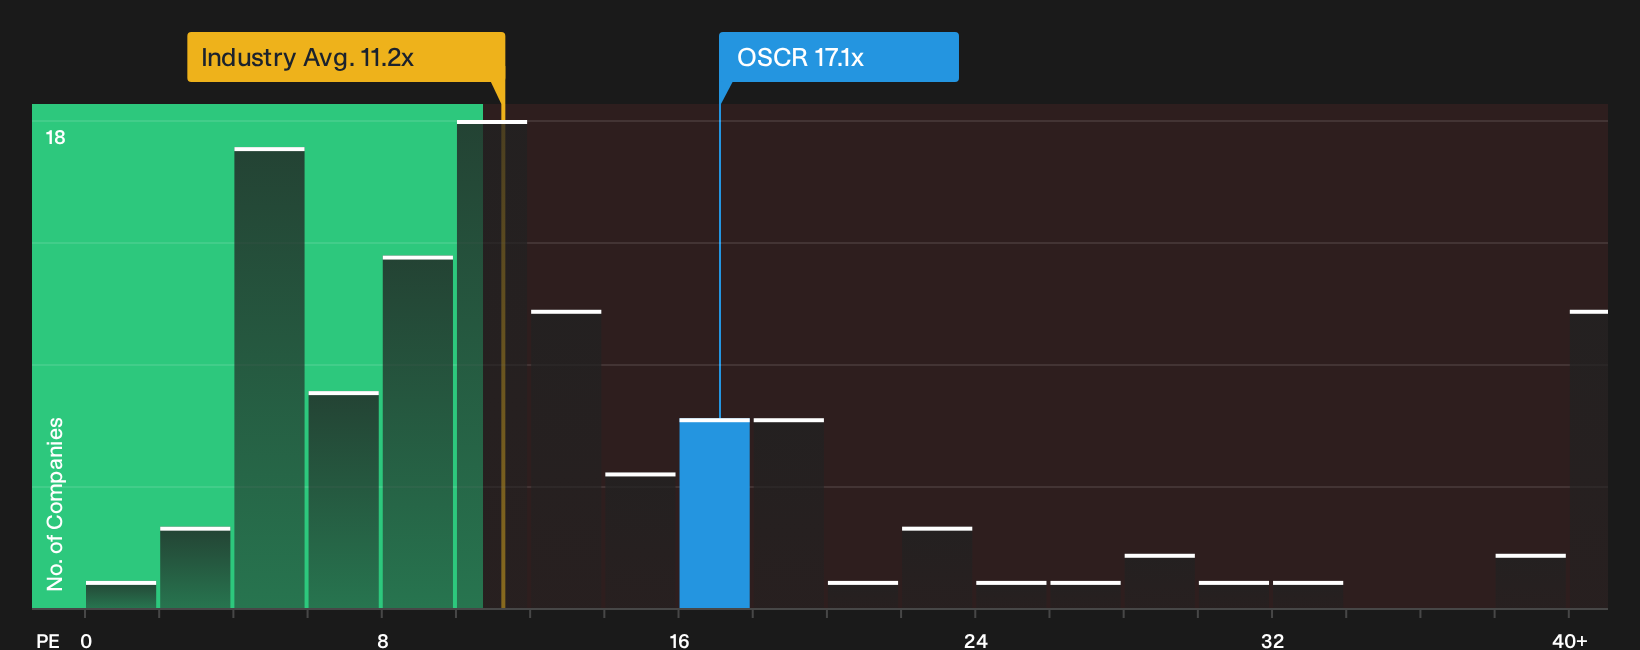
The P/E lens suits Oscar Health because the story investors care about here is the path of earnings relative to the share price. On that yardstick, Oscar trades on a P/E of 17.1x, which is below both the broader insurance industry average of 11.2x and the peer group’s 33.6x, so the stock changes hands at a level that sits between sector pricing and more growth‑tilted competitors.
Because the 2027 product lineup expands Oscar Health’s reach and mix of offerings, the Fair Ratio framework, which blends growth, margins, scale and risk, points to the current 17.1x sitting below the multiple you might expect for this business. Because that expansion story is already known to the market, the valuation signal here is that the stock screens as undervalued on earnings compared with what that tailored benchmark implies. Explore the numbers behind Oscar Health's P/E valuation.
The Oscar Health Narrative: What Would Justify Today's Price?
Oscar Health’s valuation puzzle only really makes sense once you spell out the future it implies. This is what Simply Wall St Narratives aim to do on the Community page by mapping what would need to happen to growth, margins and earnings for the stock to be worth materially more or less than it is today. Each narrative sets up fair value as a concrete thesis about Oscar Health’s business that you can revisit over time and see how it holds up against actual results.
The Oscar Health community splits sharply between a deep value story and a more cautious view that current enthusiasm already reflects a lot of good news.
Bull case: 95% undervalued
"Suspicious of a value trap, I started digging into the operational engine to find the catch. Instead, the deeper I dug, the more the moat began to show…"
Discover why this Narrative puts Oscar Health at 95% undervalued.
Bear case: 13% overvalued
"While Oscar Health points to AI driven efficiencies and a lower SG&A ratio as support for its cost position, the scale of CMS program integrity reviews that are expected to cancel unauthorized ACA enrollments introduces a structural risk…"
Explore why this Narrative puts Oscar Health at 13% overvalued.
Oscar Health’s valuation leaves one more crucial piece off the table
Everything so far has focused on what Oscar Health looks like today, yet analysts have already sketched out where they think this business could be a few years from now. Explore where analysts expect Oscar Health to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com