


EN
Jio Platforms Stock After The IPO Plus Telecom Shares Worth A Closer Look
Jio Platforms’ blockbuster IPO debut, with shares listing at a premium of more than 25%, has turned Indian telecom and digital platforms into the main story on Dalal Street and put Jio Platforms itself under a bright global spotlight. This kind of momentum can quickly reprice expectations, which means both opportunity and risk for you. This article walks through 3 large-cap telecom and digital stocks exposed to this news and explains why each one now deserves closer attention.
The three companies covered below are only a sample of the opportunities around Jio Platforms’ IPO, and the full large-cap telecom and digital-platform screen surfaced 11 more India-listed firms with equally compelling narratives that are not unpacked in this article. To see the wider field and identify which ideas match your own risk, sector and valuation preferences, go straight to the Indian large-cap telecom & digital platforms screener.
Indus Towers (NSEI:INDUSTOWER)
Overview: Indus Towers operates telecom towers and digital infrastructure that support mobile networks and data services for large operators in India and select African markets.
Market Cap: ₹983.68b
Indus Towers gives you exposure to the telecom and digital-platform theme not through consumer apps, but through the physical grid that keeps rising data usage online.
"Although Indus Towers cites data driven demand with 31% YoY growth in total data consumption and 87% YoY growth in 5G traffic, the continued energy margin losses, which were at a decline of 4.6% in Q1 FY27, mean each incremental tower or colocation can add volume without materially improving net margins or earnings quality."
One question for investors is what could change if a single pressure on Indus Towers’ cost base shifts while the underlying demand story continues.
If that cost shift is what you are watching, the full narrative for Indus Towers outlines how tower demand, tariffs and energy terms could be quietly decoupling.

Jio Platforms (NSEI:JPL)
Overview: Jio Platforms runs a large Indian telecom network across 4G and 5G and layers on consumer and enterprise digital services from streaming to cloud.
Operations: Jio Platforms generates ₹1.47t in revenue from digital services, platforms, applications and software, all currently reported from India.
Market Cap: ₹13.05t
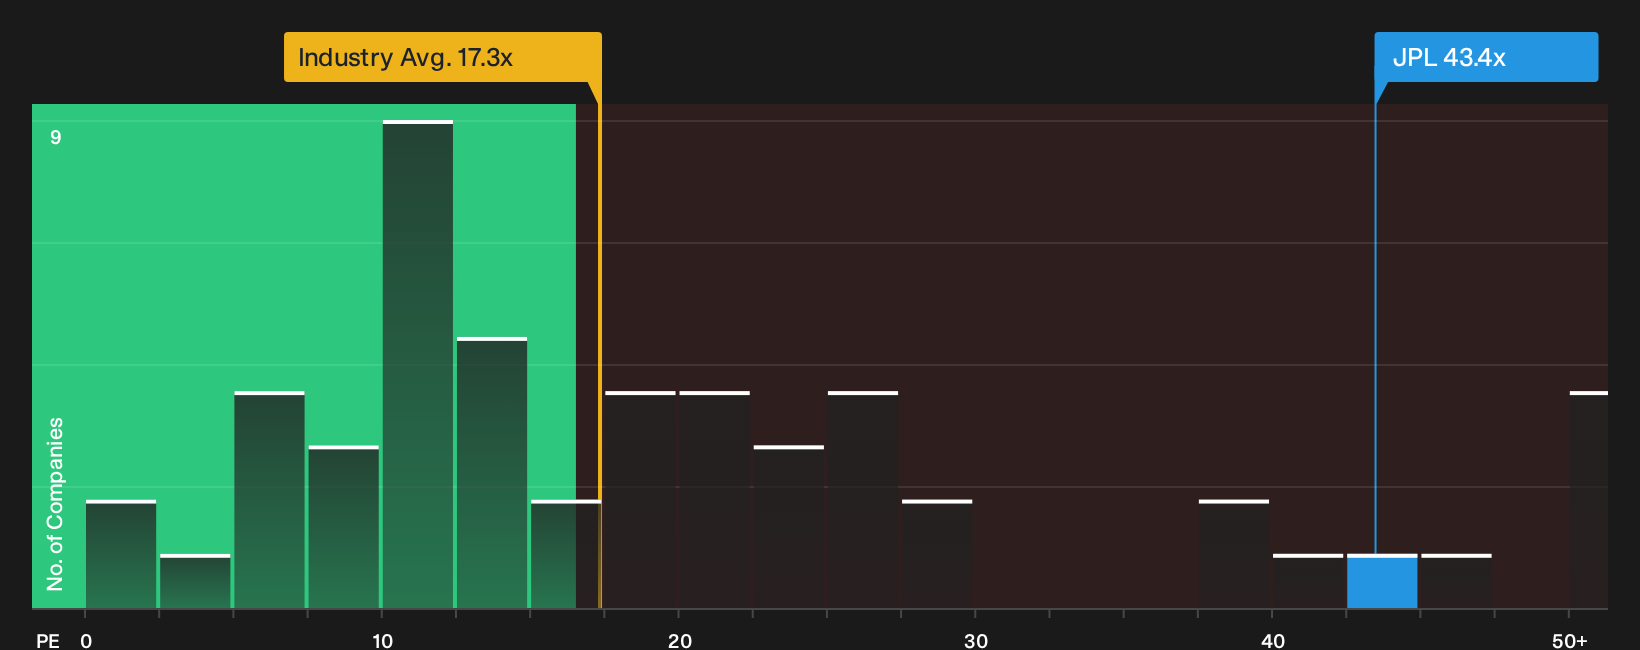
Jio Platforms is a pure-play telecom and digital platform company with a ₹13.05t valuation and fresh IPO funding. The company provides direct exposure to India’s data and app economy. However, with a 43.4x P/E and all funding coming from external borrowings, a change in how investors weigh growth relative to that capital structure could be significant.
That trade off between growth and leverage is exactly what the analysis report for Jio Platforms unpacks, so you can see where Jio Platforms’ story could accelerate next
Bharti Hexacom (NSEI:BHARTIHEXA)
Overview: Bharti Hexacom runs Airtel branded mobile, fixed-line and broadband services, giving direct exposure to Indian telecom and digital connectivity demand.
Operations: Bharti Hexacom generates roughly ₹92.1b from Mobile Services and ₹4.3b from Homes and Office Services, after small eliminations.
Market Cap: ₹832.7b
Bharti Hexacom plugs into the same Indian data traffic story as Jio Platforms, yet approaches it through a more regionally focused, cash-generative telecom footprint under the Airtel umbrella.
"Very high operating free cash flow relative to net debt, with INR 830 crores of operating free cash flow in Q1 FY27 against net debt of INR 960 crores and net debt to EBITDA at 0.2x, gives Bharti Hexacom room to tilt more towards shareholder returns over time."
What really matters now is how one quiet shift in spending priorities could reshape both resilience and income potential for Bharti Hexacom.
That potential shift in capital allocation is exactly what the full narrative for Bharti Hexacom unpacks, highlighting where Bharti Hexacom’s cash profile could be masking bigger upside and emerging risks.
Seeking Alternatives Before Momentum Flies
Fresh breakout stories rarely stay under the radar for long. Once momentum builds, entry points can get caught chasing. Scan these ideas before the crowd and act now.
- Spot resilient cash engines that still trade on quieter risk scores by running the 229 resilient stocks with low risk scores while that edge is under the radar for now.
- Hunt for strong balance sheets backing real earnings power through the curated list of solid balance sheet and fundamentals (202 results) before that quality premium gets fully priced in.
- Track where robotics demand is building quietly, then use the hand picked 96 robotics and automation stocks to identify potential breakout names before momentum sends them higher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com