


EN
How Investors Are Reacting To Vend Marketplaces (OB:VEND) Return To Profitability
- Vend Marketplaces reported third quarter 2026 basic earnings per share from continuing operations of NOK 21.29, compared with a basic loss per share of NOK 3.50 in the same period a year earlier.
- The sharp swing to positive earnings per share in the quarter contrasts with year to date losses from continuing operations. This highlights how volatile the earnings profile has been through 2026 so far.
- The focus now shifts to how Vend Marketplaces' sudden quarterly swing to positive EPS might influence the existing investment narrative around the business.
Vend Marketplaces Investment Narrative Recap
For a shareholder in Vend Marketplaces, the core belief is that its online platforms in Mobility, Real Estate, Jobs and Recommerce can convert strong user engagement into steadier earnings over time. The Q3 EPS swing to NOK 21.29 sits against a nine month loss from continuing operations, so it mainly underlines how sensitive results still are to one off factors and quarterly timing.
The key short term catalyst remains execution on cost transformation and portfolio simplification while traffic and advertiser volumes hold up. The biggest risk is that structural volume pressure and the phaseout of TSA revenues hit 2026 profitability harder than planned. This quarter’s EPS jump does not remove that execution risk.
The third quarter and nine month earnings announcement is the most relevant update right now because it gives a fresh read on how Vend Marketplaces is absorbing the planned TSA revenue phaseout and ongoing HQ deficits. Investors can see basic EPS at NOK 21.29 in Q3, yet a basic loss per share from continuing operations of NOK 3.78 for the nine month period.
This mix of one strong quarter and weaker year to date numbers matters for any thesis built around margin expansion and ARPA initiatives in Mobility and Real Estate. It keeps the spotlight on whether cost actions, portfolio simplification and scaling of higher margin transactional models can offset volume pressure and Recommerce losses without relying on sporadic EPS spikes.
Vend Marketplaces' published narrative points to forecast revenues of NOK 7.5 billion and earnings of NOK 1.8 billion by 2029, based on analyst estimates. This implies a projected earnings increase of about NOK 300 million from current earnings of NOK 1.5 billion and incorporates an assumed 3.3% yearly revenue decline over the next three years.
Uncover why Vend Marketplaces' fair value indicates a 55% potential upside to its current price, which could narrow quickly.
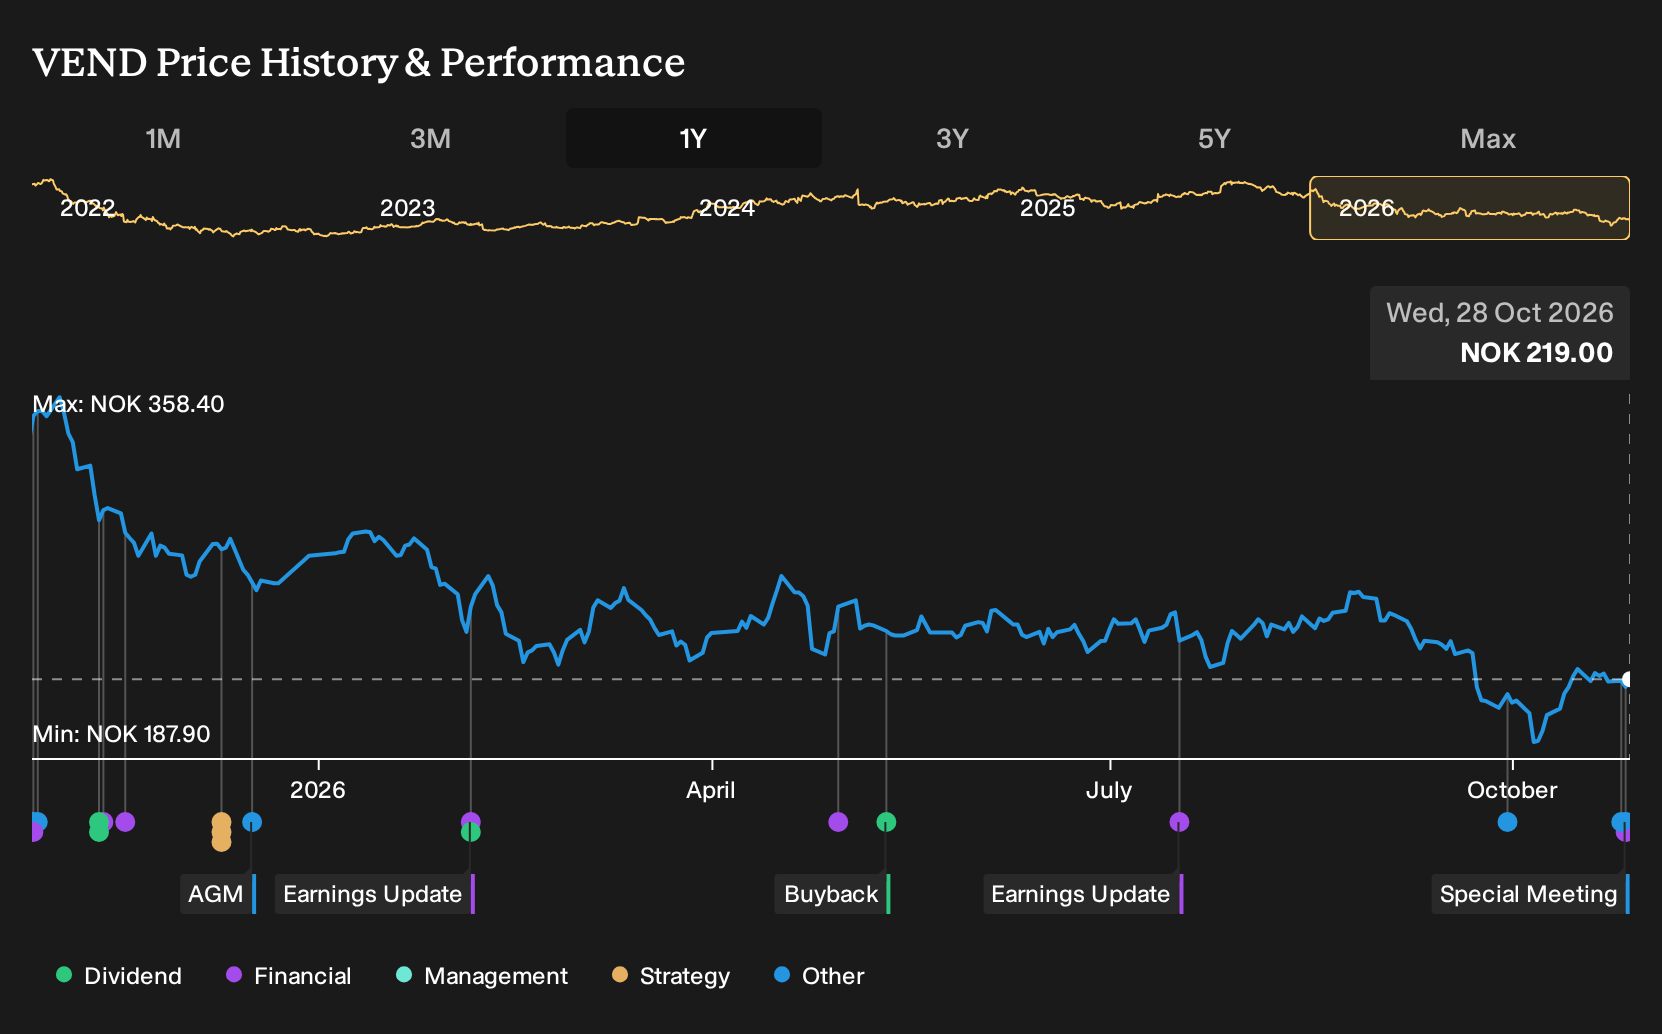
Exploring Other Perspectives
One alternate view on Vend Marketplaces leans hard into the risk that volume softness drags on longer than expected. The most cautious analysts were pencilling in revenue of about NOK 6.7b and earnings near NOK 1.4b by 2028, with EPS of NOK 6.91. That is meaningfully lower than consensus, and it sets up a very different story if this latest EPS spike leads them to revisit those older assumptions. You can treat this Q3 surprise as your cue to compare both sets of forecasts and decide which camp you find more convincing.
Explore 2 other Vend Marketplaces fair value estimates, including one that suggests it could be worth just NOK264.60!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vend Marketplaces research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Vend Marketplaces. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vend Marketplaces' overall financial health at a glance.
Looking For More Investment Ideas Beyond Vend Marketplaces?
Once you have a handle on Vend Marketplaces, it can help to compare this thesis with a few very different types of opportunities surfaced by the Simply Wall St Screener.
- If you want potential mispricing combined with solid fundamentals, scan through a curated set of 192 high quality undervalued stocks that already pair quality with attractive pricing signals.
- For investors who care most about resilience, filter the market for 229 resilient stocks with low risk scores that score well on Simply Wall St's risk framework and may help smooth out portfolio swings.
- Income focused readers can look at companies prioritising cash returns to shareholders by reviewing a targeted group of 225 dividend fortresses that offer higher yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com