


EN
Is Navigator Company (ENXTLS:NVG) Undervalued On Weaker Nine Month 2026 Results?
The Navigator Company (ENXTLS:NVG) just reported nine-month 2026 figures that showed sales of €1,333.3m and net income of €65.37m, both below the prior-year period.
The latest nine month results landed as the share price has softened, with a 30 day share price return of down 5.79% and a year to date move of down 4.61%, while total shareholder return over the past year is still up 4.42%. This suggests recent momentum in Navigator Company has faded, even though longer term holders with a 5 year total shareholder return of 29.60% remain ahead overall.
Review how Navigator Company fits into a wider watchlist and compare its recent setback with a curated 192 high quality undervalued stocks that currently screen well on both cash flows and balance sheets.
After a weaker nine months and a softer share price, the real fork in the road for Navigator Company is simple. Is this a reasonable entry point now, or does patience for a cheaper valuation make more sense?
Most Popular Narrative: 17% Undervalued
The most followed narrative on Navigator Company pegs fair value at €3.68 per share, above the latest close of €3.06. This frames recent share price weakness against a still-supportive valuation story built on packaging and tissue expansion.
Robust expansion into sustainable packaging and tissue segments, supported by major investments such as the PM3 machine conversion and molded cellulose product lines, positions Navigator to benefit from the global shift towards plastic bans, circular economy policies, and rising demand for renewable packaging, supporting future revenue growth and higher margins as these products command premium pricing relative to legacy paper.
See why 49 investors see Navigator Company as 17% undervalued.
Result: Fair Value of €3.68 (UNDERVALUED)
Still, the Navigator Company story can shift quickly if digitalisation continues to eat into printing demand or if rising energy and chemical costs have a greater impact.
Find out about the key risks to this Navigator Company narrative.
Another View: What The P/E Ratio Says About Navigator Company
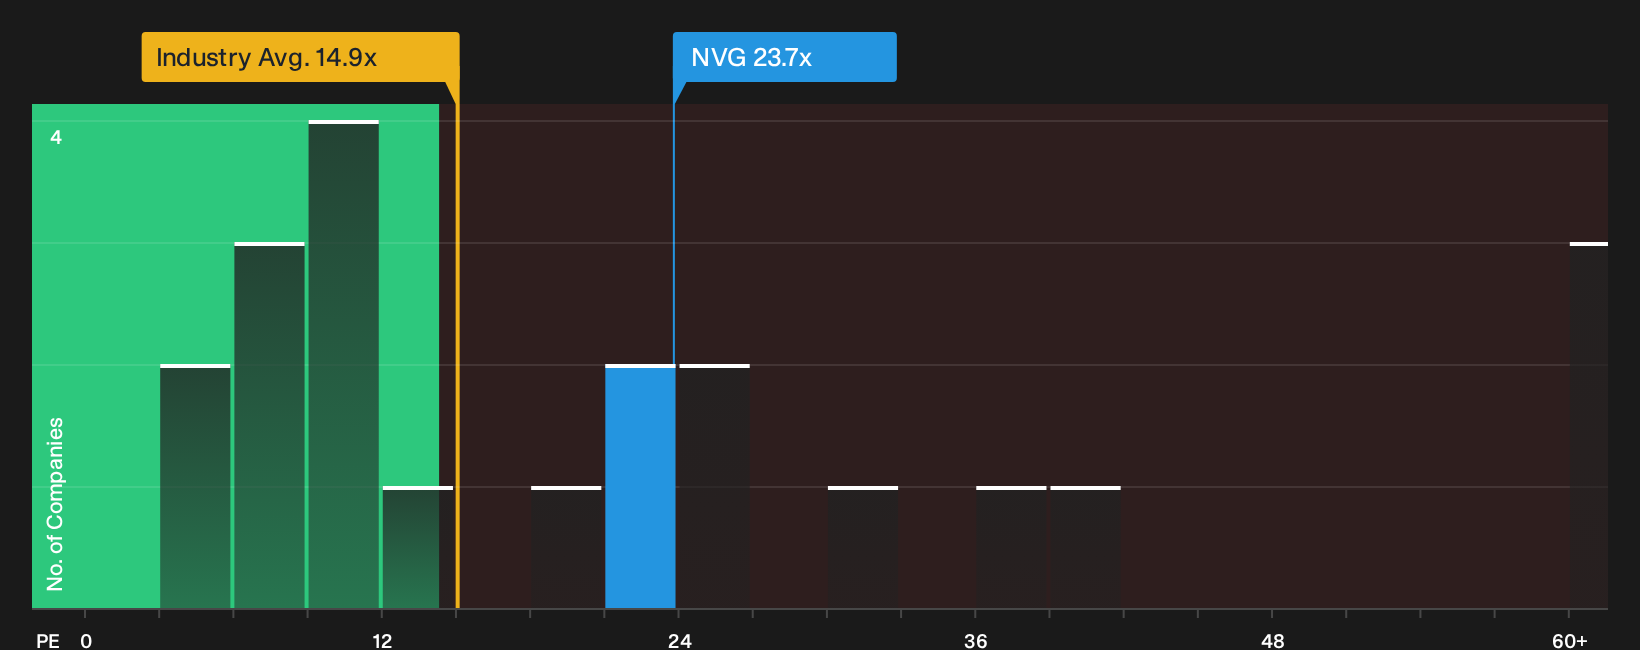
The SWS DCF work-up points to upside, yet the simple P/E lens tells a more cautious story. Navigator Company trades on 23.7x earnings, compared with 14.9x for the global forestry group and 36.2x for peers, while the fair ratio sits even higher at 38.9x.
That spread means the stock carries a richer multiple than the wider industry but still sits below what the fair ratio suggests the market could move towards. This leaves you deciding whether this gap signals valuation risk or a potential opportunity if sentiment shifts.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on sentiment can be helpful. Use them as a prompt to review the data, pressure test your thesis, and weigh up 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Navigator Company?
If Navigator Company has you rethinking your next move, use that momentum to scan fresh opportunities before the market leaves you behind.
- Target potential mispricing by reviewing companies that screen well on quality and valuation through our 192 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with strong finances using the list of solid balance sheet and fundamentals (203 results).
- Hunt for under-followed opportunities by checking a curated pool of 609 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com