


EN
Should Distribution Hike Require Action From MPLX (MPLX) Investors?
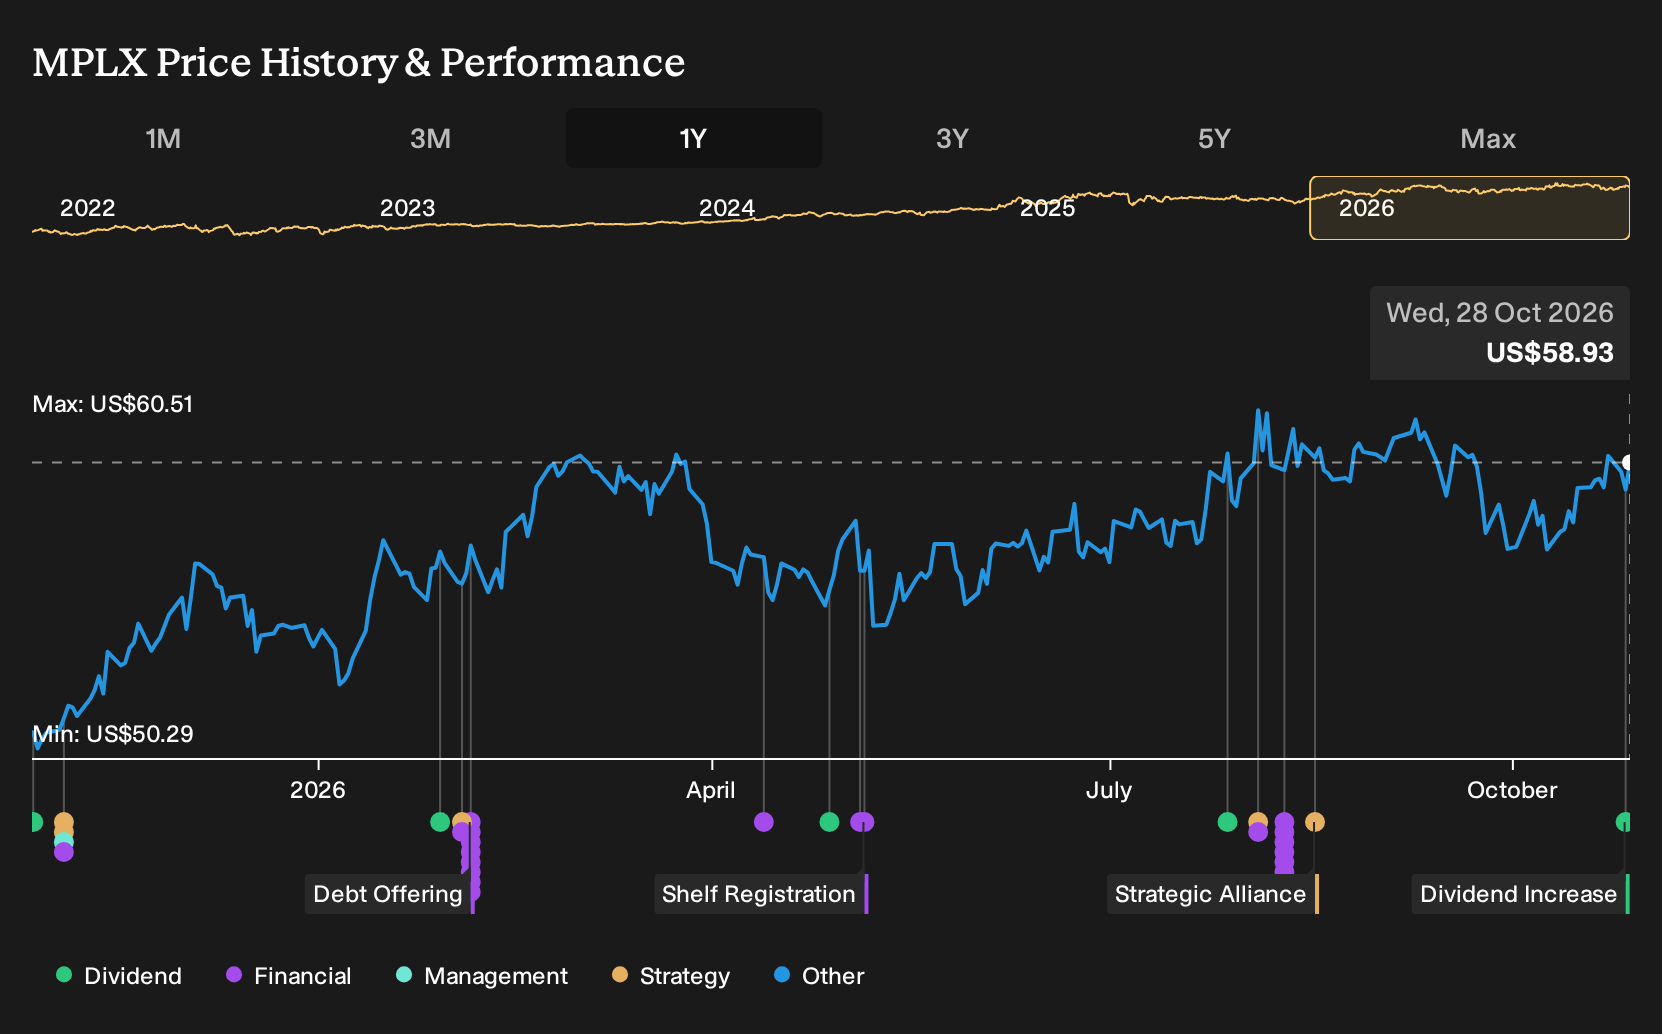
- MPLX declared a quarterly cash distribution of $1.2111 per common unit for Q3 2026, equal to $4.84 annualized, a 12.5% or $0.1346 per unit increase from Q2, with payment made on November 13, 2026, to unitholders of record on November 6, 2026.
- The 12.5% distribution uplift signals that MPLX is allocating a larger share of cash to unitholders at a time when its gas and NGL projects and acquisitions are tying future payout capacity directly to execution on high utilization midstream infrastructure.
- We will now look at how MPLX's 12.5% distribution increase could reshape the investment narrative built around its gas infrastructure projects.
MPLX Investment Narrative Recap
To own MPLX, you need to be comfortable with a midstream partnership that leans heavily on gas and NGL infrastructure, high utilization on processing plants, and long haul Permian takeaway. The key short term swing factor is execution on projects like Secretariat I, Harmon Creek III, Titan and Solitude, because throughput and fee based cash flows hinge on keeping volumes moving.
The 12.5% distribution uplift does not change those core drivers. However, it does tighten the link between capital projects and payout capacity. The biggest near term risk remains capital intensity and funding. Higher debt costs, weaker returns on the 2026 US$2.9b capex plan or softer Permian and Delaware drilling could pressure coverage and reported earnings.
The fresh distribution increase matters most alongside MPLX’s recent buildout in natural gas and NGL services, including Northwind Midstream and full ownership of the BANGL pipeline. Those assets, combined with rising utilization in the Marcellus and Delaware systems, frame how much room there is to sustain a richer cash return profile while funding new projects.
For an income focused holder, the link between this higher payout and the gas project slate is direct. Execution on expansions like Titan, Secretariat I and Harmon Creek III, along with longer term Solitude pipeline plans to connect Permian supply to Gulf Coast demand centers, will likely influence how MPLX balances leverage, spending and future distributions.
MPLX Forward Earnings and Revenue Setup
MPLX's narrative projects US$15.8b revenue and US$5.6b earnings by 2029. This projection is based on 9.5% yearly revenue growth and an earnings increase of about US$0.9b from US$4.7b today.
Uncover why MPLX's fair value indicates a 7% potential upside to its current price before the window for that discount narrows.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$62.85 to US$129.96 per unit, which shows how far opinions on MPLX can stretch. Those estimates were set before the 12.5% distribution hike and ongoing US$2.9b capex program, so you should weigh both payout ambition and project execution risk, then explore the full spread of community opinions.
Explore 2 other MPLX fair value estimates, including one that suggests as much as 121% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your MPLX research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MPLX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MPLX's overall financial health at a glance.
Looking For More Investment Ideas Beyond MPLX?
Once you have a view on MPLX, it can be useful to line it up against a broader watchlist so you can see where the trade offs really sit for income, quality and risk.
- If you want income without stretching too far on quality, compare MPLX with a 6 dividend fortresses that focus on consistency of cash distributions.
- For investors hunting for a margin of safety, weigh MPLX against a 26 high quality undervalued stocks that combine solid balance sheets with supportive cash flows.
- If you prefer to cast a wider net and look for less crowded opportunities, set MPLX alongside a 19 high quality undiscovered gems that still screen well on fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com