


EN
Terex Stock Earnings Beat And $500 Million Buyback What's Changed
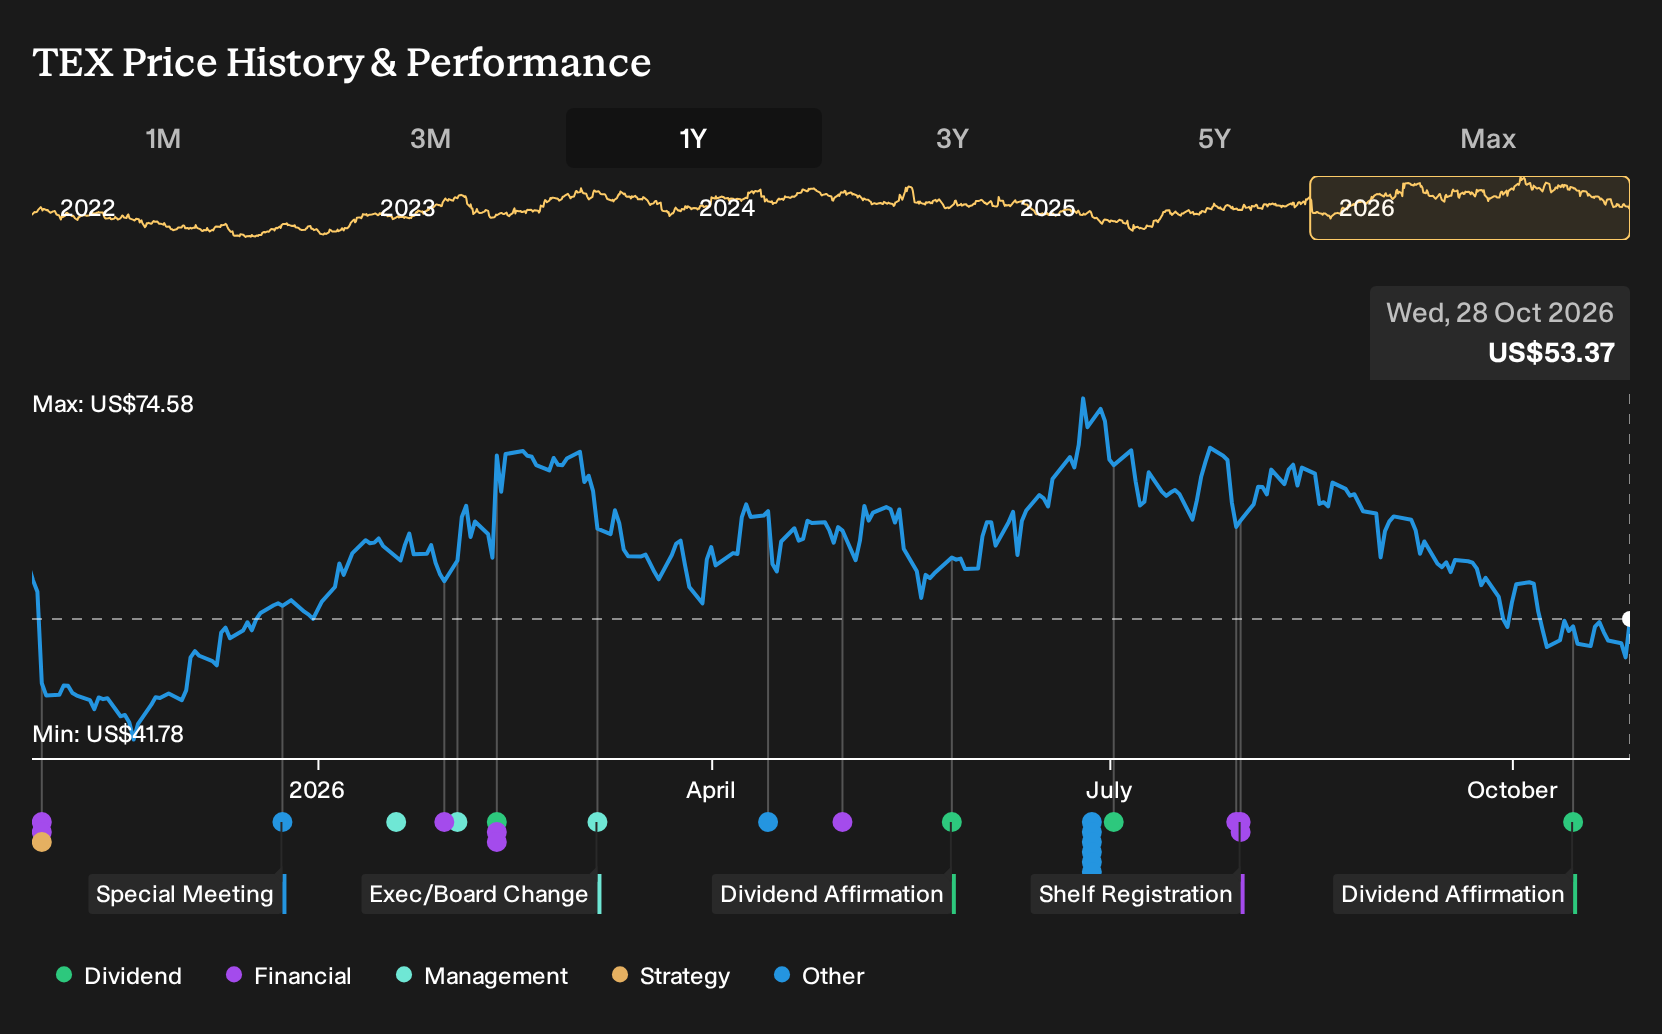
- Terex reported Q3 2026 sales of US$2.20b and net income of US$114m, refined full year revenue guidance to a range of US$8.0b to US$8.2b, and announced a new US$500m share repurchase authorization alongside a US$0.17 quarterly dividend.
- The combination of higher quarterly earnings per share, a large buyback plan, and continued dividend payments highlights Terex management's focus on shareholder returns as it progresses the Aerials segment separation and manages demand across its core equipment lines.
- The next area of attention is how Terex's stronger quarter and new US$500m buyback may influence the existing investment narrative.
Scan how Terex's latest buyback and dividend move compare with other machinery players returning cash to investors through our hand picked 44 power grid technology and infrastructure stocks.
Terex Investment Narrative Recap
To back Terex as a shareholder, you need to be comfortable with a construction and infrastructure cycle story that leans on a large backlog, policy supported spending and the Aerials separation to keep equipment utilization healthy. The Q3 update, with US$2.20b in sales and higher quarterly EPS, supports that operating thesis but does not remove macro sensitivity.
The main near term swing factor remains margins and cash generation as Terex manages mix across MP, Aerials and Environmental Solutions while interest costs stay relevant and Environmental Solutions faces a softer refuse backdrop. The biggest risk is a pullback in customer capital spending or further pressure on segment profitability, which would feed quickly into earnings quality.
The new US$500m share repurchase authorization is the clearest incremental datapoint alongside the Q3 Terex release. It reinforces that management expects to have room on the balance sheet and cash flow to retire stock while still funding equipment capacity and the Aerials separation, although interest coverage has been flagged as a weakness.
For you, the buyback matters if you think Terex can execute on its refined US$8.0b to US$8.2b sales outlook while protecting margins in Environmental Solutions and Aerials. If order intake softens or profitability compresses further, the practical pace of repurchases and the support they provide to EPS could end up more limited than the headline size suggests.
Terex's narrative projects US$9.5b revenue and US$974.5m earnings by 2029. This implies a 12.5% yearly revenue growth rate and requires roughly a US$829.5m earnings increase from US$145.0m today.
Discover how Terex's fair value points to a potential 50% upside from its current price before the market closes the gap.
Exploring Other Perspectives
One alternate Terex angle presents the Aerials separation as the key catalyst. The most optimistic analysts were already modeling revenue of about US$10.2b and earnings near US$1.0b by 2029 before this Q3 beat, the refined US$8.0b to US$8.2b guidance and the US$500m buyback. You can compare that stronger story with more cautious views and decide which assumptions feel realistic.
Explore another Terex fair value estimate, including one that suggests up to 78% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Terex research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Terex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Terex's overall financial health at a glance.
Looking For More Ideas Beyond Terex?
After assessing Terex, it can help to widen your opportunity set and compare it with other companies that match the kind of risk, quality, or income profile you prefer.
- If resilience and balance sheet strength sit at the top of your checklist, start with a list of solid balance sheet and fundamentals (24 results) that meet stricter financial health criteria.
- For investors who want growth potential paired with reasonable pricing, scan through a 26 high quality undervalued stocks that combine quality fundamentals with undemanding multiples.
- If reliable income is a priority, focus on a 6 dividend fortresses that aim to pair higher yields with business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com